In October 2014, Lawrence B. Sorrel agreed to discuss an office lease that still had nearly three years to run. Tailwind Capital had enough room. The furniture did not need an emergency evacuation. By the ordinary office calendar, there was little reason to hurry. Yet Sorrel and the firm’s chief financial officer, Sean Gagnon, took the meeting. The interesting deadline belonged to their landlord.
Ten of the twelve tower floors at 485 Lexington Avenue had leases expiring in 2017 or earlier. That concentration gave a tenant something to consider before its own expiry date became urgent. Tailwind eventually renewed, with an allowance to improve its space. A commercial lease is an unlikely opening to an investment career. It does, however, supply a useful question: whose calendar are you watching?
A long apprenticeship before his own front door
Sorrel, known professionally as Larry, co-founded Tailwind in 2003. He arrived with experience at Morgan Stanley and Welsh, Carson, Anderson & Stowe. His education crossed three institutions: a bachelor’s degree from Brown University, a law degree from Harvard Law School and an MBA from Harvard Business School. Contracts and capital both had a place in the preparation.
He joined Morgan Stanley in 1986 and became a managing director in its private equity business. From 1998 to 2002, he was a general partner at Welsh Carson. His responsibilities there included membership of the management and investment committees. Before becoming a founder, he had worked inside organizations where decisions about buying businesses came with colleagues, committees and obligations to investors.
That sequence matters to his story. Tailwind was an entrepreneurial undertaking by an investor who already knew institutional investing. The leap was from making decisions within an established organization to helping build an organization that could make them repeatedly. A firm needs people who can assess the next acquisition. It also needs people who will still be there to manage the last one.
- 1986Morgan Stanley
- 1998Welsh Carson
- 2003Tailwind begins
- 2026Managing Partner
Capital, with the date attached
By September 2008, Tailwind had closed a $775 million fund, above its $750 million target. The firm had already made seven investments with more than $250 million of equity commitments. One involved TowerCo’s $670 million acquisition of 3,100 communications towers from Sprint Nextel. Behind the fund total sat physical assets, operating businesses and transactions with rather more moving parts than a signature page.
The timing gives those figures their significance. In the 2008 fund announcement, Sorrel and fellow managing partner Douglas Karp acknowledged the difficult broader market while maintaining their focus on middle-market growth. A newly raised fund gave the firm capital to deploy. It also left its partners responsible for deciding how much of the changing market they understood.
At a 2009 private equity roundtable, Sorrel described a cautious approach to the downturn. He wanted portfolio companies to think carefully about the capital they held. Their chief executives could be optimistic; many had not managed through an environment like this. He also allowed that timing had played a part in the condition of Tailwind’s portfolio. Luck was permitted a seat at the table.
“We are being patient.”
Larry Sorrel, 2009
He expected difficult conditions to persist. That short declaration of patience belongs beside the later lease meeting: in one setting, waiting was useful; in another, beginning early was useful. The common question was what the available time allowed the firm to do. A calendar can provide room for judgment, if nobody mistakes it for an instruction to remain idle.
The next fund is another vote
In 2015, Tailwind closed its second fund with $1.05 billion in commitments against a $750 million target. Sorrel described the closing as a milestone for the firm’s investment strategy, track record and team. By then, Tailwind had invested more than $1 billion in 27 portfolio companies. The firm had also completed more than 65 additional acquisitions.
Those are two different kinds of growth. A portfolio company is an investment around which a business can develop. An additional acquisition can expand that business’s customers, geography or capabilities. The second category creates work long after the original purchase: combining operations, choosing managers and deciding which systems survive the marriage. The wedding photograph is the easy part.
The third fund closed in 2018 at approximately $1.8 billion. Its investors included institutions and individuals across North America, Europe and Asia. Tailwind had grown into a firm with an international pool of backers while continuing to pursue middle-market businesses. Pension funds, endowments and family offices could participate in the same fund, bringing different constituencies to a shared investment vehicle.
Sorrel’s response to that closing again emphasized the existing investors, the incoming investors and the team. The language of fundraising tends toward celebration. Its practical meaning is more demanding: a new commitment starts another period in which the manager must put money to work and account for what happens next. The larger number carries a longer list of people waiting for an answer.
Forty boardrooms, and a radio company
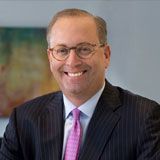
A separate archival portrait of Sorrel.
Alongside building Tailwind, Sorrel accumulated experience on company boards. By 2020, he had served on the boards of more than 40 mid-sized businesses. At Emmis Communications, his directorship dated to 1993, a decade before Tailwind’s founding. That overlap puts the career in perspective. His work with businesses extended across several stages of his own employment history.
Emmis identified him as an audit committee financial expert. It also valued his experience in buying, selling and financing communications businesses, and the longer strategic perspective he brought to deliberations. Those responsibilities are less photogenic than an acquisition announcement. They concern the quality of information, the structure of financing and decisions that can look different after several years.
A board position connects an investor to a business after the initial transaction. The agenda keeps returning. So do questions about capital and strategy. Sorrel’s lengthy Emmis service adds that recurring obligation to the founder’s biography: he was helping oversee an operating company while also helping develop the investment firm that became his principal professional home.
Giving the team a larger part
The people building Tailwind also became part of Sorrel’s public work. In May 2021, the firm promoted Dan Bise, Will Fleder and Caki Guinee to partner. Sorrel credited their work and leadership. The appointments covered investment activity as well as investor relations and marketing, a reminder that an investment firm needs more than a roomful of people seeking the next deal.
At the time of those promotions, Tailwind had 37 professionals, led by 11 partners and supported by 15 operating executives and senior advisers. Over the preceding year, the firm had deployed more than $500 million into four platform investments and 19 additional acquisitions. The headcount and the transactions belong together. Each new company adds relationships to manage; each acquisition creates decisions for the people running it. Fleder had joined in 2011, Guinee in 2014, and Bise had returned in 2019 after an earlier period at Tailwind. Their promotions also marked years of work inside the organization.
In February 2024, Sorrel and fellow managing partner Jeff Calhoun jointly discussed further promotions and investment-team additions. Their message emphasized developing and expanding the team. By December that year, Tailwind reported $4.3 billion invested across more than 295 acquisitions, including 51 platform companies. An organization operating at that scale needs a way to distribute responsibility.
That concern extends into the portfolio. Tailwind’s Emerging & Ascending Managers program, TEAM, develops executives at its companies. Its 2022 program description set out a year of professional development, with a second class of almost 20 executives following the first. Sorrel and Calhoun signed the accompanying managing partners’ message. Leadership development had become an organized activity with a cohort and a timetable.
Tailwind also runs an employee equity initiative, the Tailwind Ownership Program. The firm identifies National Trench Safety, Axis Air and Banner among companies where it has launched the program. Common equity for employees is realized at exit. It gives a wider group a financial stake in that future event, which otherwise can seem to belong chiefly to investors and senior management.
A founder still doing the work
Today, Tailwind lists Sorrel as Managing Partner and identifies active portfolio involvement including ASC, Material+, NTS and Riskonnect, formerly Ventiv. The firm’s current investment focus includes infrastructure services, supply chain and IT services. His professional story continues among businesses that require investment decisions, operating attention and people prepared to carry them out.
Tailwind describes its approach through three activities: developing talent, adopting technology and making acquisitions. The emphasis is on working with management teams to expand capabilities. That is a useful way to read the years after founding. The firm has to keep making organizational changes inside businesses, while making its own organization capable of supporting them.
Return to the lease. The discussion started in October 2014; the process finished in June 2016. Tailwind’s advisers had explored alternatives, and the firm secured improvements while the new lease economics would begin in summer 2017. There was no need for an imaginary last-minute dash to make the episode interesting. The useful work happened because the deadline was still some distance away.
Sorrel’s career contains larger transactions than an office renewal. Yet this small episode earns its place beside the funds, committees and board seats. It shows an investor participating in an ordinary business decision with time available to examine the choices. Sometimes the advantage is as modest, and as consequential, as having the meeting before the meeting becomes unavoidable.