An employee gets hurt. The obvious event is the injury. Then come the less obvious events: an empty shift, a supervisor rearranging work, a medical appointment, a question about a payment. A single incident becomes a coordination problem. Zenith Insurance Company has built its business around that expanding circle. The policy matters. So does everything the employer and injured worker must do next.
- The business: U.S. workers’ compensation, California agribusiness insurance, and claims services.
- The operating idea: prevent injuries, coordinate care, and help people return to suitable work.
- The buyer: employers working through independent agents and brokers; self-insured clients can buy claims services.
For a business owner, this makes Zenith an interesting purchasing proposition. It asks you to consider the machinery around an insurance claim alongside the premium. A policy transfers covered financial risk. Safety advice, coordinated communication, and recovery support address practical problems that can keep an employer occupied long after the incident itself.
01 / Start with the pattern
Zenith’s safety consulting begins with something pleasingly unglamorous: past injuries. Its consultants review a business and its loss history, identify consequential hazards, investigate causes, develop interventions, and track results. The subjects include lifting, repetitive motion, machinery, falls, vehicle use, and occupational exposures. A safety program becomes a sequence of decisions about particular work.
“Problems must be clearly defined before they can be solved.”Zenith / Safety & Health
That sentence carries the company’s most transferable idea. Before choosing training, establish which activity is hurting people and why. Zenith explicitly argues that inspections, program audits, and general training alone will not produce meaningful results. Its alternative is a process that checks whether an intervention reduced exposure, claims, or costs.
- 01ReviewFind the injury pattern
- 02InvestigateDefine the causes
- 03ChangeAct on the exposure
- 04MeasureTrack what improves
The limit follows from the process: somebody must implement the change. An employer who buys the policy but leaves the work untouched has skipped a crucial step. Any manager can copy the underlying habit: choose a recurring problem, investigate it closely, change the task, and review the evidence.
02 / The people around the claim
When prevention fails, Zenith brings together in-house claims specialists, nurses, medical bill reviewers, fraud investigators, and consulting physicians. Legal expertise includes attorneys and former judges. The point of that collection is coordination: medical decisions, payments, employer communication, and claim questions belong to the same episode, even when different specialists handle them.
Return-to-work support adds a practical detail. Zenith has developed transitional assignment lists for more than 50 industries. The work must fit the injured employee’s abilities. A company needs duties the employee can safely perform, together with communication among the worker, employer, and medical provider. The usefulness depends on the available assignments and the individual recovery.
industries covered by Zenith’s transitional work assignment resources
Zenith Connect handles smaller, persistent frustrations. Available in English and Spanish, the app lets injured employees view payment information, track medical appointments, find their doctors, and contact their examiner by phone or secure message. Mileage reimbursement requests are supported in California and Florida. These are modest functions, but they address questions a recovering person actually has.
The same expertise also has a separate commercial life. Zenith Claims Solutions serves the self-insured market with claims administration, recovery services, claims-legal support, nurse case management, and managed care. Clients can buy help running claims while retaining their own insurance risk. Services vary by state.
03 / An orchard is a very particular workplace
Zenith’s other distinctive business sits in California agriculture. A farm combines physical assets, vehicles, products, people, and liability exposures. Its insurance needs can stretch from a farmhouse to an agricultural processing facility. Zenith Agribusiness Solutions offers farm, commercial property, general and products liability, business auto, umbrella, and workers’ compensation coverage.
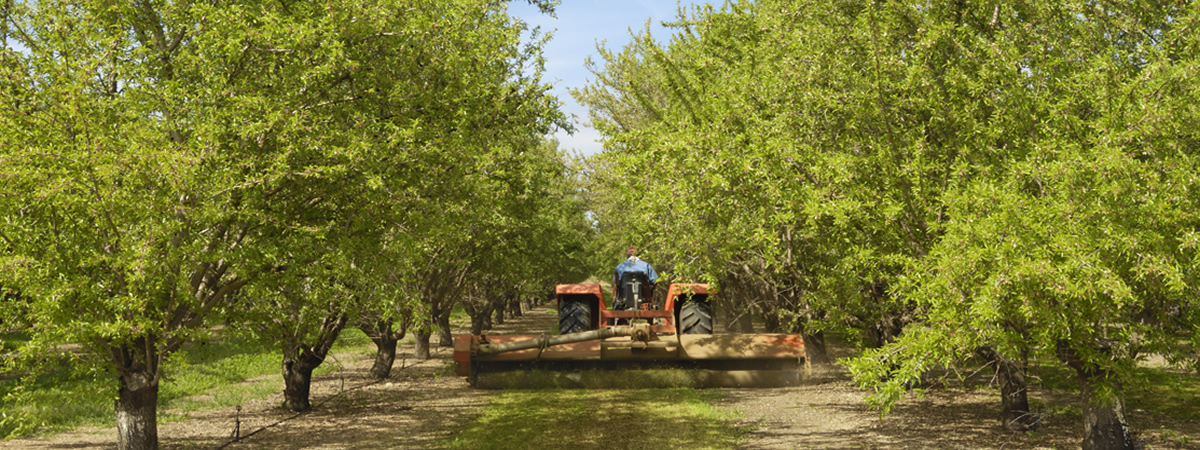
The company emphasizes insurance professionals based in California with agricultural experience. That matters because “farm” is an awkwardly broad word. Dairies, vineyards, berry operations, and cattle ranches do different work. Zenith’s proposition is familiarity with those differences, coupled with coverage choices and risk management. The contracts still determine what is covered.
Education extends that relationship. Zenith University offers current customers and agents live and recorded webinars at no additional cost, including sessions in English and Spanish. Its subjects reach into farm equipment transport, incident investigation, and heat illness prevention. Selected public webinars are complimentary. An employer can use the material to give supervisors a more concrete starting point.
04 / The price of paying attention
Zenith traces its founding to 1949. A Florida regulatory examination dates its workers’ compensation specialization to the arrival of management in 1978. Fairfax acquired the holding company in 2010 after announcing a $38-per-share deal that valued Zenith at approximately $1.4 billion. Davidson Pattiz became president and CEO in January 2025.
The economics are those of an insurer with an additional services business. Zenith National Insurance Corp. and subsidiaries reported $886.3 million in total revenue for 2025, including $765.7 million in net premiums earned and $10.5 million in service fees. Those are consolidated group figures. Investment results also contribute to revenue; premiums alone do not describe the whole business.
Selected revenue components, not a complete revenue breakdown.
The competitive field includes national workers’ compensation carriers such as Travelers, The Hartford, and AmTrust, alongside state funds. Zenith’s pitch emphasizes specialist service and the employer’s costs over time. A buyer still needs to compare the actual quote, coverage, service commitments, and fit with the business.
For the buyer, cost has two different meanings. There is the quoted premium, shaped by underwriting. Then there is the time spent managing disruption. Zenith’s service model is a reason to ask specific questions before purchase: who handles a difficult claim, what safety support will the operation receive, and how will progress be reviewed? An employer with little capacity to act on advice may get less from the relationship. A company prepared to involve supervisors, examine recurring injuries, and organize appropriate transitional duties has more opportunities to use what it is buying.
There is pressure behind the proposition. In October 2026, AM Best affirmed Zenith’s A financial strength rating with a stable outlook, while pointing to cumulative trauma claims, medical costs, and weaker recent profitability. Expertise cannot remove those forces. For an employer, the useful question is concrete: will this relationship help change the next injury’s likelihood, or the experience of recovering from it?