The buyer is overseas. The goods are ready. Then the money gets complicated. For a small exporter, winning an international order can be followed by another negotiation altogether: persuading a financial institution that the transaction is legitimate, explaining the paperwork and finding out how much will survive the journey into the company’s account.
XTransfer has made that unglamorous interval its business. Founded in Shanghai in 2017, the financial technology company helps importers and exporters receive payments, exchange currencies and pay suppliers. Its wager is that small traders deserve financial services designed around how they actually work, including the documents and banking questions that accompany a shipment.
The audience has grown. XTransfer reported more than one million registered customers in August 2026, up from a reported 700,000 in July 2025. Those are registrations, not a count of businesses making payments every month. Still, the scale gives a once-narrow proposition considerable weight: there is a business in helping other businesses get their money.
The first obstacle was the bank account
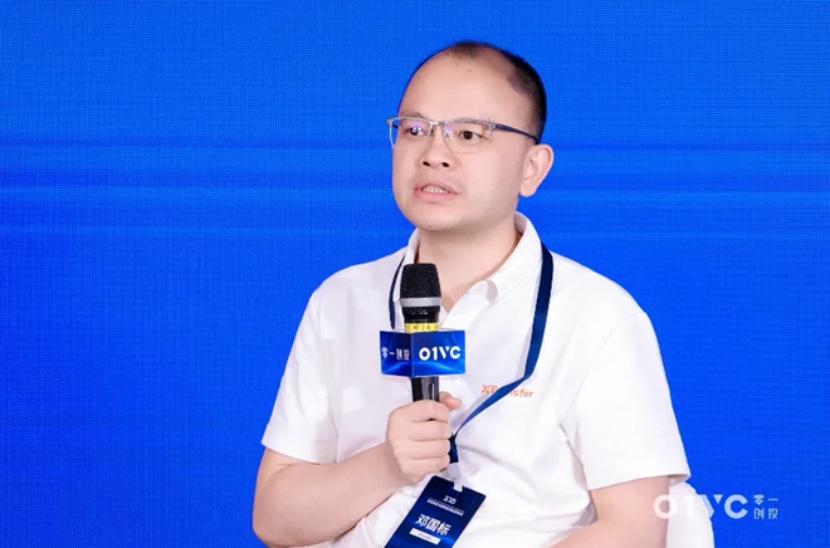
Bill Deng came to the problem with experience inside the payments industry. After nearly seven years at Ant Financial, he left to establish XTransfer with five colleagues, according to a profile in The Business Times. The team understood the machinery of international finance. They chose customers for whom access to that machinery could be awkward and expensive.
Small companies create a difficult equation for banks. Each customer needs checks, but a modest account may not generate enough revenue to justify laborious reviews. An exporter’s commercial legitimacy and a bank’s willingness to serve it are separate questions. A perfectly ordinary shipment can still require someone to examine unfamiliar counterparties and supporting records.
Deng described the resulting account freezes and exclusions in his Trade Finance Global interview. His proposed answer was an intermediary that could connect traders with banks while doing more of the risk work. The important failure in this origin story is a service gap: firms capable of selling internationally could struggle to obtain dependable financial access.
“We had to become a platform to connect SMEs and banks again.”
Bill Deng · Trade Finance Global · June 2025
That choice also explains XTransfer’s stated mission, “Making SME financial services simple and accessible.” The ambition sounds straightforward until a payment arrives with a complicated commercial history. Then simplicity becomes a substantial back-office job.
A wallet built for the shipment
The customer-facing product is a business wallet. A verified company can use collection accounts, hold supported currencies, convert money and send funds onward. Local collection details matter because a buyer can pay through familiar domestic arrangements where available, reducing dependence on a conventional international wire for every transaction.
Consider an illustrative exporter selling machine parts to an overseas distributor. The practical questions are whether the buyer can pay in an available currency, how the receipt is matched to the order, and how the exporter pays its own supplier. XTransfer puts those steps within one service. The attraction is less administrative juggling between receipt and reuse.
Its Chinese onboarding guide makes the trade connection explicit: customers create orders and associate incoming money with them. It also describes business and beneficial-owner verification. That is a useful corrective to the idea that opening a payments app makes the underlying commercial checks disappear.
- 01Verify the
business - 02Receive the
payment - 03Connect the
trade records - 04Convert or
pay onward
The global mobile app, launched in 2024, extends that workflow beyond the office desk. XTransfer says customers can manage and allocate funds from their phones. Its published global onboarding instructions require business verification and do not support personal verification. This is a tool for trading businesses, with approval at the front door.
Free has a route attached
The published price list advertises free account opening and maintenance, plus free transfers between XTransfer accounts. Sending to a business bank account starts at US$2 per transaction. Certain local-currency receipts carry charges starting at 0.5%. The destination, currency and method determine which promise applies.
For perspective, a 0.5% charge on a US$10,000-equivalent payment would be US$50. That is arithmetic, not a quote for a particular customer. It illustrates why a trader should look beyond the word “free” and compare the amount ultimately received, including conversion and any external charges.
Advertised transfer fee. Bank payouts and other routes have their own pricing.
XTransfer’s receiving-account FAQ points out that correspondent banks can deduct fees from international telegraphic transfers. Its own incoming-payment charge and the total cost of moving money are therefore different measures. The useful habit is to agree who bears deductions before sending, then reconcile the receipt against the original instruction.
The company’s 2026 listing draft reports US$248.46 million in 2025 revenue. Payment services supplied 83.8%; interest on client funds contributed 15.4%. That makes the economics clearer: free entry can support a business earning money from subsequent activity and balances. The application proof is a draft, subject to change.
The software has to understand the trade
XTransfer calls its AI-powered risk infrastructure TradePilot. In its account of Web Summit Qatar 2025, the company described using the technology to help banks detect fraud and perform anti-money-laundering checks. It also described an internal engineering team building AI capabilities into its systems and app.
The proposed advantage is specific. Trade brings information that does not arrive as a tidy payment instruction: who is buying, what is being sold and whether the supporting documents fit together. Better tools for interpreting that material could reduce the manual effort needed to serve a small account. That is the economic argument behind the technology, rather than an independent verdict on its accuracy.
The company’s published founding-team presentation helps explain the emphasis. It lists backgrounds spanning Visa, PayPal, Alibaba and Ant Group, with experience in risk management, engineering, finance and sales. This business requires more than a pleasant interface; someone must understand both the trade and the reasons a bank might question it.
Building those capabilities took capital. In September 2021, XTransfer raised US$138 million in a Series D led by D1 Capital Partners, reaching a valuation of roughly US$1 billion. Its announced uses included product upgrades, AI and big-data investment, anti-money-laundering systems and overseas recruitment. Funding bought room to build; it was not a disclosed itemised construction bill.
The bank handshake is part of the product
There is a reason XTransfer’s announcements feature so many banking agreements. A local account depends on local financial infrastructure. Visa Cross-Border Solutions, previously Currencycloud, described helping XTransfer collect funds in Canada, Europe and the United States. The partnership connected a customer need to payment capabilities already operating in those markets.
Hong Kong supplies another piece. In an Invest Hong Kong profile, Deng explained the city’s usefulness as a regional hub connecting Chinese suppliers with international buyers and banking partners. Its role is practical: a concentration of financial institutions can help a payment company organise services across multiple destinations.
The same logic appears in Africa. A February 2025 agreement with Ecobank aimed to let Chinese customers collect local African currencies and help African businesses pay in local money. That tackles a real commercial complication: a willing buyer may have domestic currency but face friction obtaining foreign exchange.
In November 2025, OCBC agreed to support XTransfer with corporate banking services across Greater China and ASEAN. Maybank separately signed an agreement covering payments and FX, with plans to explore Shariah-compliant offerings. These announcements describe different building blocks and development intentions. They do not establish that every proposed service is already available everywhere.
Follow the buyer to the next market
XTransfer’s expansion follows an observable change in its customers’ trade. In July 2025, the company said more than 70% of its clients had exported to Asia, Africa or Latin America during the first half of that year. Those destinations were increasingly central to its account of where growth would come from.
That creates an understandable incentive to recruit both sides of a transaction. Serving the exporter brings the overseas buyer into view; serving both can make an internal payment possible. The app’s advertised round-the-clock transfers between XTransfer accounts make that proposition concrete. The benefits of an internal network depend on both counterparties being able and willing to join.
Expansion also requires permission. On September 3, 2026, XTransfer announced in-principle approval in the UAE for a retail payment services licence. The company said pre-issuance conditions still had to be completed before the licence would allow service to mainland UAE clients. A new market takes more than another language option in an app.
The useful comparison is your next invoice
XTransfer competes with banks and overlaps with Wise Business, Airwallex and Payoneer. Wise offers international business payments; Airwallex combines payments with broader business finance tools; Payoneer serves international businesses and marketplace sellers. XTransfer’s distinctive emphasis is the import-export relationship and the compliance work surrounding it. That emphasis is positioning, not proof of universal price superiority.
For a prospective customer, the sensible comparison starts with an actual transaction: the business’s jurisdiction, buyer’s currency, supplier’s destination and documents required. A low advertised transfer fee is useful only if the route works. A company relying on an unsupported market or transaction type cannot solve that mismatch by downloading the wallet.
The business lesson is equally concrete. Find the expensive administrative task preventing a customer from using an existing service, then organise a product around reducing it. XTransfer’s case suggests that banks can become distribution partners when a fintech helps make small accounts workable. Copying the interface without the verification capacity or banking relationships would leave the difficult part untouched.
A payment platform cannot manufacture foreign currency, remove trade restrictions or guarantee that every transaction clears a review. What it can do is shorten the distance between a legitimate order and usable money. For the exporter preparing the next shipment, that is a proposition worth inspecting closely.
Open the wallet. Hear the founder.
XTransfer website · Pricing · Company news · Trade blog
Watch: Bill Deng at Money20/20 Europe · Watch: Singapore FinTech Festival session · Official YouTube channel