The payment is the part everyone notices. The hours spent arranging it are easier to miss. A sports promoter must get prize money to competitors abroad. A property platform needs investor capital available before a project can start. A payments business has customers of its own asking where their money went. IFX Payments has built its current pitch around this back-office commotion: give the finance team somewhere to manage the whole job, and someone to call when it gets complicated.
That is a more demanding proposition than selling a good exchange rate. The London company combines foreign exchange with accounts, bulk payouts and software connections through its proprietary platform, ibanq. Its chosen customers include corporates and financial intermediaries whose structures, markets or payment needs require specialist attention. The challenge is commercial as much as technical: being helpful must translate into work the customer can measure.
01 / THE PIVOTA currency broker discovers the paperwork
IFX began in 2005, when Nick Williams and Tom Greenwood founded the business at Shardeloes Farm in Amersham. The setting is a pleasing distance from the usual fintech origin story. Its early business was telephone brokerage, arranging foreign exchange for clients. In a 2025 industry essay, CEO Will Marwick described the pressure that eventually pushed the company to reconsider: FX was becoming commoditised, with margins increasingly deciding who won an account.
The company chose to concentrate its next move on corporate customers. Marwick’s explanation was practical. Retail payments already demanded polished consumer experiences at very thin margins. Businesses, meanwhile, had problems beyond the price of currency: collections, settlement, account management and the effort of joining those tasks together. IFX could sell assistance with a larger piece of their working day.
Its April 2021 leadership announcement recorded the addition of ibanq in January 2020. By that announcement, IFX said its client base had doubled over twelve months and it was handling 150,000 payments a month. Those are historical figures, but they help explain the management change: Marwick moved from COO to CEO, while Williams became executive chairman. Payment infrastructure had become central to the business.
02 / THE PRODUCTOne place for money with several destinations
ibanq brings several related jobs into one environment. Multi-currency accounts let businesses receive and hold different currencies. Virtual IBANs provide payment identifiers in the business’s name. Sub-accounts organize money by client, entity or purpose. Together, these features are meant to make funds easier to identify and reconcile when the same business operates across markets.
The current product pages advertise more than 40 currencies for holding and receiving funds, and more than 60 for outgoing payments. Keeping the two numbers separate matters. A destination supported for a payout does not automatically mean the same currency can be collected or held through an identical route. The operational question is whether the specific journey a customer needs is supported.
Conceptual workflow, not a screenshot. Available routes and services depend on the account setup.
Mass payments compress a list of transfers into a batch. That suits recurring runs to suppliers, employees or partners. The API takes the same idea into a customer’s own software: beneficiary management, payment instructions, currency exchange, account reporting and status updates can be connected to existing systems. A business can use IFX directly; another fintech can put IFX’s infrastructure behind its own offering.
The FX business remains part of the package. Spot transactions cover present currency needs; forward contracts fix a rate for an agreed future exchange. A company paying a known overseas bill can use that certainty in its budgeting. It still has a contract to fulfil. Fixing a rate removes the chance to benefit from a later favourable move on the contracted amount, and applicable margin terms need attention.
03 / THE CUSTOMERSThe prize money has to arrive
Matchroom Sport makes an unusually vivid customer example. Its events send prize money to athletes in up to 60 countries. In an August 2026 IFX case study, founder Barry Hearn described how rising scale made the expense of its previous banking arrangements harder to accept. Matchroom looked at several alternatives and began working with IFX in 2015.
“Currency can be a pain if it takes our time.”Barry Hearn / Matchroom Sport
The case study describes batch payments, currency balances and a relationship manager familiar with the operation. For a sports business, the useful outcome is fairly concrete: less payment administration trailing each event. Hearn also makes clear that a long relationship does not exempt a supplier from comparison. Matchroom continues to assess the market. Eleven years earns another evaluation, rather than a lifetime pass.
Sciopay illustrates the infrastructure side. It supplies branded FX and payment services to other businesses. IFX’s August 2025 case study says Sciopay had processed more than £3 billion in cross-border payments since the partnership began. Its reported problems included growing transaction volumes, settlement delays and the difficulty of integration. IFX supplied API infrastructure and worked with its team on customer requirements. The £3 billion is cumulative payment value, not IFX revenue.
LendCart, a real estate lending platform, offers a different measurement. Its published case study reports a 40-50% reduction in transaction processing time and FX savings of up to 1.5% against traditional banking partners. It used consolidated multi-currency accounts, tracking and tailored integration to address delays moving investor money and making disbursements. These are customer-specific reported results, rather than a tariff or a promise to every applicant.
less transaction processing time
Reported by the customer in IFX’s case study. Results vary by payment setup.04 / THE ECONOMICSThe exchange rate is only one line of the bill
IFX’s commercial business is foreign exchange and payment services. Customers receive bespoke quotes, and applicable charges and dealing terms belong in that agreement. The economic proposition is that repeat transaction activity and ongoing infrastructure relationships support the cost of software, payment access and human service. This is a business built around moving money, with software making those relationships more useful.
There was visible growth before the latest platform rebuild. IFX reported revenue of £41 million for 2023/24, compared with £33 million a year earlier. In November 2024 it said its workforce had exceeded 200 people. These dated disclosures establish a meaningful operating business without turning an old figure into a claim about today’s performance.
A buyer can compare IFX with OFX’s business FX and payment services, Wise Business’s international accounts and transfers, or Airwallex’s accounts and broader payment tools. Banks remain an alternative too. The categories overlap. IFX’s emphasis on specialist onboarding and relationship management is a positioning choice, not proof that another provider cannot handle the same customer.
The useful comparison includes the amount received after charges, the supported route, payment timing and the staff effort needed to resolve exceptions. A firm with occasional, straightforward transfers has less administrative work to recover through a tailored arrangement. A business with repeated, complicated flows has more reason to test it. The sensible unit of comparison is the completed payment run.
05 / THE DEALA £3 million offer meets a larger liquidity problem
IFX’s attempt to acquire Argentex in 2025 shows why payment companies must be judged on more than their interfaces. In April, the companies agreed an offer valuing Argentex’s equity at approximately £3 million. The proposed combination would have expanded IFX’s FX risk-management capabilities, institutional reach and geographical presence.
Financing commitments were larger than the headline purchase price. An initial £6.5 million secured bridge loan grew to £10.5 million. In May, Argentex announced a separate revolving credit facility of up to £20 million from IFX, intended to help meet margin calls arising from adverse currency movements. The figures describe different instruments; they cannot be treated as one completed acquisition payment.
The weakness was liquidity. Reuters reported that Argentex was hit by currency-market swings following US tariffs, then suffered further deterioration before pausing commercial and trading activity in July. Its operating partnership entered special administration; the parent subsequently entered administration. On August 7, the offer lapsed after IFX received Takeover Panel consent to invoke an insolvency condition.
That sequence explains the reversal without inventing a boardroom change of heart. An expansion plan encountered the target’s insolvency. For readers assessing the business, it is also a reminder to distinguish an announced transaction from a completed one, and credit committed from money ultimately lost. The proposed purchase did not make Argentex Group an IFX subsidiary.
06 / THE NEXT VERSIONSoftware, safeguards and someone accountable
IFX continued to develop its operating business. In June 2025 it selected Form3’s Verification of Payee service, adding to earlier use of Confirmation of Payee and SEPA Credit Transfer. The service checks a payee’s name against account records before a payment is sent. It addresses a specific source of mistakes and fraud, rather than making international transfers risk-free.
In June 2026, IFX announced ibanq 2.0 alongside a reshaped leadership team and a new London base at The Carter. The platform update involved rebuilt infrastructure for corporate payments and fintech customers. Anastasia Evans became COO, Adam Dowling moved to chief commercial officer, and Murat Ates took responsibility for product and technology. The company also announced specialist risk and compliance appointments.
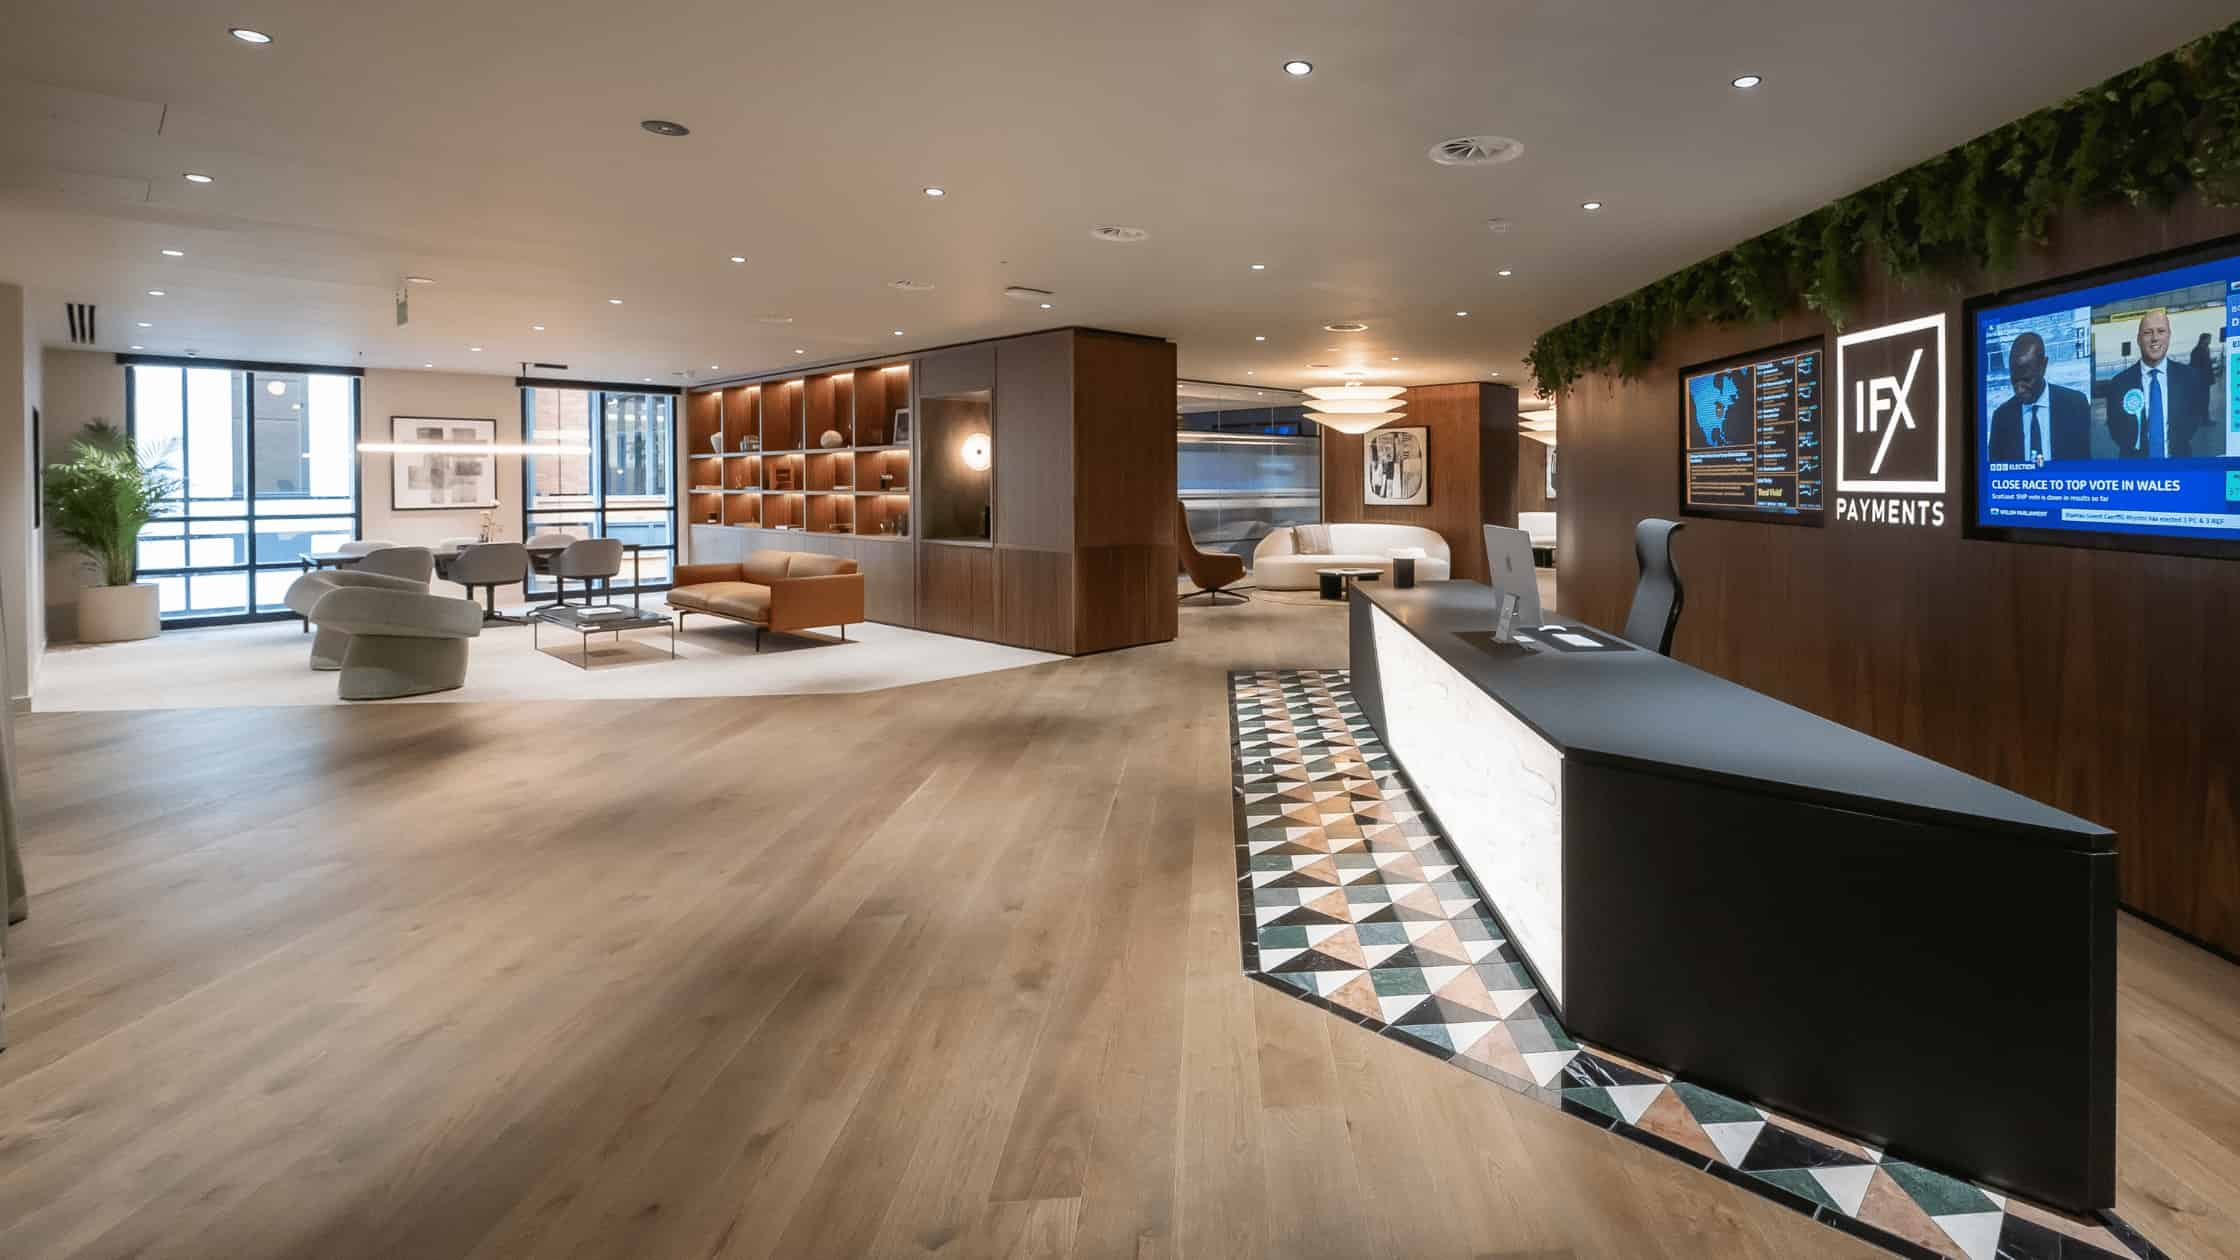
The hiring and office announcements suggest how IFX wants to work: software development alongside operational and regulatory expertise. Its recruiting material emphasizes collaboration, flexibility and development. Those are employer statements, but the structure of the business explains the need for cooperation. A payment issue may require an engineer, a relationship manager and a compliance specialist to understand the same customer.
There is a boundary to the banking language. IFX’s UK operating business is an authorised electronic money institution. Its safeguarding explanation says client funds are protected through arrangements separate from operational money, and that IFX is outside the Financial Services Compensation Scheme. A financial intermediary using it must also attend to its own safeguarding duties.
The practical lesson for a finance team is to map one real payment run before shopping for a replacement. Count conversions, handoffs, reconciliation work and unresolved exceptions. Then test the proposed setup against that record. IFX’s pitch becomes persuasive when those tasks get easier. The exchange rate still matters. So does getting the afternoon back.
Follow the money
Explore IFX Payments, its payment API and news and customer stories. Read the Matchroom conversation, the LendCart case study or the Reuters report on Argentex.