Ten minutes is a pleasing amount of time to wait for a loan decision. Long enough to make tea; short enough to forget where you left it. When Vimal Saboo joined EarlySalary in July 2016, the company was already advertising underwriting on that timescale. His assignment was to help build the machinery behind the promise: credit risk profiling, underwriting and operations. The customer would see a quick answer. Saboo’s work concerned the reasons for giving it.
By July 2025, the same executive had become chief executive of EarlySalary Services Private Limited, or ESPL, Fibe’s licensed non-banking financial company. Nine years separated the two appointments. Between them sits a professional story about the changing speed of finance, and the responsibilities that stubbornly refuse to hurry.
A loan application has a beginning and an end on a screen. A lending relationship has a longer calendar. Read Saboo’s career with that distinction in mind, and the promotion becomes more interesting than a new line beneath his name.
The résumé behind the risk model
Saboo is a chartered accountant, with the Institute of Chartered Accountants of India listed in his education. Before EarlySalary, his employers included L&T-John Deere, ICICI Bank, Axis Bank and Edelweiss. It is a route through established businesses into a younger lending company, with credit and analytics running through the middle.
At ICICI Bank, he held the title of chief manager and worked across credit card operations. At Axis Bank, his work encompassed credit decisions, sourcing policy, the authorisation centre and analytics for cards. He later held a senior vice-president role at Edelweiss. These are responsibilities with a particular vocabulary: policy, approval, authorisation, exposure. None is likely to be chosen as the name of a glamorous product launch.
Yet they describe the work on which such launches depend. A card can look elegantly simple in a wallet. The decisions supporting it are anything but decorative. That earlier experience gives Saboo’s move into mobile lending its context: he arrived with familiarity with the operations behind consumer credit.
- Before 2016L&T-John Deere, ICICI Bank, Axis Bank and Edelweiss
- July 2016Chief Business Officer, EarlySalary
- July 2025CEO, EarlySalary Services Private Limited
Ten minutes, followed by months
His 2016 arrival paired an experienced credit professional with a company trying to make lending feel immediate. Saboo spoke publicly about artificial intelligence and neural networks at the time. The terminology now feels familiar enough to appear on almost any conference programme. His interest in applying it to lending predates the current flood of conversation around AI.
That date is worth holding on to. It places his technology remarks within the original assignment, rather than treating them as a recent addition to a leadership biography. The task was concrete: developing the credit risk profiling system and overseeing credit risk, underwriting and operations.
The tension in that brief is easy to understand. Customers value a simple application and a prompt response. A lending business needs the response to hold up after the application has closed. Speed is visible immediately; the quality of a loan decision takes time to reveal itself.
Saboo has continued to discuss the two together. In a CRIF industry report, he described analytics and automation in terms of “customer delight and credit discipline”. He also discussed models for real-time decisions and tools that flag unusual, potentially risky applications. The pairing is revealing. A convenient journey and a careful decision belong in the same sentence.
“customer delight and credit discipline”
Vimal Saboo, on analytics and automation
There is an unglamorous elegance to that ambition. Ideally, the borrower experiences fewer obstacles because more useful work has happened behind the screen. A system that moves quickly still has to distinguish between applications. The spinner may stop in minutes. The lender’s responsibility continues.
The company a borrower never sees
The full name of Saboo’s new employer is longer than most people would choose to type into an app store. EarlySalary Services Private Limited is the licensed NBFC arm associated with Fibe. His July 2025 elevation put him in charge of that entity. Fibe’s co-founder Akshay Mehrotra remained identified as Group CEO in the appointment announcement.
The distinction helps explain the job. A brand can bring together products, technology and customer relationships. The lending entity has its own leadership and operational responsibilities. Saboo’s title belongs to that business within the group, a precise appointment with a substantial remit.
The announcement set out lending expansion, digital infrastructure and tailored credit for underserved customers among his priorities. It also included strategic partnerships and the integration of environmental, social and governance principles. The organisational change was presented as a way to give business verticals more focused leadership.
After years working across the organisation, he was being asked to lead a defined part of it. That continuity matters. An executive promoted from within brings a history of decisions and working relationships into the new role. Here, the preceding nine years covered the business officer’s remit before the CEO appointment arrived.
From building credit risk and underwriting operations to leading the NBFC arm.
Saboo framed his own ambition with the phrase “driving scale with responsibility”. As an aspiration, it sets a useful standard. Scale can be counted. Responsibility has to be demonstrated in the way the business operates. The phrase does not settle the question; it identifies the question his leadership will have to answer.
A quiz, a laptop, a useful warning
For a less formal view of his public work, consider Fibe’s Scam Defender campaign. In a video shared in December 2024, Saboo sits at a desk in a red polo shirt, glasses on, a laptop beside him. The setting is ordinary. The subject is digital fraud, and the format is a quiz.
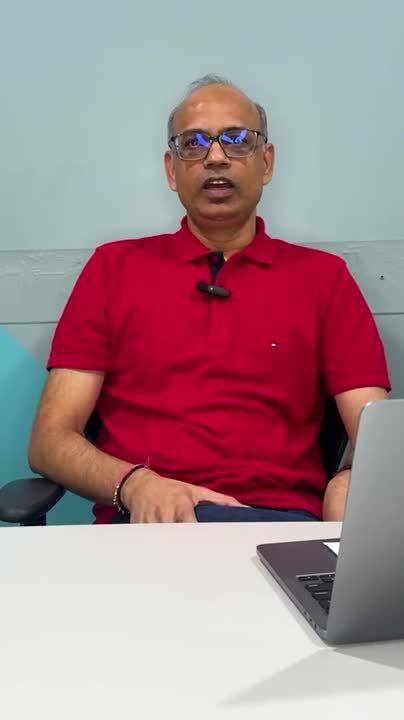
He took part and nominated Ashish Goyal, Fibe’s co-founder and CFO, to try it next. Earlier, technology executive Anil Sinha had nominated Saboo. The campaign moved through colleagues by invitation, giving the warning a small social life of its own.
It is a modest episode, and its modesty is useful. A formal appointment explains authority. A quiz explains a specific action. Here was a lending executive joining a campaign that asked people to recognise scams, with no need for a stage or a lengthy speech.
The episode belongs in this career story because fraud prevention is one of the subjects Saboo has discussed in relation to analytics. The video approaches the issue from the customer’s side: pay attention. His discussion of anomaly detection approaches it from the lender’s side: examine the application. Both concern the trust needed to transact at a distance.
Partnerships have a balance sheet
Saboo’s public appearances also show an interest in the connections between financial institutions. At an NIBM panel on fintech and financial inclusion, described in its 2022–23 annual report, he discussed Aadhaar and the way banks partner with fintech companies to expand access.
That is a different emphasis from the solitary app on a customer’s phone. The phone presents one interface. Behind it, organisations work together. Saboo’s contribution placed lending technology inside those relationships, alongside the infrastructure that makes identification possible.
A testimonial on Credit Saison India’s website offers another concrete example. Speaking as EarlySalary’s Chief Business Officer, he described the partnership as supporting seamless customer experience, wider access and the building of a larger balance sheet. The language joins customer convenience to institutional capacity.
In February 2023, he was also listed on a Bharat Fintech Summit panel about AI and machine learning in portfolio analytics. The programme connected the discussion to sustainable credit. His career experience and the subject of the session fit together: the question extends beyond an individual approval to the performance of a collection of loans.
Then, at Global Fintech Fest 2025, he joined a CRIF Talks conversation led by Parul Rathore. The published description focused on product innovation and the combination of behavioural and credit insights. Across these appearances, a recurring professional interest becomes visible: making better use of information while developing the relationships that support lending.
A longer horizon for the same decision
Consumer lending has changed around Saboo. In a 2021 discussion of buy now, pay later, he distinguished small payment-credit offerings from larger transaction financing repaid in instalments. He described EarlySalary’s NBFC-backed offering and its customer identification requirements. Even the cheerful invitation to pay later came with operational distinctions.
The broader business continued to develop after his CEO appointment. Fibe raised $35 million in equity financing from the International Finance Corporation in December 2025. Saboo shared the news publicly, emphasising the business’s risk and governance culture and thanking the team, customers and lenders.
That post is a useful closing detail. The sum belongs to the company. His choice of emphasis belongs to his public account of the event. He placed risk and governance beside the announcement of new capital, a continuation of the concerns visible in his earlier roles.
There is no neat finish to a lending career. A new product creates new applications; a new partnership creates new operating questions. Saboo’s move to ESPL’s CEO role widens the responsibility around work he has spent years doing. The title changes. The need to understand the decision remains.
Back at the beginning, ten minutes sounded like the story. It was the time a customer might wait. Saboo’s route from banking to EarlySalary, and from business officer to NBFC chief executive, supplies the longer view. Every quick answer begins a relationship that somebody must continue to manage. His next chapter takes place on that longer calendar.
Follow the conversation
- Fibe’s website · Vimal Saboo on LinkedIn
- Watch: CRIF Talks with Vimal Saboo at Global Fintech Fest 2025
- His appointment to lead EarlySalary Services
- The July 2016 EarlySalary appointment
- The Scam Defender campaign video
- CRIF’s digital lending report · Saboo’s IFC investment post
- Fibe: LinkedIn · X · Instagram · Facebook