Rent has excellent punctuality. It arrives on the first, indifferent to whether a paycheck is early, late or still making its way through payroll. Jeff Berkson’s next banking assignment concerns the space between those dates. After nearly a decade as WebBank’s executive vice president and chief risk officer, he joined Flex in May 2026. The company has named him proposed president and chief executive of Flex Bank, an industrial bank it is seeking to organize in Utah.
The title comes with a small but consequential qualification: “in organization.” Berkson is already Flex’s chief banking officer. The bank itself is proposed. Its launch depends on regulatory approval. Those words are easy to hurry past, particularly in a business fond of announcing the future in the present tense. Here, they establish where the story stands: an experienced risk executive has moved into an assignment that would put him in charge of a new institution.
A title with a condition attached
Flex announced its applications to the Federal Deposit Insurance Corporation and Utah Department of Financial Institutions on July 24, 2026. It proposed a bank based in the Salt Lake City area, operating nationally through digital channels. For Berkson, who is based in Salt Lake City, the plan joins a familiar banking location to a business built around household payments. The headquarters would be local; the customer base would extend across the United States.
The calendar problem gives the proposal its shape. Under the planned rent-credit model, a customer would contribute part of the rent near the beginning of the month. The bank would advance the full payment to the landlord, and the customer would repay the remaining balance before month-end. The purpose is to align the payment schedule with incoming money. Splitting the date does not reduce the rent. The distinction matters when a financial product enters a household budget.
Two competing calendars.
A proposed bank built to bridge the timing gap between income and essential expenses.
That is a deceptively compact brief for a chief executive. The visible experience might involve choosing a payment date on a phone. Behind it sit lending decisions, records, funding, security and the rules governing a bank. Berkson’s appointment is interesting because his earlier jobs have repeatedly dealt with those less visible parts. His career offers a way into the proposal through the organization required to make a payment feel routine.
Before the rent bill, the database
Berkson graduated summa cum laude from Duke University with a B.A. His subsequent work moved through information systems and financial analysis. At Anchor Bank in Madison, Wisconsin, he served as chief information officer in an outsourced capacity from October 2009 to August 2013. The arrangement is a useful detail: the role concerned responsibility for the bank’s technology even though his position was provided from outside the institution.
He also held the chief information officer role at Clout Financial Services, a startup credit-card issuer. His work at Clout and Anchor included building risk-management and business-intelligence platforms. Before WebBank, he was chief analytics officer at Credit Risk Management Analytics, a consultancy serving community banks. These are jobs in which the quality of a decision depends, in part, on how well the information has been collected and arranged before anybody reaches for a conclusion.
There was entrepreneurial work as well. Berkson led a financial-services analytics consultancy and an online property-tax appeal service. The latter adds an unexpectedly domestic item to a banking résumé. Property taxes are another place where a large financial obligation meets records, valuations and a process that can be difficult for an individual to navigate. His later assignment concerns renters rather than tax appeals, but both belong to the practical business of paying for a place to live.
Read together, these roles show a progression through the systems that make financial information usable. They do not make a new bank’s outcome inevitable. They do explain why a proposed bank might select a leader whose experience crosses technology, analysis and oversight. A chief executive has to understand the reports arriving at the desk. Berkson has also worked on the machinery that produces them.
Growth deserves a second look
In November 2016, Berkson published an article about commercial real estate concentration risk. Its subject was bank lending, rather than household rent payments. He argued that growth rates deserved attention because a loan portfolio could expand faster than the risk infrastructure supporting it. He urged bankers to examine concentrations, follow early warning indicators and test potential losses under difficult conditions.
“Banking is a relationship business”
Jeff Berkson · November 2016
He also connected analysis to conversations with borrowers. The argument put data in service of decisions, rather than leaving it in a report. That is a useful clue to his professional approach: figures become valuable when somebody can use them to act. The article addressed a particular lending environment. Its emphasis on the relationship between expansion and oversight offers a relevant lens for reading his move to a company organizing a bank.
WebBank gave that work a broader institutional setting. From October 2016 until May 2026, Berkson led its risk function. His remit included enterprise risk management, compliance, credit, model risk, information technology and security, risk analytics and audit. The list spans both financial judgments and the systems supporting them. It also explains why the move to a proposed CEO role represents a widening of responsibility after years spent supervising several of a bank’s control functions.
The people behind the controls
Colleagues’ public recommendations supply a closer view of the work. Martha Hayes described Berkson’s contribution to Anchor’s ability to manage and analyze information. She credited him with improving the business-intelligence group’s retention and performance, and with leadership on initiatives involving loss forecasting and enterprise risk. Her account ties technical work to the way a team performs, a useful counterweight to the assumption that an analytics career consists entirely of solitary encounters with spreadsheets.
Jill Hanson emphasized another practical skill: making large datasets concise enough to support project reporting. She described a reporting structure that could be refreshed easily, allowing her to produce regular progress updates. She also singled out his response time. Neither recommendation supplies a private personality portrait. Together, they describe professional habits that colleagues noticed: clear information, usable reporting and timely assistance. In an organization, those habits can determine whether an analysis reaches the people who need it.
His Salt Lake City connections also include housing work outside a bank’s own operations. NeighborWorks Salt Lake’s 2022 annual report lists Berkson, representing WebBank, on its finance committee. The organization’s work includes housing and community development. The committee listing places him in that local network; it does not assign every project or result to him. The connection is nevertheless relevant to a career whose next public chapter concerns the mechanics of paying rent.
Another form of recognition arrived on the 2026 Women in Governance, Risk & Compliance Awards shortlist. Berkson, listed with WebBank, was nominated in the Male Advocate category. Shortlisting is its own achievement and deserves its own precise wording. It adds a people-focused detail to a record otherwise heavy with controls, credit and technology. Banking organizations depend on the people who interpret and operate those systems, and this recognition concerns the professional community around that work.
A different stage, familiar questions
A photograph from Ripple Swell 2025 shows Berkson with fellow participants in New York. The event placed him alongside Christian Rau, Pat Thelen and Dan Chen. Rau described their discussion as addressing efficiency in digital payments while keeping consumer protection and compliance central. It was another setting in which the customer’s visible experience and the infrastructure underneath it occupied the same conversation.
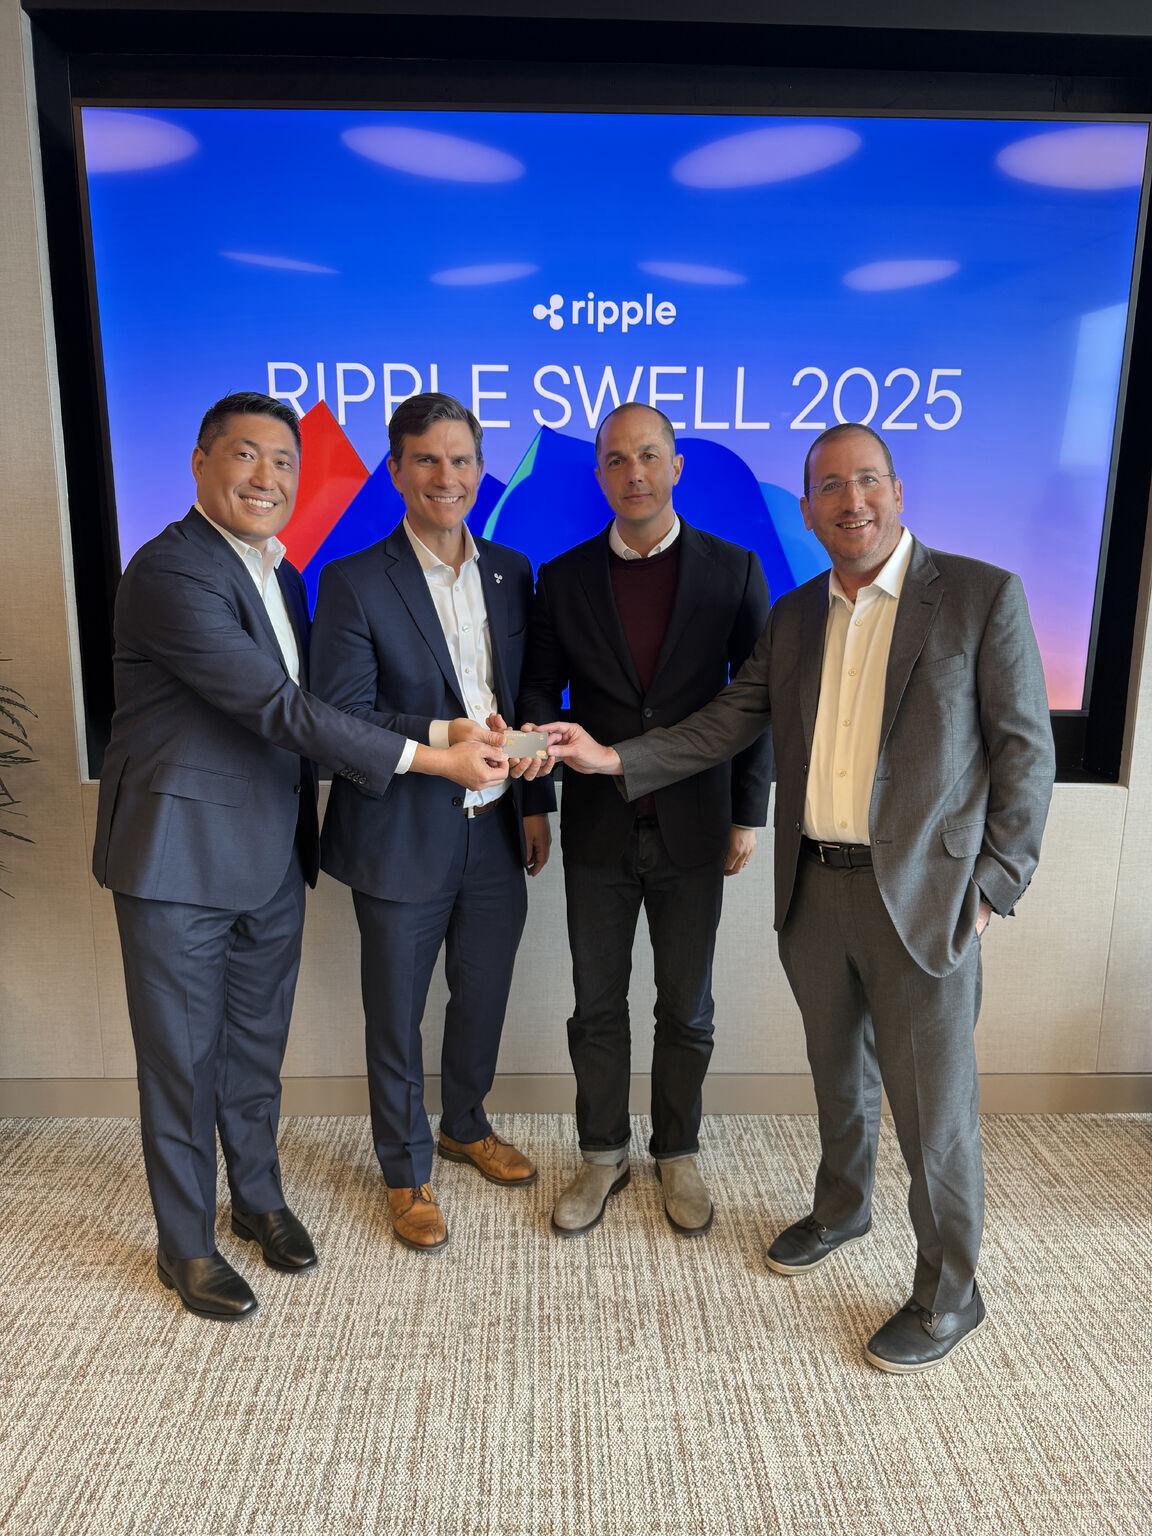
The group photograph has the familiar grammar of a business conference: jackets, smiles, a branded screen and a card held toward the camera. The discussion behind it concerns a less photogenic set of questions. How does a payment move? What protects the customer? Where does responsibility sit? Those questions travel comfortably from a payments panel to the proposed bank assignment, even when the products and counterparties change.
The bank still to be built
The Flex proposal gives Berkson colleagues with defined responsibilities. Its planned executive team includes Kristine Dickson as chief financial officer, Milos Sugovic as chief credit officer, Chelsea Keegan as chief compliance officer and Danny Gordon as general counsel. The proposed board includes Berkson, Flex chief operating officer Christina Edling, Kelly Barnett, Crawford Cragun and Roberta McInerney. This is an organizational plan, with named people attached to the work a new institution would require.
The proposed bank would issue Flex’s credit products directly and offer deposit accounts. Its plan describes digital delivery without physical branches. That makes the systems beneath the customer interface particularly consequential: the application, the records and the controls would carry work that customers might otherwise associate with a branch. Berkson’s technology experience belongs in this part of the story as much as his risk title does.
- Build the informationBank technology & business intelligence
- Interpret the creditCommunity-bank analytics
- Oversee the riskWebBank · 2016-2026
- Organize the institutionFlex Bank · proposed leadership
For now, the meaningful endpoint is the proposed institution and the executive selected to lead it. The public plan supplies an ambition for the company: bring banking functions closer to its essential-payment products. Berkson’s individual task would be to run the bank within that plan. The career behind him supplies experience in building information systems, interpreting credit and overseeing risk. The job ahead would bring those responsibilities together under the chief executive’s title.
There is a pleasingly ordinary measure of what the proposal hopes to accomplish. A landlord receives rent on time. A renter repays on a schedule that fits incoming money. The institution behind those transactions has to do considerably more work than the calendar suggests. Berkson has moved toward responsibility for that institution. Rent will continue to arrive with its usual confidence. The proposed bank is being organized to meet it.