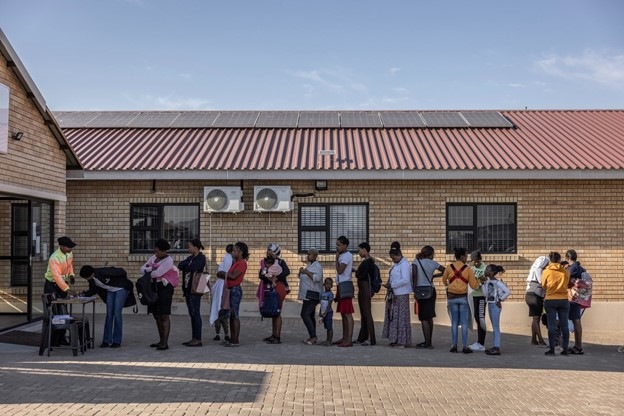
A line of patients waits outside a brick clinic in Diepsloot, South Africa. In the photograph, the building is modest, the queue ordinary. Yet this is a useful place to begin understanding Viatris, a pharmaceutical company whose products are far more familiar than its name. A medicine can exist, work and be approved, and still fail to reach the person who needs it.
Viatris helped fund this clinic with the nonprofit Rhiza Babuyile. The broader company operates at a very different scale: medicines sold across more than 165 countries and territories. Moving between those two views, the clinic doorway and the international supply network, reveals the business. Discovery is only one part of medicine. Someone must make the treatment, register it, distribute it and keep supplying it.
- Brands and generics share a global network.
- Manufacturing quality determines delivery.
- A proposed $1.65 billion deal adds pain medicines.
A young name with an old medicine cabinet
Viatris arrived in November 2020 through the combination of Mylan and Pfizer’s Upjohn business. It was born with an inheritance: manufacturing knowledge, generic medicines and established brands. Think Lipitor, Norvasc, Lyrica and Viagra. Availability and commercial rights vary by country, but the names explain why a patient might know the medicine without recognizing the company behind it.
This was no garage startup. The transaction included a $12 billion cash payment to Pfizer, financed with debt raised by Upjohn before the combination. Viatris began life publicly traded on Nasdaq as VTRS, with the obligations of an industrial enterprise already attached. Its origin story belongs in a corporate filing rather than a founder’s notebook.
The company’s stated mission is to “empower people worldwide to live healthier at every stage of life.” The interesting question is how. Its answer combines the economics of familiar products with the technical work of making harder ones.
The clever part is often the delivery
A basic generic competes in a crowded market. A complex generic may require expertise in an inhaler, injection, formulation or delivery mechanism. Viatris’s Wixela Inhub, the first generic of Advair Diskus, illustrates the distinction. Reproducing the therapeutic option involves more than manufacturing a tablet with the right ingredient. The device matters too.
That helps explain its position beside competitors such as Teva and Sandoz. Viatris combines generics with an established branded portfolio and an expanding innovative medicines business. It is selling treatments, rather than a software subscription or a clinic membership. Wholesalers, distributors, pharmacies, hospitals and public purchasing systems connect those products to patients.
For a health system, generics can offer treatment options at lower cost. For a development partner, Viatris offers regulatory, manufacturing and commercial capabilities across markets. For an individual, the useful next step is its country-specific product directory: a global brand list does not establish local availability, reimbursement or suitability.
Even the scale deserves careful reading. Viatris estimates that it reaches about one billion patients annually. That is a calculation from medicine volumes and estimated use, not a count of registered customers. The distinction matters when comparing a pharmaceutical supplier with a hospital network or a consumer app.
register
verify
replenish
The worksheet that became a business problem
In June 2024, FDA inspectors visited the company’s Indore facility in India. Their subsequent warning letter described quality-control records for tests attributed to analysts who, according to biometric access records, were not physically present. The failure began inside the evidence supporting manufacturing quality. By December, it had become an import restriction.
Viatris said the alert affected 11 actively distributed products, with conditional exceptions for four because of shortage concerns. It brought in outside specialists and implemented a remediation plan. The company later estimated the negative effect on 2025 revenue at approximately $370 million. Here, quality documentation had a very tangible commercial price.
The lesson extends beyond pharmaceuticals: inspect the evidence underneath the dashboard. A release process is useful only when its records describe work that actually happened. Viatris’s published value “Be Real” sounds admirably practical. The manufacturing record shows how demanding that instruction becomes in daily operations.
Quality records can decide whether medicines reach patients.
Selling businesses. Buying a different future.
Under Scott Smith, CEO since April 2023, Viatris has been reshaping what it owns. By July 2024, it had completed previously announced disposals including substantially all its over-the-counter business, its women’s healthcare business and its Indian active pharmaceutical ingredients business. Keeping the whole inheritance was no longer the strategy.
Meanwhile, it paid Idorsia $350 million upfront in 2024 for rights involving two Phase 3 development programs, selatogrel and cenerimod. This is the logic of a large commercial network buying access to scientific opportunities. Rights bring development obligations and risk; a late-stage candidate still has to demonstrate that it works and clear regulatory review.
The shift became more explicit on October 8, 2026. Viatris agreed to acquire Pacira BioSciences for $36.50 a share in cash, an equity value of $1.65 billion. The proposed purchase would add non-opioid pain medicines EXPAREL and ZILRETTA, plus commercial and research capabilities. Closing was expected by year-end, subject to conditions. These were promised additions, not yet owned assets.
Eight days later, Viatris announced FDA approval of RYZUMVI for presbyopia in adults, expanding its existing indication. It was exploring a U.S. commercialization partner. An approval and a distribution decision are separate steps, even when the medicine already has a name.
A network still has to earn its keep
The financial picture resists a tidy victory lap. Revenue was $14.30 billion in 2025, against $14.74 billion in 2024. Viatris reported a $3.51 billion net loss in 2025, including a substantial goodwill impairment. Revenue measures the size of the operation; it does not establish profitability.
Its 2026 restructuring plan anticipated $700 million to $850 million in pre-tax charges and a workforce reduction of up to approximately 10%. Management expected $600 million to $700 million in savings once implemented. Those figures are expectations. They also make clear that simplifying a network costs money before it saves money.
There were signs of improvement: second-quarter 2026 revenue reached $3.8 billion, up 5% as reported, alongside a $119 million GAAP net loss. Supply remained a constraint. Following a fire and subsequent inspection observations at Nashik, India, the company forecast $100 million to $150 million of second-half revenue impact from disruptions.
What can another operator borrow? Build distribution deliberately, partner where expertise is missing, and measure delivery from the customer’s end. Viatris reports a 92% on-time, in-full customer service level for 2025. Such a model depends on reliable quality systems, workable local economics and products people need. Without them, geographic reach becomes expensive geography. The clinic doorway remains a useful test: did the treatment arrive?