A client asks a wealth adviser a reasonable question: how am I doing? The answer ought to arrive before the coffee goes cold. Yet the ingredients can be scattered across custodians, fund statements, transaction systems and somebody’s indispensable spreadsheet. Valuefy has built a business around bringing those ingredients together. Its ambition reaches beyond a tidier chart: the same information should support the recommendation, the order, the fee calculation and the next client conversation.
That puts the company in an unusually revealing corner of financial technology. Consumers may never encounter the Valuefy name. Banks and wealth firms can put their own branding on its applications. The visible experience belongs to the institution; Valuefy supplies much of the machinery underneath. Its buyers include private banks, asset managers, wealth advisers and family offices, organisations whose polished client service depends on decidedly unpolished operational work.
The first obstacle was a familiar workbook
Sharad Singh and Vivek Singal founded Valuefy in 2010 after working at Fractal Analytics. Their early specialty was helping investment teams understand what drove portfolio performance. The difficult part was persuading people to change familiar habits. In a 2016 founder interview, Singal described customers attached to Excel and a market that moved slowly. Larger institutions proved more receptive. Valuefy also moved from hosted software toward SaaS.
“It was a slow journey, but definitely a profitable journey.”Vivek Singal · April 2016
The account offers a useful correction to the standard software origin story. A sharper analytical tool did not automatically create demand. Adoption required a buyer willing to reorganise the work around it. The company’s early response included distribution partnerships and an advisory board. That is a practical lesson for specialist software founders: understanding the calculation and reaching the person who will pay for it are separate jobs.
Five verbs, one working day
Today the platform’s structure reads like an adviser’s to-do list: Engage, Analyse, Advise, Execute, Operate. Together, they cover the journey from a prospective customer to an account that needs servicing, monitoring and reporting. The older “Wealth in a Box” description captures the breadth. The current website also uses Wealthfy, alongside the separate ValueAT analytics offering.
Engage handles the front door: prospect tracking, digital onboarding and branded mobile applications. An adviser can see documents, interactions and portfolios in a common workspace. For a bank, the attraction is continuity. The person who began an application on a phone should not have to become a new administrative puzzle when a relationship manager takes over.
Analyse assembles portfolios across assets held with the institution and assets held elsewhere. It adds comparisons, attribution and reports that an adviser can take into a meeting. Advise supplies model portfolios, investment-policy rules and planning tools. Execute carries instructions into an order workflow. Operate deals with the chores that survive every elegant product presentation: reconciliation, billing, administration and exceptions.
- 01EngageKnow the client
- 02AnalyseSee the holdings
- 03AdviseSet the plan
- 04ExecutePlace the order
- 05OperateClose the books
Consider a hypothetical client whose portfolio has drifted away from its agreed allocation. The useful software journey begins by showing that drift, carries the proposed rebalance through the client’s mandate checks, then records what actually happened. If each stage requires a fresh export, an employee must keep the versions straight. Valuefy’s proposition is to connect those stages closely enough that the instruction retains its context.
A large asset figure with a small but crucial distinction
Valuefy’s May 2026 materials say it processes more than $300 billion in assets annually and serves more than 50 institutions. Its public customer display includes ICICI Bank, HDFC Bank, Barclays, IDFC FIRST Bank, 360 ONE and Waterfield Advisors. IDFC FIRST Bank’s published vendor list separately names Valuefy Technologies Private Limited, including its former Solutions name.
Company-reported · May 2026
Those assets belong to the financial institutions’ investment ecosystem. The figure describes the reach of Valuefy’s technology, not its revenue, valuation or a pot of money its founders personally invest. That distinction matters because the company earns its place as an infrastructure supplier. Its success depends on institutions choosing and using the software.
Different buyers bring different headaches. A bank needs an application that can serve several customer segments while respecting its internal permissions. A family office needs to see through ownership structures. Valuefy’s family-office offering explicitly covers trusts, companies, currencies and alternative assets, including art. A painting does not send a daily price feed. Its valuation and paperwork still need somewhere sensible to live.
Why the analytics still matter
ValueAT preserves the company’s original investment-team focus. Its published capabilities include return attribution, pre-trade analysis, mandate monitoring and risk reporting. Attribution breaks a result into the decisions behind it. A fund’s return is the headline; the contribution from allocation or security selection explains more about the manager’s work.
The product applies different methods to different investments. Equity attribution and fixed-income analysis need different treatment. ValueAT describes debt analysis covering carry, yield-curve movements, credit and selection. It also shows how a proposed trade could change duration, issuer exposure or sector concentration before that trade reaches the dealer.
For an investment committee, this is a more demanding job than displaying performance. The system must help people explain decisions and inspect constraints. ValueAT’s demonstrations also track differences between model portfolios and individual accounts. The practical value lies in noticing a deviation while someone can still act on it, with a record of the information behind the decision.
The price sits beyond the licence
Valuefy sells through institutional conversations, demonstrations and customer agreements. Software scope, integrations and implementation therefore belong in the buying discussion together. The buyer is arranging a working system around existing accounts, data feeds and staff responsibilities. A feature checklist can describe the destination while saying surprisingly little about the journey.
In its May 2026 essay on fragmented software, Valuefy argues that buyers should count integration upkeep, reconciliation, billing discrepancies and audit preparation. Those are vendor arguments, not audited savings for every customer. They do, however, identify costs a procurement spreadsheet can miss. Someone pays for the time spent explaining why two reports disagree.
The sensible test is a sample of the buyer’s actual work. Follow an awkward transaction, inspect an exception and reconcile the final report. Ask who maintains each connection and what a data migration demands from the operations team. A low subscription bill can coexist with a laborious daily routine; a broader platform can also become expensive if the institution buys capabilities it barely uses.
AI meets the client who hates forms
Two recent Valuefy ideas show where its product thinking is going. “Zero-input” financial planning starts with a draft built from available information rather than an empty questionnaire. For a new prospect, that may involve cohort assumptions; an existing customer may already have holdings visible to the institution. The client then corrects the proposed plan and can supply more information.
The appeal is easy to understand. Reacting to a proposed retirement date is easier than constructing a financial future from a blank page. But an inferred household is still an approximation. The useful design choice is to make assumptions visible and editable. A convincing first draft earns its usefulness through correction, especially when someone’s circumstances differ from the group used to sketch them.
The Synthetic CIO addresses a different inconsistency: what the investment committee decides and what each adviser tells clients. Valuefy describes AI support that combines house views with portfolio context to prepare relevant talking points. The aim is to spread informed preparation across the adviser network. Whether it helps depends on the quality and currency of both inputs. A fluent explanation cannot repair an incorrect holding.
What changed at fifteen
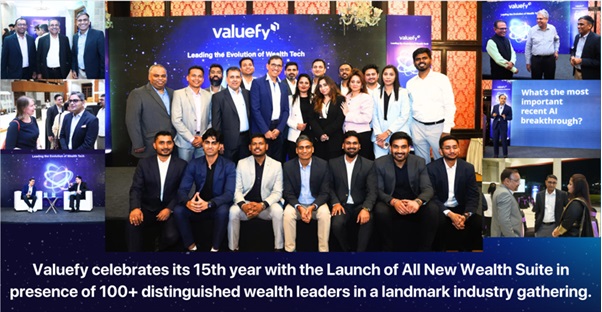
In March 2025, Valuefy marked its fifteenth anniversary by launching a new integrated platform at Mumbai’s MCA Club. The company said more than 100 wealth-industry leaders and partners attended. The announcement emphasised analytics, client engagement and connected workflows, evidence of how broadly the business now defined the problem it wanted to solve.
Its current leadership page names Srutaban Mukhopadhyay as CEO and lists Singh and Singal as founders. The company describes its working approach through five disciplines: finance, quantitative analysis, technology, AI and user experience. That combination fits a product whose users range from investment specialists to client-facing staff. Each group needs accuracy; they do not all need the same screen.
The next sale has to survive Monday morning
Valuefy occupies a competitive market. InvestCloud also offers institutional wealth technology across client engagement, data and operations. Existing systems, specialist products and internal integrations provide other routes. Valuefy’s particular pitch combines investment analytics with broad workflows and explicit connections to Indian market infrastructure. The relevant comparison is how well each option handles a buyer’s own assets, channels and controls.
Its bank rollout model acknowledges that installation is a sequence. Reporting and adviser tools can sit over an existing core first; customer journeys, advisory and execution follow, with AI added as another layer. That gives buyers a concrete idea to copy: establish one useful working stage before making the next stage depend on it.
Consolidation is most persuasive when fragmented information already consumes meaningful effort. A firm with a narrow, well-functioning workflow may have less to gain from a broad replacement. For Valuefy, the everyday test is wonderfully ordinary: can an adviser answer the client’s question, act on the answer and trust the report that follows? That is where the spreadsheet relay finally ends.
Website · ValueAT · Request a demo · Company insights
LinkedIn · Twitter / X · Facebook · YouTube channel · 2025 launch announcement