In 1985, Trinidad and Tobago Unit Trust Corporation offered investors an unusual reassurance. Buy units in its Growth and Income Fund, hold them continuously for three years, and the redemption price would not fall below the purchase price. For someone approaching the stock market with considerable suspicion and a modest pay packet, that was a persuasive invitation.
The provision was meant to be temporary. It lasted four decades. On February 2, 2026, UTC stopped attaching it to new investments. Existing eligible balances retained the feature. A small change in fund documentation contained a much larger story: an institution built to introduce people to investing now believed its market had matured enough to dispense with an early reassurance.
- Small savings, professionally managed.
- TT$100 opens the TT$ Income Fund.
- New GIF units lost the guarantee in February 2026.
A market with room for the small saver
UTC came from legislation, rather than a founder’s garage. The 1981 Act took effect in February 1982; trading began that November. Its organising idea was straightforward: pool individual savings, invest them professionally, and give ordinary people access to opportunities that would be cumbersome to assemble alone. The customer bought units in a collective portfolio.
The distinction matters. A saver did not need to select every company or become a securities analyst. UTC supplied portfolio management and a structure for participation. Today its customers include individuals, businesses and government institutions, with products spanning short-term income, education savings and retirement. The practical problem it addresses is the distance between having something to save and knowing how to invest it.
The opening machinery had a price. Initial institutional contributions totalled TT$5 million, from the Central Bank, insurers, the National Insurance Board, and commercial banks and financial institutions. The Central Bank also agreed to supply management and other services through December 1984 for TT$250,000 a year. This was financial infrastructure with an institutional sponsor.
The first leak was impatience
The first annual report records an awkward development. Unit capital contracted from roughly TT$36 million at the end of 1982 to TT$32.1 million by June 1983. Some investors withdrew money to pursue quick capital gains in new share offerings. Even a collective investment vehicle could lose attention to the excitement of an individual stock.
That episode suggests a useful distinction: opening the door to investment and establishing a saving habit are separate jobs. UTC’s early response included promotion, education and a reinvestment plan. Decades later, its Foundation still works on education and financial well-being. Access requires repetition. The paperwork can admit a customer; it cannot supply patience. A fund manager therefore has a second audience beyond the person buying units today: the same person deciding next month whether to add more, withdraw everything, or let the investment continue.
“We are a fledgling institution and require the support of the entire population”John Hunt · Founding chairman · 1982 annual report
Five units and a decision
The contemporary entry point can be pleasingly ungrand. UTC’s TT$ Income Fund allows an account to open with five TT$20 units, or TT$100. Its product page describes no minimum holding period and no withdrawal penalties, with income credited quarterly. It also says the quoted yield is an estimate, without a guarantee that it will be realised.
That combination makes the fund relevant to people seeking income while retaining access to cash. The Growth and Income Fund serves a different, medium-to-long-term purpose and carries a moderate risk classification. The Universal Retirement Fund addresses a longer horizon. Global Investor Select ETF funds offer conservative, moderate and aggressive options. Different objectives require different portfolios; a familiar brand cannot make those distinctions disappear.
UTC earns management charges for administering investment funds. The Growth and Income Fund’s 2025 interim accounts describe a maximum annual management fee of 2% of net asset value. That is a ceiling specified for this fund, rather than a universal price for every UTC product. Uon, its online account-management platform, is free to register for and use. Fund expenses and transaction terms still deserve their own reading.
For a prospective customer, the sensible sequence is concrete: decide when the money will be needed, identify the currency and risk level, then read the relevant prospectus. Someone expecting immediate access and no possibility of capital loss should examine those requirements carefully before choosing an equity-oriented fund. The 2026 guarantee change makes the subscription date especially consequential.
The branch now fits in a pocket
Uon brings the everyday administration online: customers can move Trinidad and Tobago dollar funds between UTC and local banks, transfer within their UTC accounts, access statements and upload registration documents. Two-factor authentication is part of the platform. The attraction is less cinematic than a trading floor and more useful: fewer errands between the decision to save and the act of doing it.
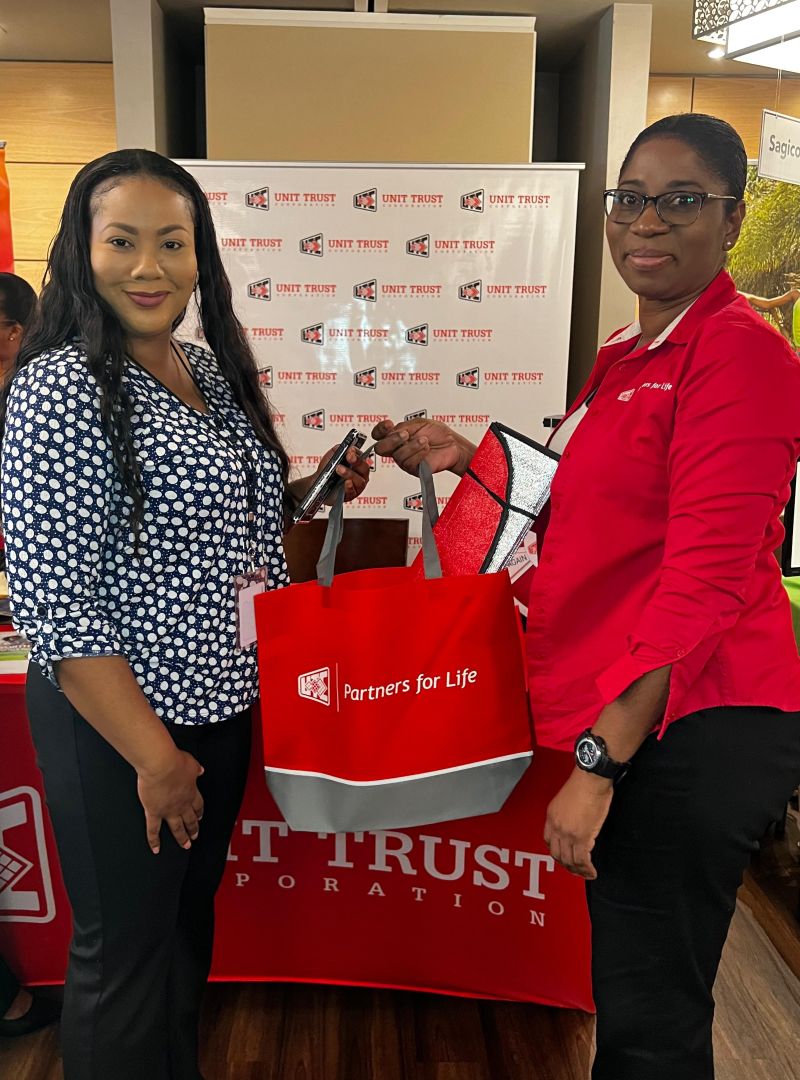
UTC also retains Investment Centres. Its presence at UDECOTT’s Financial Fair in 2024 included account openings, payment setup and investment discussions. That combination of digital access and face-to-face explanation suits an institution whose remit includes helping people understand the product. A downloadable form and a conversation solve different parts of the same problem.
A bigger cheque, a wider Caribbean
At its May 2026 annual meeting, UTC reported TT$659.9 million in distributions to investors for 2025, up 33.3% from the previous year. Distribution payments describe money paid out across funds; they are not the percentage return of any particular customer. The distinction is essential when a large headline number starts doing the work of an investment argument.
UTC operates alongside Republic Bank, Scotiabank and First Citizens investment businesses. Its distinctive position rests on its statutory origin, long retail history and explicit savings-education mandate. Those traits help explain the franchise; they do not establish that every UTC fund beats every alternative. Currency, expenses, access and investment horizon remain useful grounds for comparison.
The ambition now extends across the region. UTC reported that its Global Balanced Fund operated across six Eastern Caribbean Currency Union member states by its 2026 meeting. At home, Scale Up TT pairs business acceleration with mentorship; a Ministry of Trade and Industry partnership supports the programme. Teaching households to invest and helping businesses grow are connected to its original economic-development purpose.
The lesson others can borrow is the order of operations: provide an accessible product, explain it, make repeat participation convenient, and revisit the terms as the audience changes. It depends on credible management, sustained education and a product that fits the customer’s actual needs. UTC’s four-decade guarantee offers a memorable final detail. In finance, even a temporary measure can acquire a pension.