The family chore is an ancient institution, performed under several management systems: affection, duty, nagging and, when negotiations become sophisticated, money. Timothy Sheehan grew up in a household where chores belonged to the first category. You did them because you were part of the family. There was no tiny payroll department waiting at the kitchen table.
So when Sheehan became a father, he followed the custom he knew. His four children did not receive allowances. Then came the irritating discovery familiar to any parent: a principle can be perfectly clear to the adult explaining it and entirely invisible to the child hearing it. The children were not learning what he hoped they would learn about money. The household policy changed. Allowance entered the picture, and with it came decisions that could be repeated: spend now, wait, save, reconsider.
That small reversal matters because it explains Greenlight more neatly than a stack of pitch decks. Sheehan did not begin with a card. He began with a gap between instruction and experience. A lecture could describe patience. Ten dollars and a coveted toy could test it.
Money, made visible
Sheehan had spent his career around the machinery of personal finance before he aimed it at children. He worked in product at E*TRADE, became director of Yahoo Finance and later served as general manager at Yodlee. A former colleague credited him with the vision behind Yodlee's MoneyCenter, released in 2006, and remembered the work required to align a company behind a new flagship. Sheehan then co-founded Reachable, a social-media marketing platform, before joining Fiserv as a senior vice president responsible for products, marketing and strategy in its biller-solutions business.
The sequence is useful. Brokerage, financial information, account aggregation, bills: each job dealt with making money legible on a screen. At Greenlight, the screen moved into a more delicate setting. The user was sometimes eight years old. The administrator might be making dinner.
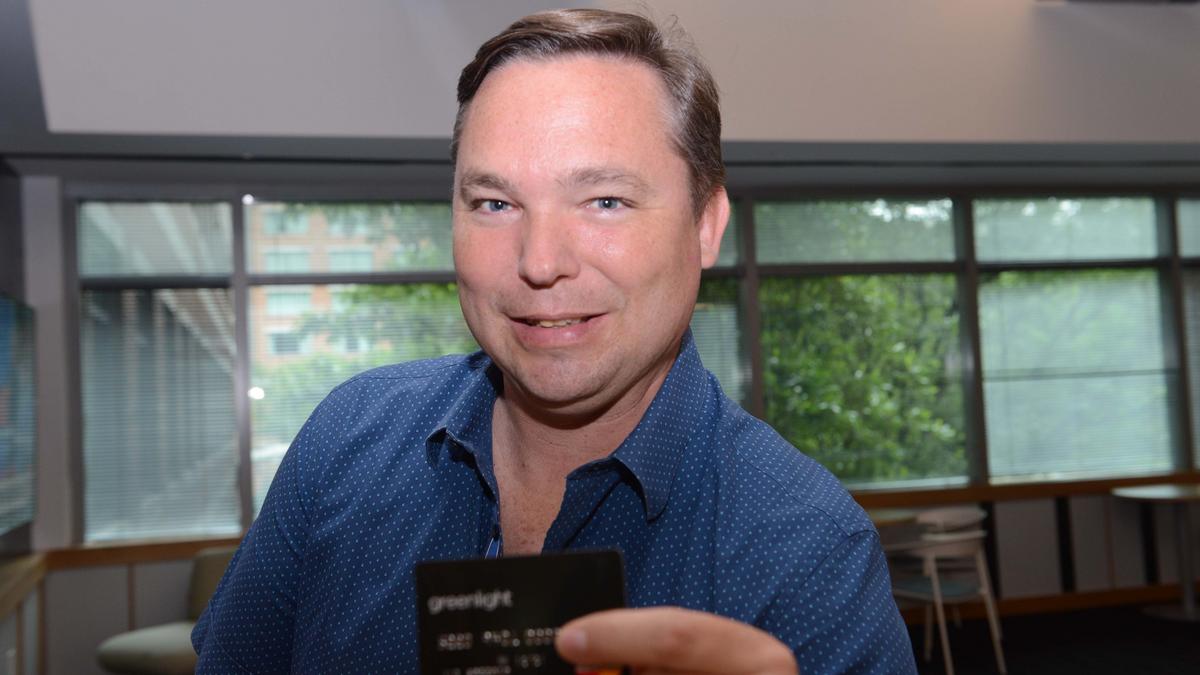
Before founding Greenlight, Sheehan also served as lead entrepreneur-in-residence at Georgia Tech's Advanced Technology Development Center. In 2014, he and Atlanta entrepreneur and investor Johnson Cook started the company. Their premise was plain enough to survive the jargon: parents needed a way to help children practice money management in a world steadily misplacing its cash.
The lesson he inherited
The premise also carried a family debt of the agreeable kind. Sheehan has said his father gave him useful financial habits early. Only later, after money became his profession, did he notice how unevenly that knowledge was distributed. Friends and peers had reached adulthood without the same preparation. The comparison turned a private advantage into a public question: could the essential parts of that education be made available to families who did not happen to have a confident money teacher at home?
His own children made the problem specific. Children were becoming fluent in taps, swipes and one-click purchases while the old props of instruction were disappearing. Cash at least announced its departure. Digital money could vanish politely, leaving behind a notification and no physical sense of scarcity. Parents had gained convenience while losing some of the theater that once made spending comprehensible.
Sheehan brought the financial-product map; Cook brought a deep Atlanta startup network. Cook had founded Atlanta Tech Village and spent years as an entrepreneur, investor and community builder. The partnership placed Greenlight in a city with a dense payments industry but outside the usual coastal startup script. That mattered. Greenlight was close to banking infrastructure and to an ecosystem accustomed to the unglamorous work of moving money correctly.
There was also a useful division of attention. Cook drove growth and expansion as president. Sheehan led the product vision as chief executive. The company could pursue financial partnerships and consumer adoption while keeping the family interaction at the center. The target customer was technically a household, which meant every feature had at least two constituencies and, on a difficult day, several opinions.
The green light in Greenlight
The early product paired a debit card with two views of the same small economy. A child could see a balance, pursue a savings goal and spend. A parent could move money, set boundaries and receive transaction alerts. The arrangement made independence conditional without making it imaginary. A child still chose; a parent still had a brake pedal.
This balance is harder than it sounds. Total control produces compliance, not judgment. Total freedom can produce a remarkably educational afternoon at the mall. Greenlight placed the lesson between those poles. Parents could approve where money went, but children could watch their own progress and encounter the trade-off themselves.
Parent supplies the rails
Allowance, chores, spending controls, approvals and a view of each transaction.
Child supplies the choice
Spend, save, give or invest, then see what the decision changes next.
Sheehan's preferred word is not curriculum but habit. He has said the product was built to fit into parents' and children's lives so learning could happen naturally. The distinction is practical. Families rarely reserve Thursday evening for a seminar on compound interest. They do, however, encounter birthdays, chores, requests, misplaced cards and the urgent requirement for sneakers.
One young customer supplied Sheehan with a favorite example: at thirteen, the child used Greenlight while starting a book-publishing business. The tale is charming because the money tool recedes. The interesting thing is what the child decided to do with it.
When the numbers grew up
Greenlight arrived on the market in 2017 and soon met a national appetite. In 2020, the company raised $215 million at a $1.2 billion valuation. Six months later, a $260 million round led by Andreessen Horowitz valued it at $2.3 billion. The company said that round brought total funding above $550 million and would support product development, distribution and hiring.
Sheehan and Johnson Cook found Greenlight in Atlanta.
Series D funding announced in April 2021.
Family members served when Family Hub launched in 2026.
Capital changed the scale, but it did not simplify the job. In early 2023, Greenlight reduced its workforce by more than one hundred people. In a live interview, Sheehan described the macroeconomic environment as difficult and said the company had acted to continue serving customers. He returned quickly to the work in front of it: Level Up, a financial-literacy game, and Greenlight for Classrooms, offered free to teachers and students.
There is a revealing sobriety in that answer. Sheehan has been described by a former colleague as “grounded and wise,” praise so untheatrical that it sounds plausible. His public manner is closer to product review than revival meeting. Even his grandest stated aim - a world where every child grows up financially healthy and happy - is usually followed by a feature list.
A product career becomes a family platform
Yodlee releases MoneyCenter, a product former colleagues say Sheehan helped champion.
Greenlight begins with the problem of teaching children about money.
Investing joins the family platform as Greenlight closes its Series D.
Family Hub carries the company's organizing instinct from the wallet to the household.
The wallet leaves the wallet
Over time, Greenlight added savings, investing, cash rewards, financial education and safety features. A card for children became a family account, then a family platform. In June 2026, the company pushed the idea into hardware with Family Hub, a dedicated screen for calendars, chores, photographs, lists, location tools and a family assistant.
At first glance, a smart household display sits some distance from a child's debit card. Through Sheehan's product logic, the distance is shorter. Both take a recurring negotiation that lives in a parent's head and put it somewhere the family can see. Who has practice? Who finished a chore? Where is everyone? What are we saving for? Software becomes the neutral third party, less exhausted than a parent and less inventive than a teenager.
At launch, Greenlight said the broader platform had managed nearly $10 billion across earning, spending, saving and investing. Family Hub also signaled a change in the company's self-description. Greenlight was no longer presenting itself only as family finance. It was becoming family technology, with the daily household as its operating system.
Practice before consequence
Sheehan's work outside Greenlight now extends the pattern. He participated as an angel investor in banking-infrastructure company Synctera and joined the board of property-management software company MagicDoor in 2025. He is also named on a 2013 patent involving the ranking of targets in a universal graph. The details vary, but the fascination is consistent: systems that turn complicated information into an action a person can take.
For children, the actions remain wonderfully modest. Wait another week. Move five dollars to savings. Ask why a stock price moved. Learn that a balance is not an invitation. Sheehan argues that investing, learned well, can alter a child's future. Yet the more immediate achievement may be simply making tomorrow visible enough to compete with today.
This is the comic unfairness of financial education: adults introduce it after the money has become serious. Rent is due. Credit has a memory. Errors acquire fees. Greenlight's answer is rehearsal. Let the first budget be small, the first failed plan survivable and the first flash of buyer's remorse cheap.
Sheehan learned that lesson as a parent before he sold it as a founder. His children did not need another explanation of what money meant. They needed money to mean something in their own decisions. The allowance did the work. Greenlight gave it an interface.