The motorbike had to go. Somewhere in the early life of INSTANDA, Tim Hardcastle needed money for payroll, and a machine built for his own enjoyment became a way to keep other people working. Years later, he would tell the story while discussing the business he had helped build. It is a useful detail to keep beside the funding announcements. Before there were investors writing substantial cheques, there were possessions that could be sold.
Hardcastle’s professional life has involved a recurring disagreement with waiting. Insurance businesses wanted to create products, reach customers and adjust to changing circumstances. The technology between the idea and its execution could make those ambitions painfully slow. He had occupied the CIO’s chair. He knew what it meant to be responsible for the machinery, and to explain why the machinery could not easily do what people wanted.
His eventual answer, developed with co-founder Derek Hill, was INSTANDA: software intended to let insurance teams configure products and run them without commissioning a fresh coding project for every change. The proposition sounds tidy. Getting it into the world required years of work and a rather less tidy relationship with personal finances.
An accountant discovers the queue
Hardcastle began as a chartered accountant. Technology leadership followed, across more than one industry. That route matters because insurance was a business he entered with other ways of doing things already in his head. He could recognise familiar technical problems without accepting every local explanation for why they had to remain unsolved.
In 2005, he joined Hiscox as chief information officer after being headhunted. Its business gave him a view across different kinds of insurance, from large specialist risks to household cover. He has described learning from its then chief executive, Bronek Masojada, and from other senior leaders. Hiscox became an education in the workings of insurance and an important influence on what came next.
He became a founding partner of the consultancy F2X Group in 2006. Consulting gave him more opportunities to test what he had seen against other insurers and brokers. The problem kept recurring: people with ideas for their businesses were constrained by the systems expected to support them. An internal frustration was becoming a possible business proposition.
The distinction is practical. A person who understands a customer’s needs may still have to wait for somebody else to alter a screen, a pricing rule or a document. Every dependency adds a conversation. Enough conversations can consume the opportunity. Hardcastle’s interest lay in shortening that distance between knowing what should change and being able to change it.
The coffee was the inexpensive part
Hardcastle and Hill discussed their idea in a London coffee shop. “We started Instanda from nothing in Starbucks,” he recalled. The business is generally dated to 2012; the platform’s first customer went live in 2015. Those dates leave room for the part of entrepreneurship that a founding announcement rarely conveys: building something people can actually use takes longer than describing it.
Their proposal was to put more of the work into the hands of insurance businesses themselves. Personalised services needed to be possible at scale, at a cost that would allow them to make commercial sense. A clever product idea would have limited value if turning it into a working insurance offering remained prohibitively expensive.
In the early years, Hardcastle and his colleagues mortgaged homes and sold assets to fund wages. His later account of the motorbike gives that broader statement an unusually concrete shape. The founder asking others to trust a new business had put his own resources into keeping its commitments.
A chance meeting with Robin Merttens at the Royal Exchange also became part of his account of that period. They were pursuing separate ventures, comparing experiences and ideas. Their conversation developed into a friendship and continuing debates about insurance. When they revisited it a decade later, the setting offered a reminder of how long an apparently new technology business can take to become established.
“We started Instanda from nothing in Starbucks.”
Tim Hardcastle, 2023
Give the underwriter the controls
To understand the appeal of the proposition, forget the software vocabulary for a moment. An insurance product consists of decisions: what questions to ask, which risks to accept, how to calculate a price, what documents to issue and what happens when a customer needs a change. Somebody has to translate those decisions into a system that works.
INSTANDA lets clients configure that work. Its platform covers product creation, quoting, distribution and policy administration. The underlying software still requires engineers; the company maintains it. The change is that clients can assemble their own combinations of questions, calculations, documents and processes without each combination requiring alterations to the core code.
For Hardcastle, that is a question of who holds the controls. The insurance specialist should be able to exercise judgement through a tool that responds to it. A pricing decision ought to become usable in the business while the circumstances that prompted it still apply.
A conceptual guide to the work, not a measured implementation timeline.
This does not make insurance simple. It changes where some of its complexity is handled. Product specialists can spend more of their effort on the product, while technical teams maintain the platform and connections beneath it. The customer still needs a clear explanation of what is being bought. A quicker system is useful only if somebody uses it to produce something worth buying.
The people do not come preconfigured
Hardcastle’s discussion of successful customers includes an awkward qualification for anyone hoping to buy instant organisational harmony. Teams need a clear intention and a willingness to participate. He has described implementations becoming difficult when underwriters resist the changes rather than engage with them. A platform cannot settle the argument about what a business wants to become.
His view of brokers makes a related point. He sees room for intermediaries to use their knowledge of customers in more sophisticated ways, including advice about preventing losses. Software can help personalise an offering, but the relationship and the judgement still have work to do. The ambition gives people different tools and asks them to use their expertise more effectively.
He has also spoken about inclusion inside his own company. In 2023 he identified himself as Anglo-Indian and described the value of having different cultural backgrounds in the business. His test for diversity went beyond assembling a list of people: communication had to be inclusive, and the working environment had to allow merit to count.
That concern sits naturally beside the product argument. Giving people control has limited meaning if they cannot contribute to the conversation. For a founder selling the ability to make changes, the behaviour around a meeting table deserves attention too. The same question keeps returning in different clothes: who gets to take part?
A larger room to prove it in
The business opened a US office in 2019. A $19.5 million Series A followed in 2020. In June 2022, INSTANDA announced another $45 million, led by Toscafund with participation from existing investor Dale Ventures. The stated uses included expanding capabilities and supporting growth, particularly in North America.
The timing gave Hardcastle a further subject to be blunt about. Insurtech funding was facing a reassessment. He argued that investors still had appetite, but were asking harder questions about valuation, cash consumption and a route to profitability. The enthusiasm of a market could change faster than a company’s need to pay its bills.
By September 2026, INSTANDA reported more than 100 clients and over 60,000 insurance professionals using the platform, with client products operating in more than 170 countries. These are company-reported measures of reach. They describe how far the proposition has travelled; they do not remove the need to prove it to the next buyer.
Figures reported by INSTANDA. Countries refer to client product coverage, not company offices.
North America remains a particular test. Josh Hall’s appointment as regional chief revenue officer, effective July 2026, gave the expansion a dedicated commercial leader. Hardcastle has described a market carrying considerable frustration with lengthy core-system projects. His next audience includes experienced buyers who have heard promises about transformation before. They have reasonable grounds to ask for particulars.
Speed, with somewhere to go
There are glimpses of a life outside the implementation schedule. As a child, Hardcastle read Marvel comics, science fiction and fantasy. In 2023, he talked about a longstanding wish to race in the Caterham series, looking ahead to 2024. The stated ambition suits somebody whose interest in motorbikes is clearly more than decorative.
One principle he has carried into design is advice he remembered in connection with the Sony Walkman and later heard echoed by a company chairman: “Making the complex simple to comprehend is real elegance”. It is a useful standard for someone selling software to a complicated industry. The work has to become intelligible to the person trying to use it.
His more recent public activity includes joining the Insurtech UK Council, extending the conversation beyond his own company. The undertaking remains unfinished. There are more customers to persuade, more processes to improve and more opportunities for a complicated business to surprise its software supplier.
The early motorbike story supplies a reminder of what those ambitions once required. Today the work is less about finding the next payroll run and more about making a larger organisation deliver the freedom its founders imagined. Hardcastle has spent years asking an industry to move faster. He has learned how much patience that can take.
Continue the conversation
- INSTANDA: the company and platform ↗
- Tim Hardcastle on LinkedIn ↗
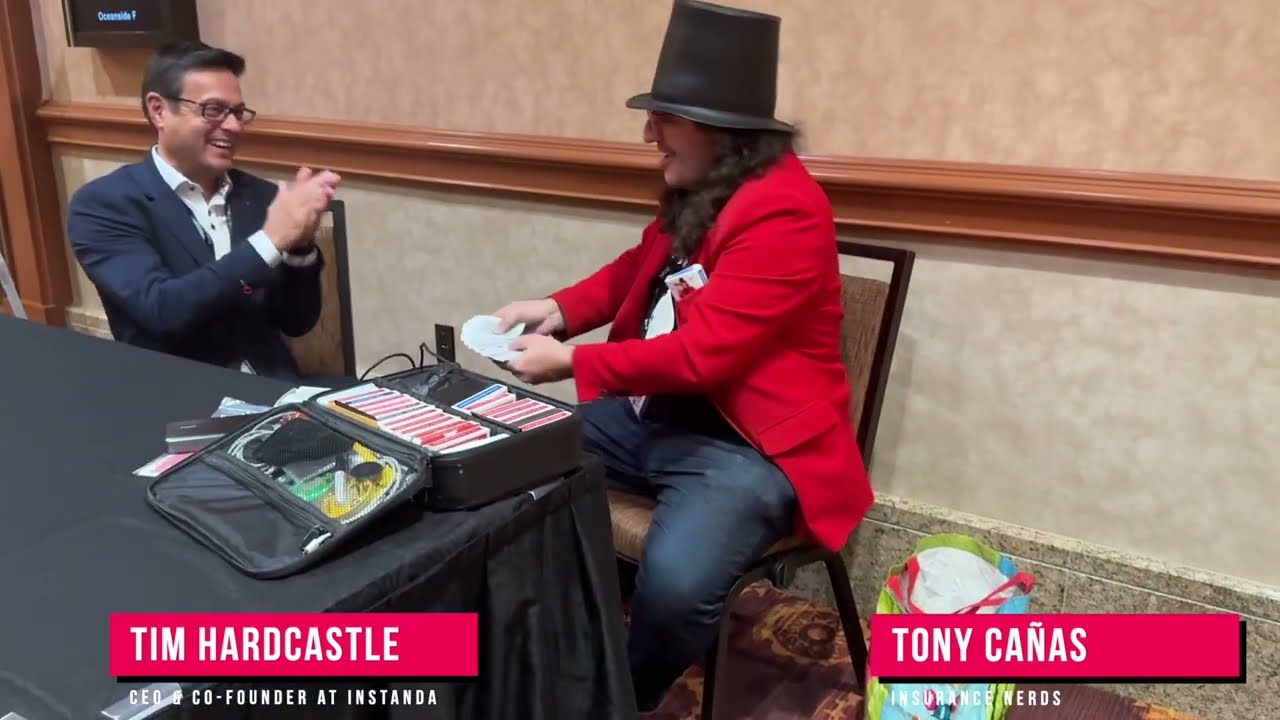
- Watch: Insurance Nerds at ITC 2023 ↗
- Watch: Risk Management: Brick by Brick ↗
- Listen: the early years, revisited with Robin Merttens ↗
- Read: the North American plans, September 2026 ↗
- Read: the coffee-shop beginnings and inclusion ↗
- Read: comics, motorcycles and design principles ↗
- Browse: Hardcastle’s published commentary ↗