An office move is usually a story about parking. In Dan Gilbert’s case, it became a story about a city. In 2010, he brought 1,700 team members into downtown Detroit. The decision put a mortgage business in a place where its ambitions soon extended beyond mortgages: buildings, public spaces, startups, somewhere to go after work.
- Rock.com is home to ROCK, the Gilbert family office.
- It connects businesses including Rocket, Bedrock, StockX and the Cavaliers.
- Its distinctive bet: businesses and their surrounding communities can grow together.
That last part matters. A company recruiting young people needs more than desks. It needs a place people want to inhabit. ROCK’s account of the move describes scattered suburban offices and a choice: build a campus, or move downtown. The problem had begun with collaboration. The answer included restaurants, housing, entertainment and the neighborhood outside the door.
The office between the businesses
Visit Rock.com today and you will find the family office for Dan and Jennifer Gilbert. Its predecessor, Rock Ventures, launched in 2007; the ROCK name arrived in 2023. Rock Holdings is a related entity. Rocket Companies is the publicly traded homeownership business. The names overlap. Their jobs and legal structures deserve separate treatment.
ROCK connects more than 100 entities. Its published specialties include operational coordination, communications, government relations, technology and community building. Think of the practical problem: a property developer, a lender and a basketball organization can share relationships and ideas while requiring very different management. Someone has to make the connections useful.
The family-office customer is principally the family and its business network. Everyone else encounters the operating brands: borrowers seeking a mortgage, founders seeking investment, tenants seeking space, fans seeking an evening out. A person shopping for a loan should go to the lender. Rock.com explains the wider arrangement.
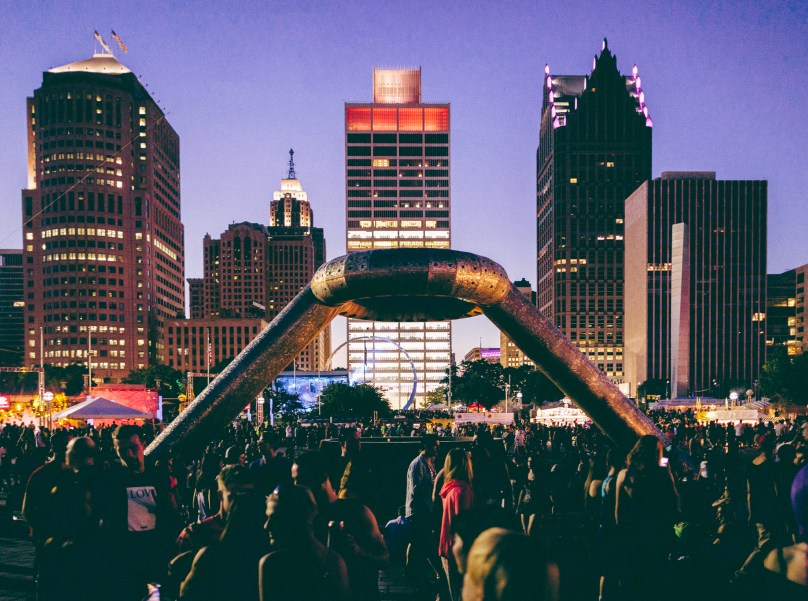
One mortgage business, several kinds of money
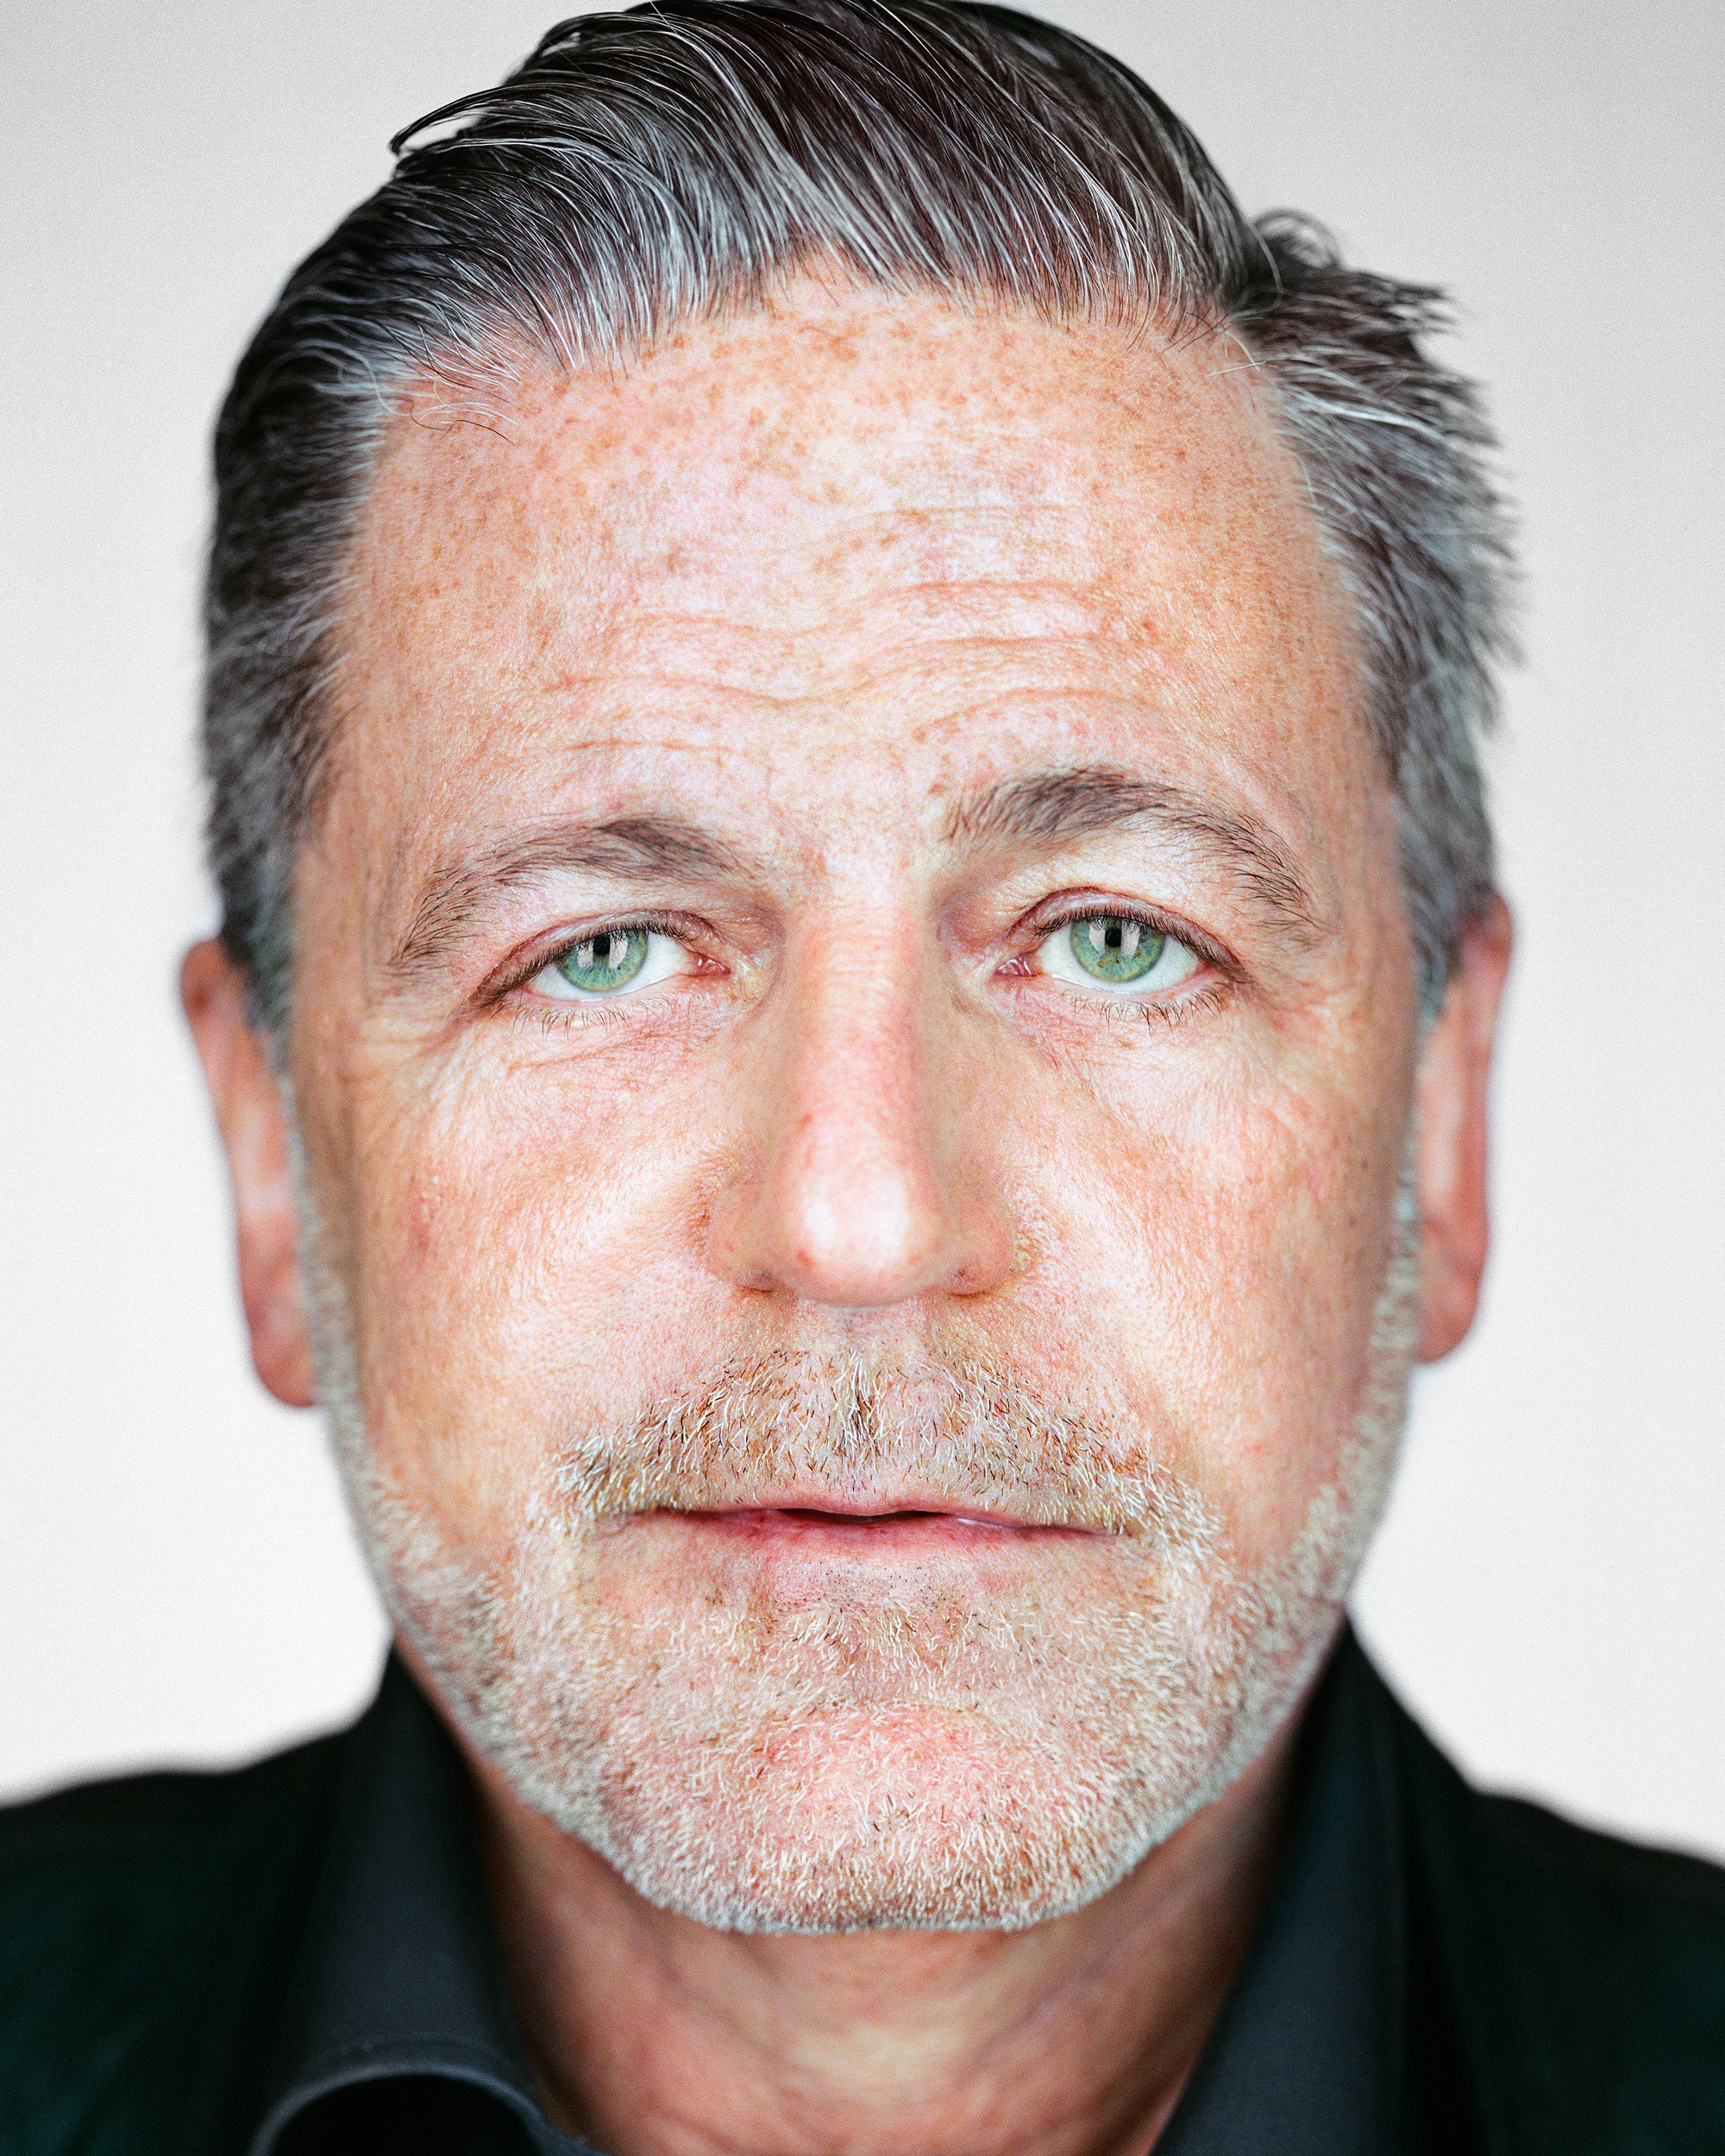
Dan Gilbert, photographed for Detroit Venture Partners, the venture firm he founded in 2010.
The original engine was Rock Financial, which Gilbert launched in 1985 with $5,000, according to ROCK’s history. Mortgage lending supplied the platform for later investments. But the resulting network is more interesting than a list of holdings: its activities solve different problems and collect money in different ways.
Rocket’s businesses handle home financing and related services. Bedrock develops and manages property. StockX connects buyers and sellers of sought-after products. Detroit Venture Partners backs early-stage technology companies; Rockbridge Growth Equity invests in established businesses. The Cavaliers sell a different experience altogether. A mortgage customer and a basketball fan need never know they occupy the same family-office diagram.
ROCK’s published capital-deployment framework. These routes have different return expectations.
That mix distinguishes ROCK from a mortgage lender or a conventional investment fund. Its stated framework includes both commercial investment and philanthropy. The distinction is essential: a grant is money committed to a purpose; property is an asset with operating costs; a venture investment may take years to return anything.
ROCK reports more than $7 billion deployed across Detroit and Cleveland. That is a network-scale figure, not a price tag for running the family office. Likewise, the $500 million Detroit commitment announced in 2021 belongs to the Gilbert Family Foundation and Rocket Community Fund, spread across ten years. Big numbers become less useful when their labels disappear.
The mortgage cycle still gets a vote
A broad network does not repeal the economics of its businesses. Rocket’s closed mortgage origination volume fell from $351.2 billion in 2021 to $133.1 billion in 2022. It reported a $493 million GAAP net loss in the fourth quarter of 2022. The lending business contracted sharply.
Rocket responded by reducing its annualized cost structure by nearly $3 billion, comparing the fourth quarters of those years. Management also emphasized reaching customers earlier and maintaining relationships longer. This is the awkward, useful chapter in the story: a recognizable brand and digital tools did not prevent a market contraction.
By 2025, Rocket was buying more of the homeownership journey. It completed the Redfin acquisition in July and Mr. Cooper in October, the latter described at closing as a $14.2 billion transaction. Home search, financing, closing and servicing could now sit within one platform. The stated aim was lower costs and an easier process; acquisition itself does not prove either outcome.
A shared vocabulary, separate balance sheets
ROCK calls its philosophy “For More Than Profit.” Its ISMs give the network a common vocabulary, including “Launch and learn” and “Simplicity is genius.” Team members attend an ISMs Day. These are portable instructions for businesses whose daily work might otherwise have little in common.
“Numbers and money follow; they do not lead.”ROCK’s published philosophy
The culture also shows up in specific operating decisions. In September 2025, ROCK profiled Dr. Lowell Fernander’s appointment as Rocket’s first chief medical officer. Shared language can travel across companies; medical leadership addresses a particular workforce need. Neither substitutes for the separate governance that the group’s careers site explicitly describes.
The next bet changes the owner
In October 2026, Gilbert pledged $1 billion toward a nonprofit redevelopment of Detroit’s Renaissance Center and surrounding riverfront. The proposed structure would prevent him and his companies from taking profits. It converts a previously planned investment into a gift; it does not add another billion to that earlier commitment.
The proposal still depends on financing and approvals. A philanthropic contribution does not remove construction costs or make public support unnecessary. Here the limits are concrete: buildings need viable operations, cities need accountable decisions, and promises need execution.
The useful lesson for a smaller company is closer to that original office move. Look at the conditions surrounding a business problem. Recruiting may involve the neighborhood. Startup capital may become more useful with operating relationships attached. Copying that habit is possible; copying the scale requires patient money, capable partners and years of work. ROCK’s bet remains tied to the places where that work happens.