The plastic cup is an unpromising place to look for a theory of competition. It has no ambition to impress you. It holds a drink, survives the journey to a table, and usually disappears before anyone asks who made it. Roberto Buaron’s investment career asks us to linger over objects like this. Behind the cup sits a manufacturer; behind the manufacturer, decisions about machinery, customers, distribution, and ownership. Each decision can change the business without changing what the customer calls the product.
Buaron founded First Atlantic Capital in 1989. Before that, he had been a management consultant and a venture capital investor. Earlier still, he studied electrical engineering. In 1981, he published an article with a briskly provocative title: How to win the market share game? Try changing the rules. The question gives his later career an interesting point of entry. What happens when someone who has written about competition takes responsibility for companies competing in the world?
The answer is spread across packaging factories, a distributor of electronic test equipment, label businesses, and New York real estate. These are settings where an idea eventually has to meet a production schedule, a customer order, or a building. A clever argument can travel light. A company carries rather more luggage.
Two business schools, one engineering education
Buaron’s educational route passed through the Politecnico of Milan, where he earned a graduate degree in electrical engineering, then INSEAD in France and Harvard Business School. He holds an MBA from each business school. His Harvard years were 1972 to 1974. Engineering and two MBAs make an unusual combination, even in a profession with a healthy appetite for credentials.
He spent nine years at McKinsey & Company, becoming a partner in its New York office and advising Fortune 500 management teams on strategy and operating performance. From 1983 to 1986, he was a general partner at First Century Partnership, whose venture capital work covered early and later stage investments. A senior partnership at Overseas Partners followed, before he founded his own firm.
That progression changes the relationship between a person and a business problem. Consulting involves persuading managers to act. Investing places capital behind decisions and ties the owner to their consequences. Buaron’s record crossed that boundary after years spent studying companies from the advisory side of the table.
A cup, a factory, fifteen acquisitions
Berry Plastics became a First Atlantic investment in 1990. Based in Evansville, Indiana, it made products including containers, closures, drink cups, and housewares. Its revenue was $57 million that year. By 2001, revenue had reached $462 million. In May 2002, First Atlantic, JPMorgan Partners, and Aetna announced an agreement to sell Berry to a Goldman Sachs-managed fund for $837.5 million, including repayment of existing debt.
The operating chapter matters as much as the sale figure. Between 1990 and 2002, Berry completed 15 strategic add-on acquisitions with First Atlantic’s support. The work also included strengthening management, investing in manufacturing and systems technology, and extending product development and decorating capabilities. Growth had several moving parts.
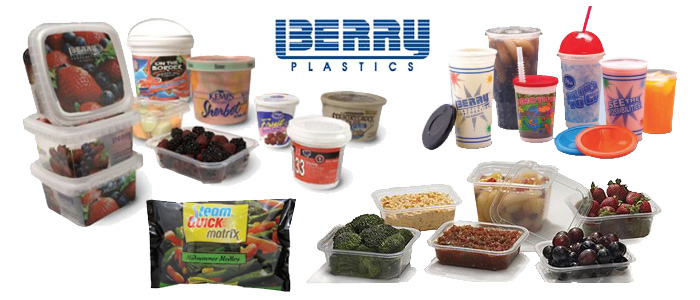
A container can be familiar while the company producing it becomes substantially different. A broader product range changes what a customer can buy. Better manufacturing systems change the cost of supplying it. Adding businesses changes the footprint from which those products arrive. The ordinary object remains ordinary; the organization behind it acquires new possibilities.
Berry’s existing senior management was to remain in place after the announced sale, and the headquarters was to stay in Evansville. Buaron thanked the management team and employees for their commitment. Ownership could change without asking the business to forget the people who had made it work.
This is the useful scale at which to consider his career: close enough to distinguish a machine investment from an acquisition, and wide enough to see how both contribute to the same company. The headline number is the result of the story. It cannot do all the storytelling.
The buyer had been here before
In 2004, First Atlantic acquired Captive Plastics, a New Jersey container manufacturer. The family that had owned the business retained a significant ownership interest. First Atlantic and management changed sales and marketing processes and invested in lower-cost manufacturing technology. Captive also narrowed its customer focus, emphasizing selected consumer markets and moving away from automotive and industrial segments.
After the initial operating work came acquisitions. Three competitors joined the business between August 2005 and August 2006. Captive’s EBITDA, earnings before interest, taxes, depreciation, and amortization, rose from $17 million in 2004 to more than three times that level by mid-2007. Then Berry agreed to acquire Captive in a transaction valued at $500 million.
The buyer supplies the pleasing twist. Berry had once been a First Atlantic portfolio company. Now it was buying another business from the same investor. An earlier chapter of Buaron’s career had become a participant in a later one.
“If you focus on the right segments, that can make a company immune to recession.”
Roberto Buaron, January 2008
Buaron’s remark about recession was a strong claim about the protection that customer selection might offer. Its relevance here lies in the question underneath: whom should the company serve? Packaging may seem like a single industry from a distance. The economics become more particular when you ask what is being packaged, who is buying, and how demand behaves.
That choice preceded the buying program. The sequence gives the Captive episode its shape: improve the business, select markets, and expand around the resulting direction. An acquisition list alone would flatten those decisions into a procession of signatures.
The engineer’s old territory
TestEquity brought Buaron’s investment work into the world of electronic test and measurement equipment. First Atlantic acquired the Moorpark, California-based business in 2012. It supplied equipment as well as laboratory and production products. During First Atlantic’s ownership, it completed two add-on acquisitions in adjacent markets.
The offering extended beyond the purchase of new instruments. TestEquity also supplied equipment through rental and lease arrangements and offered selected pre-owned equipment that had been restored, tested, and calibrated. Its expansion into laboratory and production supplies added products such as tools, workbenches, lighting, and microscopes.
For a distributor, the range of things a customer can obtain together becomes part of the business itself. An instrument sits within a working environment. Supplying more of that environment can change a customer relationship as well as a catalog. The connection to Buaron’s engineering education is appealing, although the investment’s documented story is about strategy, management, and acquisitions.
In May 2017, First Atlantic sold its majority interest to LKCM Headwater Investments. Buaron described close work with management to improve strategy and expand through acquisitions. The five-year arc offers a different setting for the same practical concern: how an owner and management team develop an established business after the purchase.
The label on the bottle
Resource Label Group offered another route into the packaging business. Labels are small surfaces with several jobs: identify a product, distinguish it on a shelf, and carry information. Making them involves design, materials, printing, and application. The business rewards attention to the part of a product most people regard as its finishing touch.
By May 2018, Resource Label served more than 6,000 customers through 13 production facilities and employed more than 900 people in the United States and Canada. TPG Growth invested that month, partnering with First Atlantic. Buaron pointed to further add-on acquisitions and strategic growth as opportunities for the company.
In October 2020, Resource Label acquired Dallas-based McDowell Label, extending its presence in the Southwest. McDowell had been started by Dave and Elaine McDowell in 1981. Here was another established, family-founded business entering a larger group. Buaron spoke of the objective of continued leadership in the label industry.
The label chapter also illustrates the limits of treating an investment firm as the work of one person. Founders, operating executives, investors, and acquired businesses all participate. Buaron’s role belongs within those relationships. A profile can follow its subject without handing him every job in the factory.
A different kind of foundation
In 2010, Roberto and Daniel Buaron founded First Atlantic’s New York real estate business. Roberto manages it. Wholly owned by First Atlantic Capital, the business describes investments in New York and the Midwest totaling more than $300 million in acquisition and development costs.
Its stated property focus includes multifamily, mixed-use, condominium, and office assets in metropolitan markets. The possible work after acquisition includes renovation, repositioning, re-tenanting, and ground-up development. Buildings bring a different set of practical constraints from packaging factories, but ownership still involves deciding what can usefully change.
In August 2025, a 22-unit residential walkup at 567 West 125th Street in Harlem was sold for $7.3 million to Yuco Management through its purchasing entity. Buaron was the signatory for First Atlantic’s selling entity. The transaction closed on August 4. It is a recent, concrete appearance of his name in the New York property record.
His professional connections also extend beyond transactions. He joined Golfsmith’s board in October 2002. The Harvard Business School Club of New York’s 2018 newsletter thanked him for board service dating from 2010. Such roles place the investment career alongside governance and the business school community that formed part of his education.
Return, finally, to the cup. It makes a modest demand on the person holding it. The business behind it makes a much larger demand on those responsible for its future. Buaron’s career has occupied that distance between a familiar product and the organization required to make it. The question he put into print in 1981 remains an apt companion: how much of the way a business competes is simply a habit waiting to be examined?