A startup can have a promising product, committed investors and a perfectly respectable reason to need more money. The troublesome part is the calendar. Product development takes longer than expected. A customer delays a decision. The next investment round remains a meeting rather than a deposit. Rob Pomeroy spent much of his working life in the space between those events, supplying loans to companies that had ambitions well ahead of their cash receipts.
It is an unusual place to make a career. The borrower wants room to grow; the lender wants its money back. Both can agree that the company has a future and still disagree about how much that future should cost. Pomeroy helped build businesses around that negotiation before co-founding Horizon’s investment adviser with Gerald A. Michaud in 2003. He then led Horizon through its public listing and two decades of venture lending.
His own calendar has moved on. Pomeroy retired as Horizon’s chief executive on June 5, 2025, initially retaining the chairmanship. On April 14, 2026, he resigned from the board when Horizon completed its merger with Monroe Capital Corporation. The company continued. The founder’s executive and board chapters had reached their closing dates.
A new firm, an old profession
By the time Pomeroy started Horizon, he had already worked at Crocker Bank and held senior positions at Financing for Science International, Transamerica Business Credit and GATX Ventures. At Transamerica, he co-founded and ran its technology finance business. At GATX Ventures, he served as president. His professional biography records more than 40 years in lending and leasing, including more than 20 in venture lending.
That sequence matters. Pomeroy brought the habits of established financing businesses into a market occupied by young companies. He had experience building lending operations inside larger organizations before building one with his own co-founder. Horizon was a new name attached to work its founders already understood.
He earned both a bachelor’s degree and an MBA at the University of California, Berkeley. An alumni note, published in 2005 under the MBA class of 1974, catches him near Horizon’s beginning. The firm had received funding, and he had a number to report: “We have committed over $50 million of the $300 million fund so far.”
The same note briefly lets the household into the balance sheet. Pomeroy wrote that he and his wife, Sue, had enjoyed life in New England for 19 years, while their daughters had returned to California. Visits followed. He signed off with “Go Bears!” Even a venture lender could spare a line for loyalties that required no underwriting.
Committed from a $300 million fund, in Pomeroy’s own account of Horizon’s beginnings.
What the borrower is buying
Horizon’s predecessor was formed in May 2003 and began originating loans and investments in April 2004. Its business placed it alongside venture investors, financing companies whose development plans needed more capital. Equity investors supplied money in exchange for ownership. Horizon supplied loans, with repayment obligations, interest and negotiated terms.
For a founder, another equity round can mean giving away another portion of the company. Debt offers another route to funding, though it brings its own bill and its own constraints. A loan can help a company reach a milestone before raising more equity. Reaching that milestone may improve its bargaining position. Missing it leaves the repayment obligation rather less interested in the explanation.
In Horizon’s lending model, an equity investment typically precedes the loan. The lender examines the company’s value and financing support, and the debt ordinarily has priority over equity. Loans can also come with warrants, giving the lender rights to purchase shares. Horizon therefore sought recurring income from lending while retaining a route to participate in a borrower’s rising equity value.
Pomeroy’s place in this arrangement required attention to two audiences. A founder could reasonably celebrate having enough money to keep building. Horizon’s investors needed the lending to produce returns. A loan that delighted the borrower and disappointed the lender would hardly make a repeatable business.
When the lender went public
In October 2010, Horizon priced its initial public offering at $16 a share. The offering included 6.25 million shares, some newly issued by the company and some sold by an existing shareholder. Its stock began trading on Nasdaq that month under the symbol HRZN. A financing business serving developing companies now had a public market audience of its own.
The structure gave investors exposure to lending through a business development company. It also made Pomeroy’s work more visible. Loans to private companies had to be explained through the reporting and governance of a listed investment company. The transactions remained individual negotiations; the results became a portfolio that shareholders could examine.
His responsibilities extended well beyond deciding whether to make a loan. They included credit oversight, strategic planning, fundraising, investor relations and corporate governance, alongside the employment decisions that come with running an organization. The product might be money, but the business still needed people to find borrowers, assess them, write agreements and follow what happened afterward.
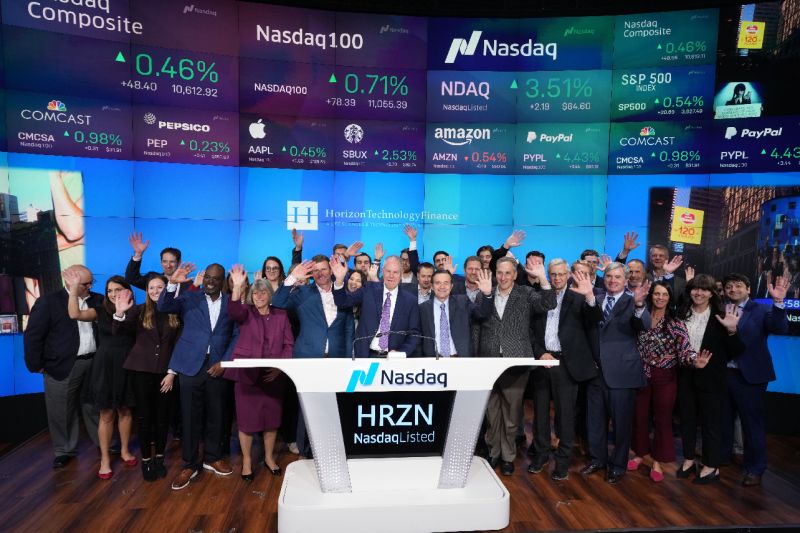
In November 2022, Horizon marked the twelfth anniversary of its listing with a closing bell celebration at Nasdaq’s Times Square MarketSite. Pomeroy was named to lead the ceremony, joined by directors, leadership and employees of the adviser. By that point, Horizon reported investing more than $2 billion in venture-backed companies since its IPO. A lending portfolio had become large enough to merit a moment under the electronic signage.
The less photogenic part of lending
Celebrations have a useful habit of occurring at a convenient hour. Credit problems are less considerate. Venture lending depends on companies continuing to make progress, obtain financing or arrange transactions that allow obligations to be met. The possibility of a good product does not remove the possibility of a bad loan.
Pomeroy addressed that problem in a 2020 earnings call through what he called a “three-legged stool” approach. The legs were company management, equity investors and the lender. Management needed realistic plans and control over spending. Investors needed to be willing and able to supply further capital. Horizon could work with borrowers through measures such as payment deferrals, covenant relief or additional lending.
The image is domestic enough to be memorable. Remove a leg and the furniture becomes an experiment. In financing terms, a lender acting alone cannot guarantee that a company will keep operating successfully. The cooperation of the people running the business and those backing it financially matters too.
That approach also makes the relationship less tidy than the moment a loan is announced. Underwriting continues to have consequences after the agreement is signed. A borrower’s circumstances can change; the lender has to decide what response best protects its position. The essential question becomes whether further support gives the business a credible route forward.
“We are blowing and going .... and growing.”Rob Pomeroy, sharing a Horizon hiring post on LinkedIn
Competition, with room at the table
In 2021, an analyst asked Pomeroy whether the abundance of venture capital made debt less compelling. His answer acknowledged that equity was competing for business. Investors were raising large funds and committing more capital. He nevertheless saw demand for debt alongside it, because the cost of issuing more ownership could make a loan attractive to companies and existing shareholders.
The answer allowed both conditions to exist at once. A busy equity market could produce more competition and more opportunities. A borrower with options might still choose debt. Pomeroy’s argument depended on where a loan fitted into a particular company’s financing, rather than on treating every other source of money as an enemy.
Later that year, another analyst asked about Horizon’s work with Trinity Capital on a $40 million venture loan to Nexii. Pomeroy described other lenders as possible competitors and partners. He put the customer’s transaction at the center of the decision. Cooperation was available when it helped assemble the financing.
His public recruiting language was considerably less formal. Sharing a Horizon hiring post, he described a team that was growing with a cheerful burst of motion. There is a useful glimpse of the operator there: the lender explaining capital structures also needed colleagues to do the work. Portfolio growth had a staffing requirement.
The handoff, in two stages
In July 2023, Monroe Capital completed its acquisition of Horizon Technology Finance Management, the adviser. Pomeroy welcomed access to Monroe’s resources and expertise as a means of expanding financing capacity. The management team and investment professionals continued in their roles. The business he had co-founded was operating inside a broader asset management organization.
Two years later, Horizon announced a planned succession. Michael P. Balkin, already an independent director since June 2023, would take over as CEO. Pomeroy endorsed his investment and portfolio management experience, saying “we are excited to work with him.” Michaud also retired as president, with continued involvement through the end of 2025. The founding partnership was stepping back from executive responsibility together.
Pomeroy’s board service continued until the April 2026 merger closing. Horizon survived the combination with Monroe Capital Corporation, while several directors, including Pomeroy, resigned. The adviser acquisition, CEO succession and public company merger were separate events. Taken together, they changed both the ownership context of the business and the founder’s role in it.
For much of his career, Pomeroy worked on a particular use of time: financing enough of it for a developing company to reach the next decision. His own Horizon tenure shows another use. A firm starts making loans, gains public shareholders, grows a portfolio, acquires a new owner for its adviser and eventually changes leaders. The founder leaves the board. The business has another calendar to keep.