A startup can have a persuasive future and an inconvenient present. The product needs work. The next financing round takes time. Equipment must be paid for before it produces anything useful. Jim Labe has spent his career in that interval, helping venture-backed businesses borrow against a future that remains, by definition, unfinished. The wager is practical and rather less glamorous than the pitch deck: can the company reach its next milestone before the money runs out?
Labe is co-chief executive and co-founder of TriplePoint Capital, based in Menlo Park. He also chairs and runs TriplePoint Venture Growth BDC Corp., the publicly traded business development company associated with the platform. Those titles place him beside two groups whose clocks run differently. Entrepreneurs want room to build. Investors want evidence that their capital will return. A lender has to take both calendars seriously.
His story begins before the current vocabulary of startup financing became commonplace. It passes through the expansion and collapse of Comdisco, a new company launched with $310 million in institutional financing, and a public-market vehicle that put the business under quarterly scrutiny. There is plenty of ambition here. There is also a repayment schedule. Silicon Valley has always been better at celebrating the former.
Before the software, there was the equipment
In the early 1980s, Labe worked at Equitec, where he helped develop venture leasing and lending. The starting point was equipment finance for companies backed by venture investors. A young business needed the tools of production, but it might have little of the operating history a conventional lender expected. Venture backing introduced another part of the picture: investors willing to support an enterprise through its early development.
The approach combined a familiar object, a lease, with an unfamiliar borrower. Equitec provided warrant-based leases to venture-backed companies. A warrant gives its holder the right to buy shares on specified terms. That structure allowed the financing relationship to include possible participation in a company's upside, alongside the obligation to make payments. The startup's uncertain future was being considered in the design of the financing itself.
For Labe, this became a field to build a career in. Equipment finance might sound like the understudy in a technology story. Yet a company can hardly perform without the machinery that makes its work possible. The less photogenic parts of a business have a habit of sending very punctual invoices.
In 1987, he founded Comdisco Ventures, the venture division of Comdisco. He moved from developing a financing product to running an organization devoted to it. The distinction matters. A useful idea still needs people who can assess borrowers, negotiate agreements, monitor loans and work with investors. Labe's career was becoming a sustained attempt to make that work repeatable.
The chapter that did not end neatly
Comdisco Ventures gave Labe years of experience and scale. Across his tenure, its lease and loan transactions exceeded $3 billion. But the company’s history also supplies a necessary complication to a tidy founder biography. Comdisco and its venture business fell apart in 2001 after the Internet bubble. The earlier growth belongs in the story; so does the ending.
By July 2006, Labe was discussing his next venture in a market where startup lending was making a comeback. He said TriplePoint would avoid Comdisco's mistakes and described a large ambition: “We plan to drive this into an extremely large, full-service financial company.” It was a promise made with a difficult predecessor in view. Experience can mean knowing what has worked. It can also mean remembering how an enterprise came undone.
That distinction gives his second company more texture. A lender serving startups participates in the same market cycles as its customers. Enthusiasm can create demand for financing, and a downturn can expose assumptions that looked sensible during expansion. Building another institution after that experience meant returning to a business whose attractions and dangers he had already encountered.
The question beneath the comeback was whether a financing company could offer entrepreneurs continuity while preserving its own. A founder can extend a company's runway with debt, but the lender must also have the means to keep lending. The balance sheet behind the loan is part of the product, even when it never appears in the sales pitch.
A second company, with a familiar partner
Labe co-founded TriplePoint Capital with Sajal Srivastava in 2005. Its formal business launch followed on February 1, 2006, supported by $310 million in institutional financing. The two dates describe different moments: establishing the company and announcing its launch. The sequence shows the preparation behind what otherwise looks like a single entrepreneurial event.
Srivastava had worked with Labe at Comdisco Ventures, leading investment and credit analysis work. Their partnership carried experience from the earlier business into the new one. Today, they share the co-chief executive title at TriplePoint Capital. A financing platform depends on the relationship between finding opportunities and examining them closely; their professional connection stretches back to the organization where they practiced that work together.
The launch proposition was financing across a venture-backed company's development. TriplePoint offered equipment leases and loans, growth capital and expansion financing, including for companies at early stages and after an initial public offering. Labe emphasized a permanent balance sheet and the ability to sustain customer relationships over time. The company wanted to remain useful as the borrower changed.
His stated objective had a pleasingly economical rhythm: help companies “move from raising money to making money.” Raising capital is a milestone that can easily become a profession. The business still has to do something with it. Labe's formulation brought the attention back to what financing was supposed to enable.
“Move from raising money to making money.”
Jim Labe, at TriplePoint’s 2006 launch
Two kinds of money, two kinds of obligation
The financing problem in Labe's career is easy to describe and harder to solve. Selling equity gives investors an ownership stake. Borrowing creates an obligation to repay. Venture debt can complement equity, providing additional capital while limiting the need to sell more ownership at that moment. It also brings payments, interest and contractual conditions into the company's future.
A founder weighing those choices has to think beyond the size of the check. How much progress will the money fund? When will the next round be needed? What happens if the milestone takes longer? The attractiveness of borrowing depends on those answers. A longer runway is useful when it leads somewhere the company can reach.
The financing mix also explains why relationships appear so often around TriplePoint. A venture investor, an entrepreneur and a lender each see the company from a different position. The investor has committed equity. The entrepreneur must turn resources into a working business. The lender needs a credible route to repayment. Agreement about the opportunity does not make those interests identical.
Labe's work sits among those interests. His contribution to the industry includes teaching other practitioners and speaking about venture finance at Harvard Business School and the University of Chicago. An emerging category needs people who can explain it as well as people who can fund it. Explaining the instrument helps establish what customers should expect from it.
When the lender has shareholders, too
In March 2014, TriplePoint Venture Growth entered public markets. Its initial offering was priced at $15 a share, with approximately $125 million in gross proceeds before the additional underwriter option and concurrent private placement. The vehicle was formed to expand the venture-growth-stage segment of TriplePoint Capital's business.
This added another audience to Labe's work. Public shareholders could examine a lending portfolio through reported earnings, asset values and distributions. The capital needs of privately held companies now met the disclosure calendar of a listed company. A business built around relationships had to present its performance in numbers that strangers could inspect.
TriplePoint Capital and TriplePoint Venture Growth have distinct identities in that arrangement. Labe is co-CEO of the former and chairman and CEO of the latter. The wider platform serves companies across development stages; the listed vehicle focuses primarily on venture-growth-stage companies. Keeping that distinction clear makes his responsibilities easier to understand.
The conversation after the banking crisis
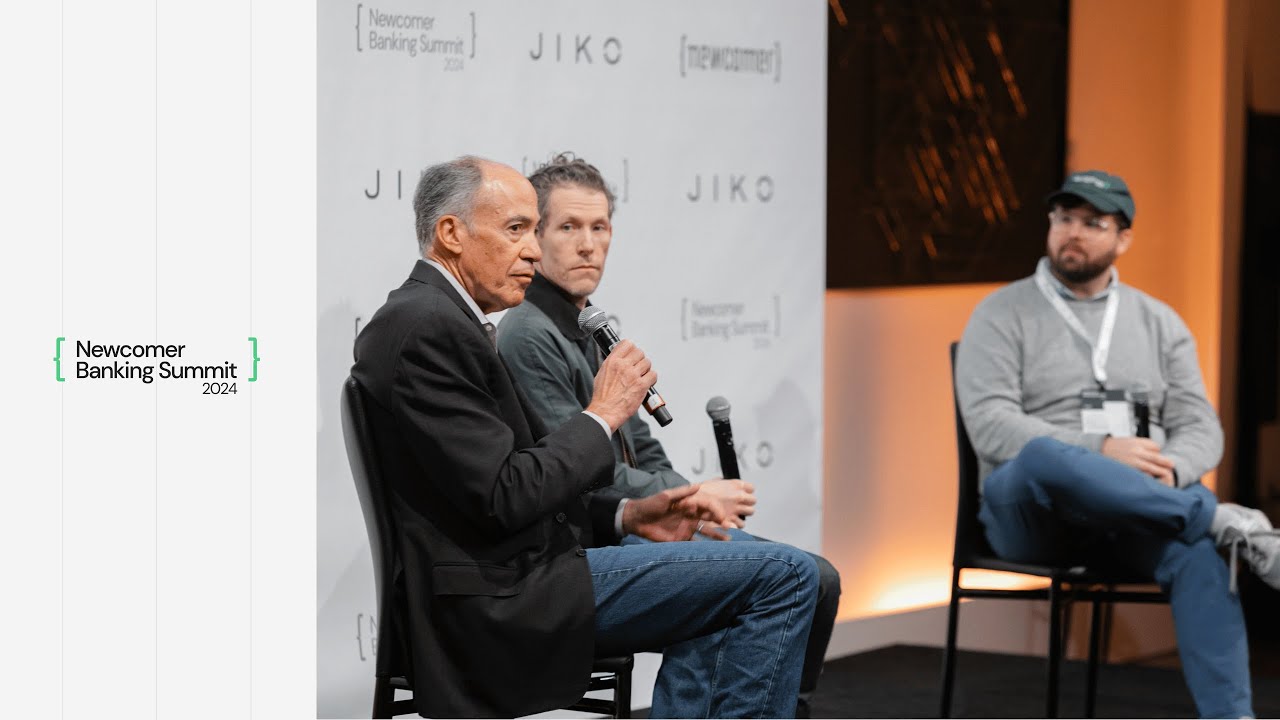
At the Newcomer Banking Summit in San Francisco on March 14, 2024, Labe joined Lightspeed's Justin Overdorff for a discussion about raising debt and equity after the banking crisis. The setting brought him into a wider argument about who would serve startups and how. Banks and financial technology companies were competing for relationships in a market that had been abruptly rearranged.
Labe expected more separation between lending and banking, creating opportunities for his firm. He saw fintech activity picking up while describing “retrenchment on the debt side.” Those observations could coexist: interest in building companies might recover while lenders remained cautious. A promising sector and an available loan are different developments.
The panel offers a useful glimpse of his public role. Decades after the equipment-finance beginnings, he was still discussing where borrowed capital fit in the venture economy. The institutions and technologies had changed. The underlying negotiation remained familiar: businesses seeking room to grow, financiers deciding how much uncertainty they could carry.
AI arrives; the calendar remains
In August 2026, Labe described TPVG's continued diversification into venture-growth-stage companies across AI and other investment sectors. The second-quarter results recorded $47.8 million of debt funding to ten portfolio companies. They also showed net investment income of $0.21 a share, down from $0.28 a year earlier. Expansion and pressure were visible in the same report.
TPVG realized a $12.8 million gain from a secondary sale of Revolut equity during the quarter. That result illustrates another part of venture finance: debt, warrants and direct equity can produce different outcomes within one portfolio. A technology company's growth can matter to a lender beyond its scheduled payments.
Away from financing, Labe's civic activities have included Stanford's Athletic Advisory Board, youth tennis organizations and volunteering as a camp counselor for underserved city children. He holds a bachelor's degree from Middlebury and an executive MBA from Chicago. These details add an educational and community life alongside the sequence of financial institutions.
His career has followed venture-backed companies from equipment needs into a market now occupied by AI businesses. Through that change, he has kept returning to the interval between having an idea and having the means to sustain it. Borrowed money can make the interval longer. The company must still use the time. For a financier, that is a career's worth of work; for a founder, it is tomorrow morning.