The buyer has found the business. The seller is willing to talk. A letter of intent has been signed. It ought to be the moment the story becomes simple. Instead, the buyer acquires a second occupation: explaining the transaction to people whose money is needed to complete it. Raises.com has made that awkward interval its business. The glamour belongs to the acquisition announcement. The work belongs to the file nobody photographs.
- For buyers of operating businesses and real estate.
- Builds structures, documents, models, and capital introductions.
- Flat advisory fees; the buyer remains the principal.
- Flagship’s published three-month base cost: $7,840 before extras.
A buyer with a clock running
Consider Cody Sechelski, a Texas construction operator. In a company-published interview, he describes discovering Raises.com through YouTube and booking a call in October 2025. His inaugural HVAC acquisition was announced in July 2026. Between those dates came the less photogenic business of making financial records agree and persuading capital providers to commit.
Sechelski’s account includes funding firms that changed their requirements and ultimately declined. The winning lender’s projected three-week close became two months. Meanwhile, a seller had to keep waiting. Raises.com identifies Tre Brown as the executive who handled the deal; its announcement describes institutional senior credit and structured seller financing, with minimal sponsor cash equity.
The lesson is smaller, and more useful, than a claim that anyone can buy anything. A financing conversation can advance for months without producing money. A buyer needs alternatives, coherent records, and a structure the seller will accept. The initial optimism changes when the calendar starts answering back.
The paperwork has a job
Raises.com organizes its work into four stages: structure, package, connect, close. It helps prepare the fund or acquisition vehicle, then the documents and financial materials, then introductions to capital providers. Its customers include independent sponsors, search funds, real estate syndicators, and acquisition entrepreneurs. Some arrive with a signed deal. Others need help becoming ready to pursue one.
The inventory sounds dry: private placement memorandum, subscription agreement, operating agreement, pitch deck, financial model, data room. Yet each answers a different question. What is the investor buying? What are the obligations? Where do the projected returns come from? What evidence can someone inspect? A handsome presentation cannot answer all four by looking handsome.
An essential boundary sits beneath the pitch. Raises.com says it is a consultancy and advisory firm, not a registered broker-dealer, and does not sell securities. The buyer remains the principal. That makes the product a combination of preparation, tools, and relationships. It cannot make an investor like a transaction merely because the documents have arrived in the correct order.
“You stay the principal.”Raises.com’s description of the engagement
What the meter reads
The published Flagship plan starts at $3,920 for the first month and continues at $1,960 a month, with a three-month commitment. That produces a $7,840 base bill. The plan lists one active raise, two financial proformas a month, matched debt and equity introductions, legal documents, and limited individual advisory.
Calculated from published pricing. Optional services and entity fees extra.
Institutional starts at $4,998, followed by $2,499 monthly, also with a three-month commitment on the dedicated pricing page. It adds a dedicated advisory team, custom modeling, and expanded support. Enterprise is $12,000 monthly, with required advertising spend of $5,000 to $25,000 monthly. Optional platform access is listed at $149 monthly; entity formation at $800 each.
Those are prices for service, not the purchase price of a company or the cost of borrowing. Debt interest, seller terms, and deal expenses belong to another calculation. Flat fees make the advisory budget easier to inspect. They also mean the buyer can pay for work while the proposed acquisition remains uncertain.
A programmer’s answer to a banker’s problem
Founder and CEO Natu Myers studied computer science and played varsity football at Queen’s University, according to his founder interview. He says he left his first coding job after roughly six months and negotiated the Raises.com domain purchase in summer 2021. The firm dates its founding to 2019. The name came after the work had begun.
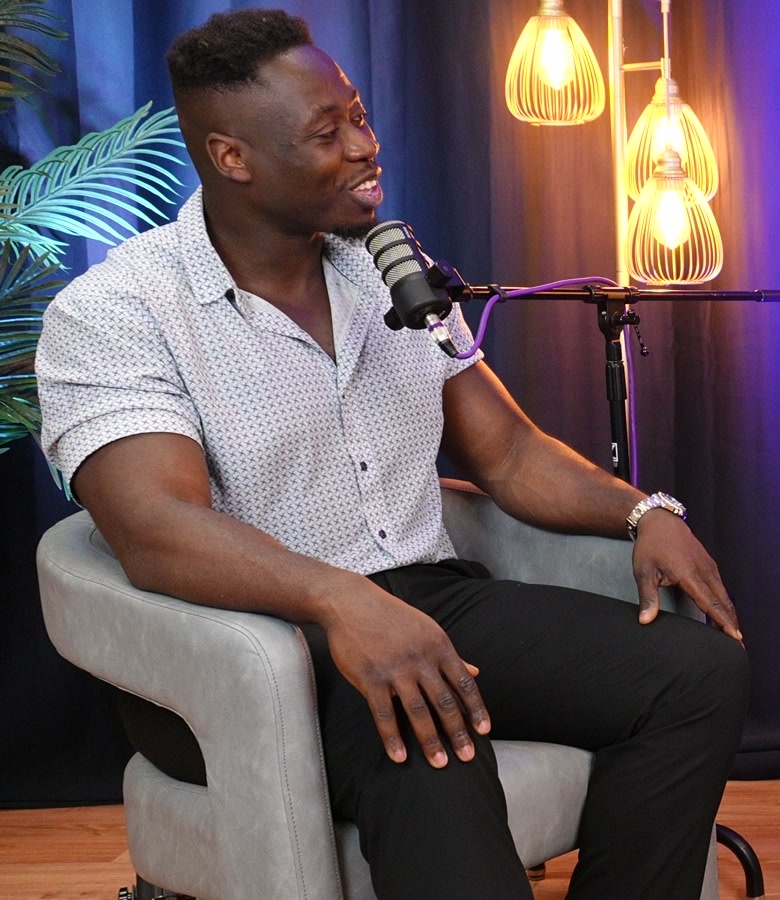
His account suggests an attraction to systems: a way of doing the work that another person can repeat. The company’s published principles make that ambition explicit. Routine scheduling and records are automated; structuring and introductions receive human attention. The principles also borrow their moral vocabulary from Biblical passages. Finance has many manifestos. This one comes with chapter and verse.
The firm says it writes institutional introductions for a particular recipient and mandate, and records an investor’s criteria after a refusal. This is a revealing detail. A rejection can improve the next match if someone bothers to remember its reason. The useful asset is a record of who will consider what, under which conditions.
The useful thing to steal
Raises.com occupies the space between acquisition education, investor software, and separately hired professional advisers. Its differentiation is the combination: materials are prepared alongside structuring advice and capital introductions. Its comparison pages name coaching programs and investor-management platforms as alternatives, although those products address different portions of the task. Buyers should compare the work they need performed, rather than the length of a feature list.
There is also a distribution business. Raises.com identifies Acquire.com as a strategic partner and offers referral and white-label programs. Brokers and advisers can introduce a client or deliver the platform under their own brand. The public referral offer advertises 20 percent of referred revenue. Here, the opportunity is being present when a buyer discovers a financing gap.
The copyable method is straightforward: reconcile the numbers, build an inspectable package, and approach capital sources whose requirements fit the transaction. Keep a record of objections. Keep alternatives alive. This fits an active buyer of an operating business or real estate who will supply accurate records and make decisions. Raises.com explicitly excludes pre-revenue startups. A passive customer expecting fees to purchase certainty will find acquisition work a particularly expensive teacher.
Follow the deal
Explore Raises.com, its plans, client stories, and acquisition guides.
Follow on LinkedIn, X, Facebook, or YouTube.
Watch Cody Sechelski’s acquisition interview and Natu Myers’s founder conversation. Read the Texas HVAC acquisition announcement.