Your banking app gets the applause. Somewhere behind its tidy buttons, less photogenic software has to keep accounts straight, process payments and make sure a card actually works. Pismo built its business in that back room. In June 2023, Visa agreed to buy the company for $1 billion in cash. The transaction closed in January 2024. That is a considerable price for a business most cardholders will never knowingly encounter.
The attraction becomes clearer when you consider what Visa acquired: cloud-based core banking and issuer processing in one platform. A financial institution can use Pismo to run the records behind an account and the processing behind its cards. Visa also pointed to connectivity with payment systems such as Brazil’s Pix. The acquisition extended the buyer’s capabilities into more of the machinery its banking customers need.
Pismo occupies an unusually useful position between the institution with the customer relationship and the infrastructure that makes the product function. Its buyers include banks, fintechs and retailers. They bring the brand and the business proposition. Pismo supplies software through which their teams can build and operate financial products. The consumer may never learn its name. For this particular business, that arrangement works perfectly well.
Announced cash acquisition price.
Completed 16 January 2024.
Four founders, one chance to start over
Founded in São Paulo in 2016, Pismo brought together Ricardo Josua, Daniela Binatti, Juliana Binatti and Marcelo Parise. Their responsibilities covered business leadership, technology, product and engineering. Josua and Daniela had experience at Brazilian payments company Conductor. They arrived with knowledge of the industry they wanted to rebuild, including the unglamorous parts that a polished demonstration can conceal.
Daniela’s account of a 2015 trip to Silicon Valley offers a concrete glimpse of the thinking behind the company. She saw startups using Amazon Web Services’ managed services to build their businesses. The opportunity was to bring that approach to financial infrastructure. Starting again gave the team room to choose its technology without first carrying an inherited platform across to a new environment.
By October 2021, the company was ready to change how it grew. Josua described a business that had relied exclusively on referrals and kept a low public profile. A $108 million Series B, led by SoftBank Latin America Fund, Amazon and Accel, financed international expansion and further development. The shift was from an introduction-led business toward a deliberate global sales effort.
The company’s people policies reflect its ambitions to recruit beyond one office. Its careers materials describe remote work, exchange programmes, employee resource groups and learning activities around inclusion and wellbeing. These are stated practices, rather than a verdict on every employee’s experience. In a business selling complex infrastructure, building a team that can understand different markets is also a practical product concern.
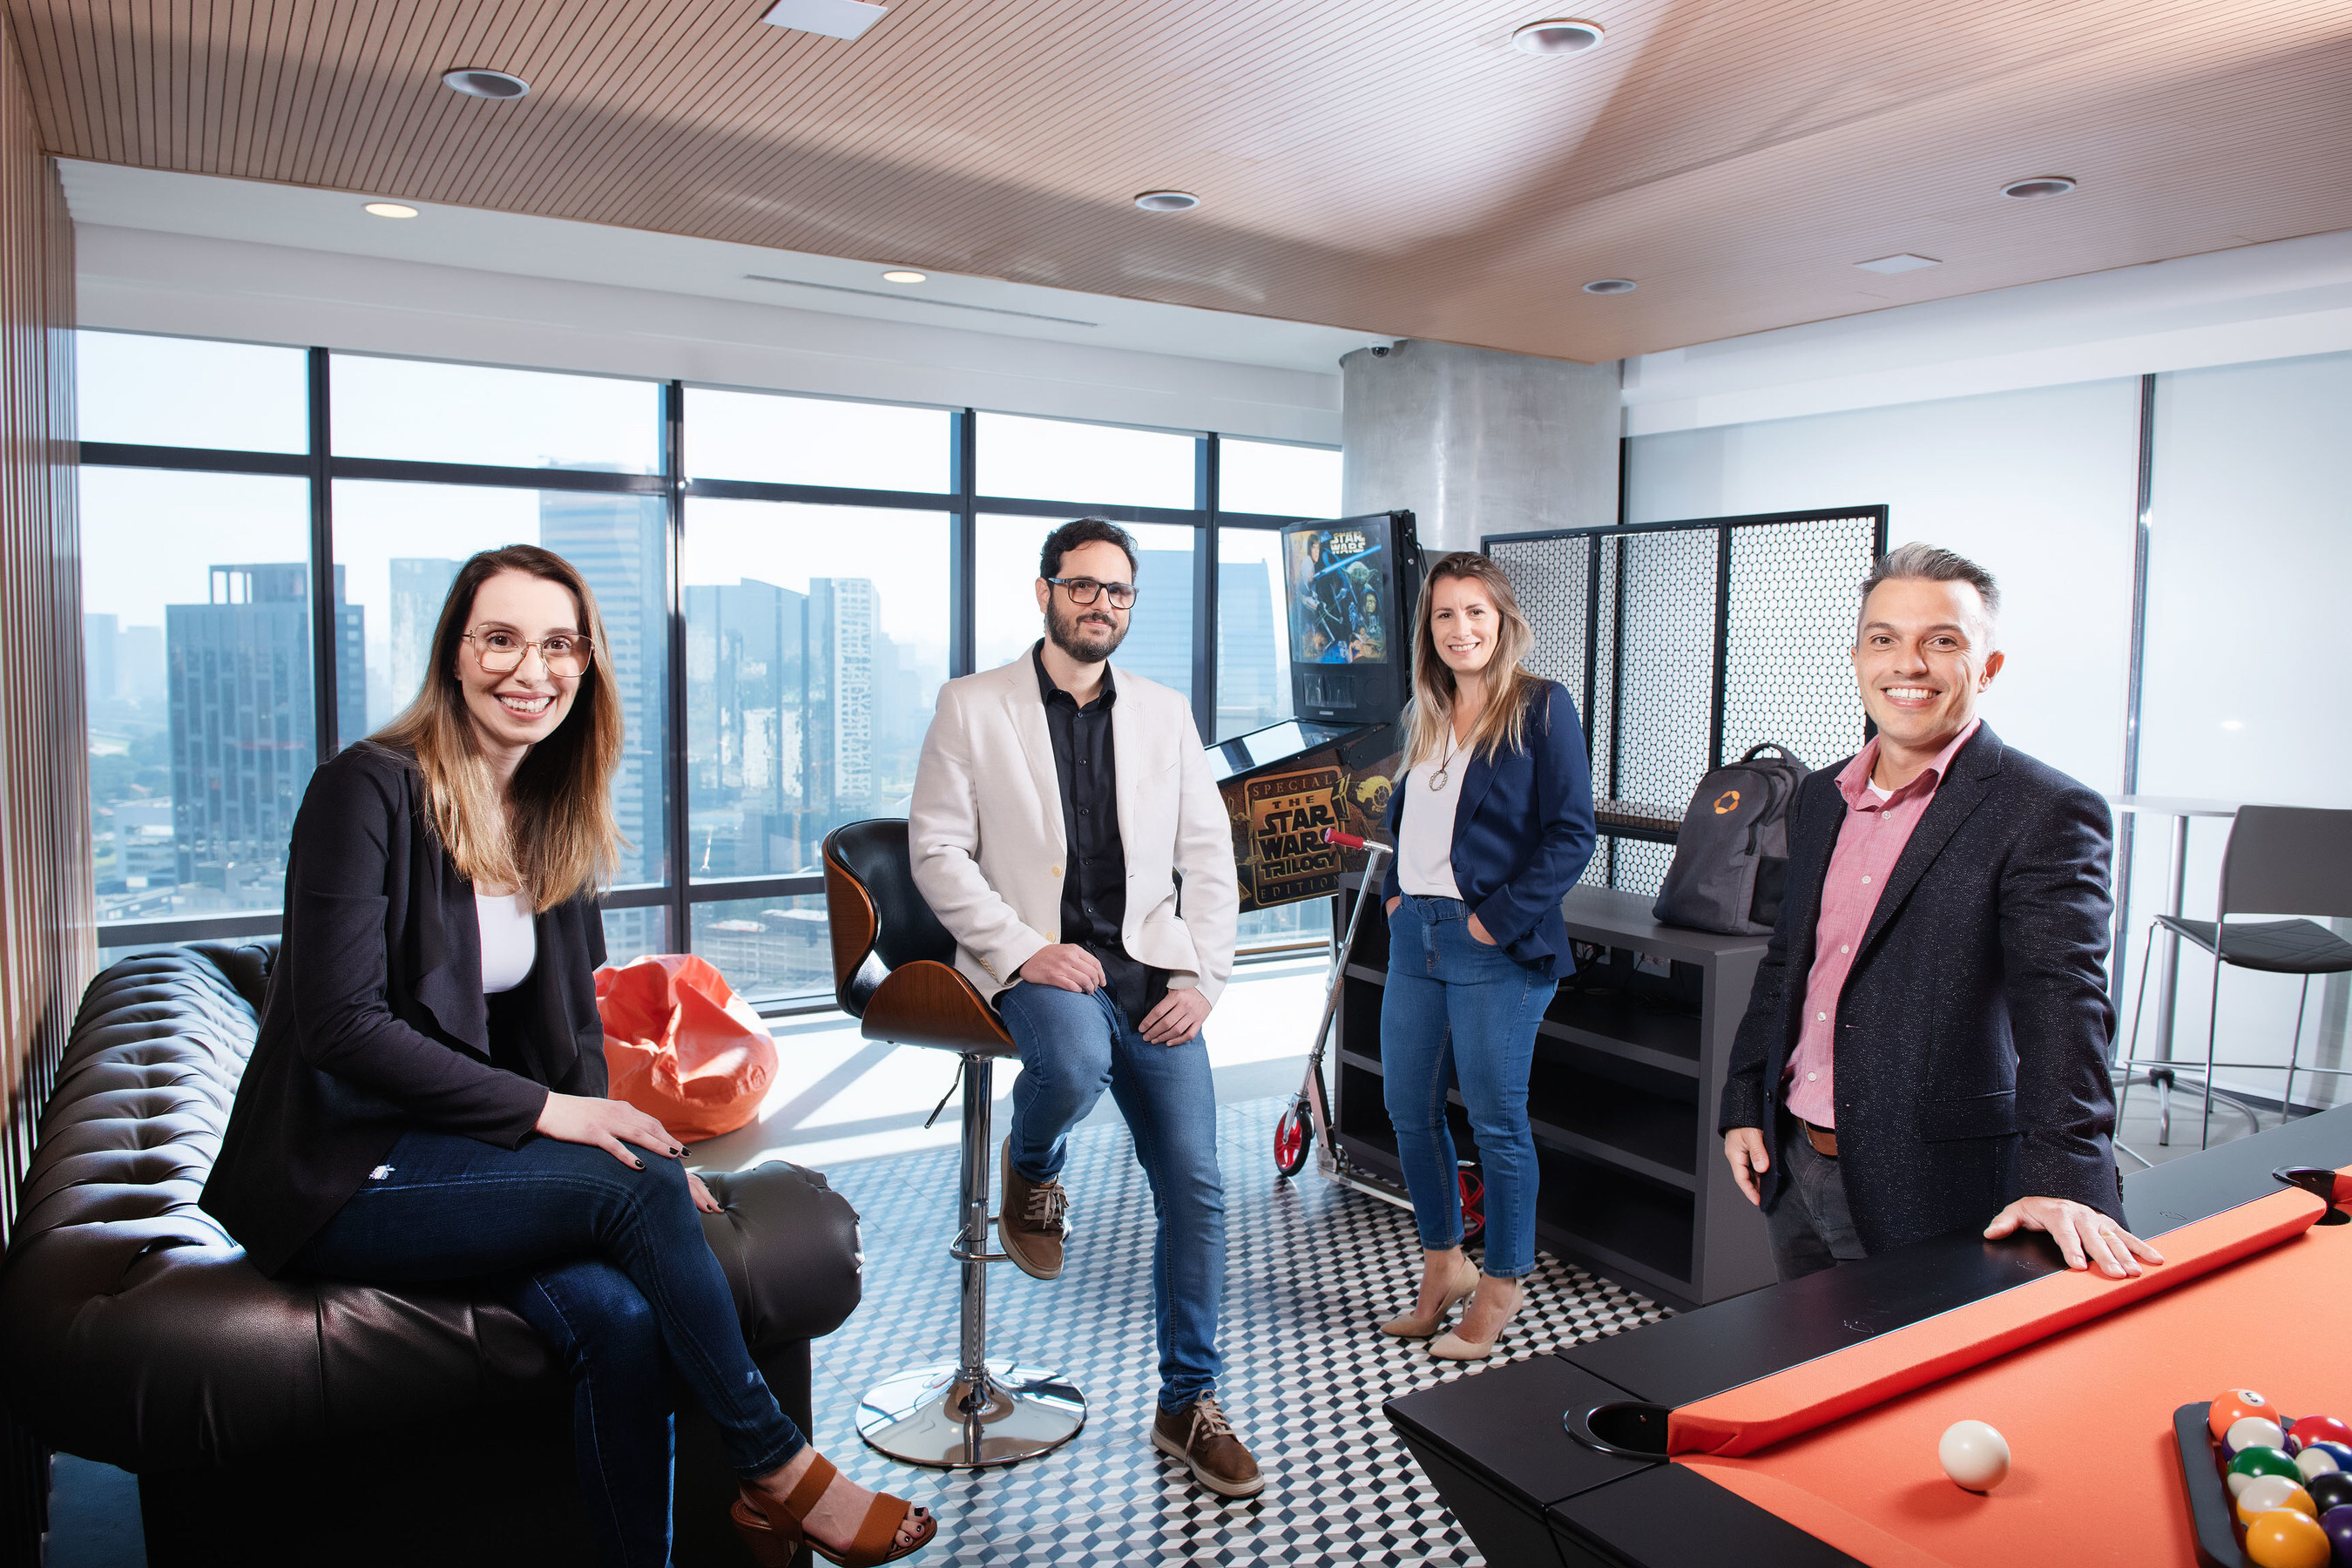
Pismo’s founding team in its 2021 publicity photograph. Photo: Pismo.
The account and the card share a workshop
Pismo’s core banking product is sold as cloud-native software as a service. Its developer documentation separates the foundational work of accounts and ledgers from transaction banking’s more involved payment and cash-management needs. That distinction matters: the software required by a consumer checking account is related to, but does not exhaust, what a corporate treasury operation needs.
Card issuing adds credit, debit and prepaid programmes, including physical and virtual cards. Pismo advertises support for Visa, Mastercard and private-label programmes. Visa ownership therefore should not be read as a claim that the product only processes Visa cards. A customer choosing the platform is buying operational capabilities for its programme, with network requirements still part of the implementation.
The catalogue extends to digital wallets, lending and seller management. Lending functions include booking, disbursement and repayments. For a marketplace, seller management can divide a payment between sellers and set settlement conditions. Those features address the less glamorous aftermath of clicking “buy”: who gets paid, how much they receive and when the money should move.
The commercial model is business-to-business infrastructure. Teams integrate Pismo’s APIs into their own applications, while the platform supplies the processing foundation. A buyer should evaluate that as an operating commitment, including integration and migration work. The practical budget question is the total cost of getting a financial product into reliable service, rather than simply the price of access to software.
A simplified view of the relationships behind a financial product.
Eight months is a case study, not a stopwatch
BTG Pactual offers a concrete example of the platform’s appeal. The Brazilian investment bank used Pismo for core banking, card issuing and payment processing when building its digital retail bank. Visa’s February 2025 investor presentation put development time at eight months, with the business launching in 2021. That is evidence of a particular project delivered; it is not a universal timetable for replacing a bank’s systems.
Cora illustrates a different audience. Its digital bank serves Brazilian small and medium-sized businesses with accounts, cards and billing tools. Pismo’s account of the relationship describes its AWS-hosted platform connecting Cora’s core systems with Visa and card embossers. The common need across BTG and Cora is operational infrastructure. Their customer propositions remain their own.
The work also reaches corporate banking. Citi selected Pismo to enhance demand deposit account services for Treasury and Trade Solutions clients, announcing the relationship in 2023. That choice puts Pismo in conversations about corporate money management as well as consumer-facing digital banks. A useful way to read the customer list is by workload: retail banking, business accounts, corporate accounts and card programmes.
“We have worked almost in stealth mode so far, selling exclusively through referrals.”Ricardo Josua · October 2021
What the test actually measured
At its 2025 investor day, Visa said Pismo had created approximately 130 million accounts by 2024 and was processing nearly 12 billion API calls a month on average. Accounts created are not the same as active customers. API calls are software requests, not a count of purchases. Those distinctions keep an impressive operating footprint from turning into an imaginary consumer audience.
A separate Pismo announcement in August 2024 described a proof of concept with an unnamed Tier 1 bank. The company reported 25,000 transactions per second in a production-ready test environment. About 100 million accounts had been provisioned in the database, with 200,000 selected for the test. Pismo said the testing framework capped the measured throughput.
The useful lesson is to read the conditions alongside the number. A benchmark establishes what happened under a defined workload. It does not promise that every customer configuration, integration or traffic pattern will produce the same result. A bank evaluating the platform should bring its own transaction mix to the conversation. The graph belongs beside the implementation plan, not in place of it.
Pismo-reported proof of concept. 200,000 selected accounts; production-ready environment. Not a universal throughput guarantee.
The first thing to inspect is the old data
For an existing bank, the difficult question is how to get from here to there. Pismo’s migration guidance starts with understanding the client’s products and preparing its records. Information that looks clean to the sending institution can still fail to align with the receiving system. The initial problem to investigate is therefore often a mismatch in data and meaning, before any argument about raw processing speed.
Pismo describes accepting migration data through files or APIs and returning events for individual migrated records. Clients can use those events to check that what arrived matches what they sent. The company also describes pilots using smaller bank identification number portfolios before larger moves. These are specific practices another technology team can copy: reduce the initial scope, inspect the result and widen the move only when the checks justify it.
That work requires people on both sides. A platform cannot supply the client’s understanding of its own products, fix every historical record by implication or decide which discrepancies are acceptable. Where a bank cannot prepare and validate its data, a phased migration still needs preparation. Breaking a difficult job into pieces makes it more observable; it does not make the underlying obligations disappear.
There is a second boundary worth understanding before buying. Pismo’s banking documentation identifies it as a technology provider and distinguishes its role from licensed banking partners. The company lists relationships with providers including Celcoin and Itaú’s service offering. Software access should therefore be evaluated alongside the banking arrangements needed for the intended product. The useful question is who performs each part of the service.
The competition is bigger than a cloud label
Pismo sits in a crowded banking software market. Alternatives include Mambu, Thought Machine and established core banking suppliers such as Temenos and Finacle. The exact shortlist depends on whether the buyer needs an account system, card processing or a broader replacement. “Cloud-native” alone does little to settle that decision. Buyers still have to compare functional coverage and the work required to adopt it.
Pismo’s distinguishing combination is its banking core and cards capability, supported by a record of serving substantial institutions. A 2025 Celent assessment placed Pismo among its technology standouts for next-generation cores serving small and digital banks and specialty institutions. The same assessment described strengths across several competing products. This is a market with different useful answers, not a contest resolved by one adjective.
Partnerships also define the boundaries of the product. Pismo’s ecosystem covers areas such as identity verification, fraud tools and card production. That allows specialist services to sit around the processing platform. For a buyer, the attraction is choice; the work is making those choices fit together. An integration plan needs to account for the surrounding services as carefully as the central system.
Visa opens doors. Delivery keeps them open.
The expansion became tangible in Thailand in September 2025, when T2P announced prepaid cards on Pismo in under three months. The customer described the project as Pismo’s entry into the Thai market. In October, Zenith Leisure announced a collaboration on a multicurrency Visa prepaid forex card in India, aimed at travellers and other groups managing spending abroad. These are concrete programmes, rather than dots added to an expansion map.
Assurance remains part of the sales argument. In July 2025, Pismo announced SOC 2 Type II compliance for its platform. Such work belongs alongside product development because buyers are entrusting a provider with consequential operations. Pismo’s January 2026 publishing agenda, including a piece on building a bank for 2030 and beyond, shows the company continuing to pitch long-term infrastructure decisions.
The copyable lesson is fairly grounded: start with a workload customers care about, connect it to an observable result and make adoption part of the product. Visa paid for technology with demonstrated uses and room to travel. For the next bank considering Pismo, the decision will be more local: which accounts move first, who checks them and whether the new system makes tomorrow’s change easier.
Inside the machinery
Explore the platform, follow the company, or hear its founders explain the idea.