A friend needed to pay Oracle. In many business stories, that would barely qualify as an event. Software gets bought; invoices get settled; everyone returns to their more interesting troubles. For Ola Oyetayo, the difficulty of getting a payment from an African business to an overseas supplier helped expose a problem large enough to leave a career over.
He had trained as a chartered accountant and worked inside the financial system. He knew the institutions, the vocabulary, the professional habits. Yet here were people running businesses who struggled to do something that ought to have been routine. They could arrange a commercial relationship across a border. Moving the money to honour it was another matter.
Verto, the company he founded with Anthony Oduu, grew from that discrepancy. Its origin includes a poker game, which makes for an agreeable opening anecdote. The more revealing detail comes afterward: an early version of the service ran through a WhatsApp group. Before the platform, there were people who needed currencies and two founders trying to connect them.
A good job, and an awkward question
Oyetayo’s education took him from King’s College in Lagos to Oxford Brookes University in the UK. His finance career included American Express, Barclays and Lloyds Bank. Those are comfortable names to place on a CV. They also gave him a view of financial services from a country where much of the machinery could be taken for granted.
The move into entrepreneurship did not require a conversion to the idea that finance mattered. He already believed that. It required choosing a different vantage point: the business owner waiting to pay, rather than the institution deciding how a payment should proceed.
His first paid work had been mobile-phone telesales, with a monthly pay packet of £500. It is a useful detail in a career often introduced through bank names. Before he was designing a financial service, he had held a job in which someone at the other end of the line could simply decline the proposition.
He has described his Nigerian background as shaping the commercial way he looks at everyday problems. A delayed payment, viewed that way, contains several questions. Who is inconvenienced? What does it cost them? Would they use a service that removed the difficulty? An accountant has reasons to ask for the figures before getting carried away.
The first product fitted inside a group chat
In 2017, Oyetayo and Oduu discussed payment frustrations during poker games. Oyetayo had been exploring remittances; Oduu was pursuing a property-technology venture and preparing for an MBA. The conversation gave their separate experiences a shared direction. They began Verto in 2018.
The WhatsApp beginning deserves a little attention. A group chat is an unusually candid first product. People show up with something they need. Other people may have the matching requirement. The usefulness of the connection becomes apparent without much room for a decorative explanation.
Verto subsequently joined Y Combinator’s winter 2019 batch. The company’s early currency marketplace developed into a platform for business payments and foreign exchange. Oyetayo became CEO; Oduu led technology and product. Their division of labour put commercial experience alongside the task of turning a recurring exchange into working software.
- 2017Poker discussionsA shared payment problem
- 2018Verto beginsAn early WhatsApp exchange group
- 2019Y CombinatorThe winter batch
An invoice has a geography
A business payment is attached to other work. A supplier needs to release goods. A company needs software to keep operating. A finance team needs to know which amount will arrive, in which currency, and when. Each unanswered question spreads beyond the payment itself.
Oyetayo has repeatedly drawn a distinction between this work and sending money to an individual. Verto concentrates on businesses. The customer might be dealing with a foreign supplier, receiving money from an overseas buyer, or managing payments between operations in different countries.
In his explanation, the obstacles include finding enough of the required currency, establishing an exchange rate, and getting the transaction settled. A price on a screen is useful only if there is a practical way to complete the exchange. A payment instruction is useful only if the receiving business gets paid.
- Find the currencyLiquidity: having access to the money a supplier needs.
- Agree the exchangePrice discovery: knowing the rate before committing.
- Complete the paymentSettlement: getting the value to its destination.
His ambition is that international payments should feel as straightforward as placing a WhatsApp call. The comparison gives the customer a recognisable standard. Nobody wants a tutorial in telecommunications before ringing a relative. A business owner would appreciate a similar arrangement with an invoice.
Learning which door to knock on
A background in banking did not make every banking conversation easy. Oyetayo has recalled approaching former employers for an account for his new venture. He expected his network to help. The proposed business involved moving money into African markets, and the reception was considerably less warm than he had anticipated.
That experience helps explain his interest in how risk gets assessed. From one side of the desk, a region can become a broad category. From the other, there is a particular business, with particular customers and documents, trying to carry out a transaction. Verto’s opportunity depends partly on doing the work between those perspectives.
He also acknowledges an early strategic hesitation: whether to concentrate more firmly on emerging markets or spend more effort serving developed-market customers. Looking back in 2024, he wished Verto had embraced its emerging markets heritage earlier. For a founder, that is a fairly expensive form of politeness toward a larger imagined audience.
Choosing a focus makes the product’s obligations clearer. The customer’s difficulty becomes the assignment. It also gives Oyetayo a way to judge an attractive new idea: whether it helps the businesses Verto has decided to serve.
The opportunity principle
Oyetayo connects his leadership approach to being an immigrant in a country that gave him opportunities. He wants other people to receive a chance too. His account of management stresses delegation, ownership and accountability, with room for ideas from people whose experiences differ from his own.
“Being open-minded creates the winning ideas.”
Ola Oyetayo / on building a team
There is a practical test behind that sentiment. When the company crosses markets, no single person carries all the relevant knowledge. Letting colleagues exercise judgment becomes part of running the business. The founder has to make room for information he did not bring into the meeting.
His interest in opportunity also extends to education. He co-founded Iwe-League, a charity supporting secondary schooling for underprivileged children in Nigeria. It is a separate undertaking from Verto, connected by a concern with access: who gets the opening that makes later achievement possible.
A trophy, then back to the bills
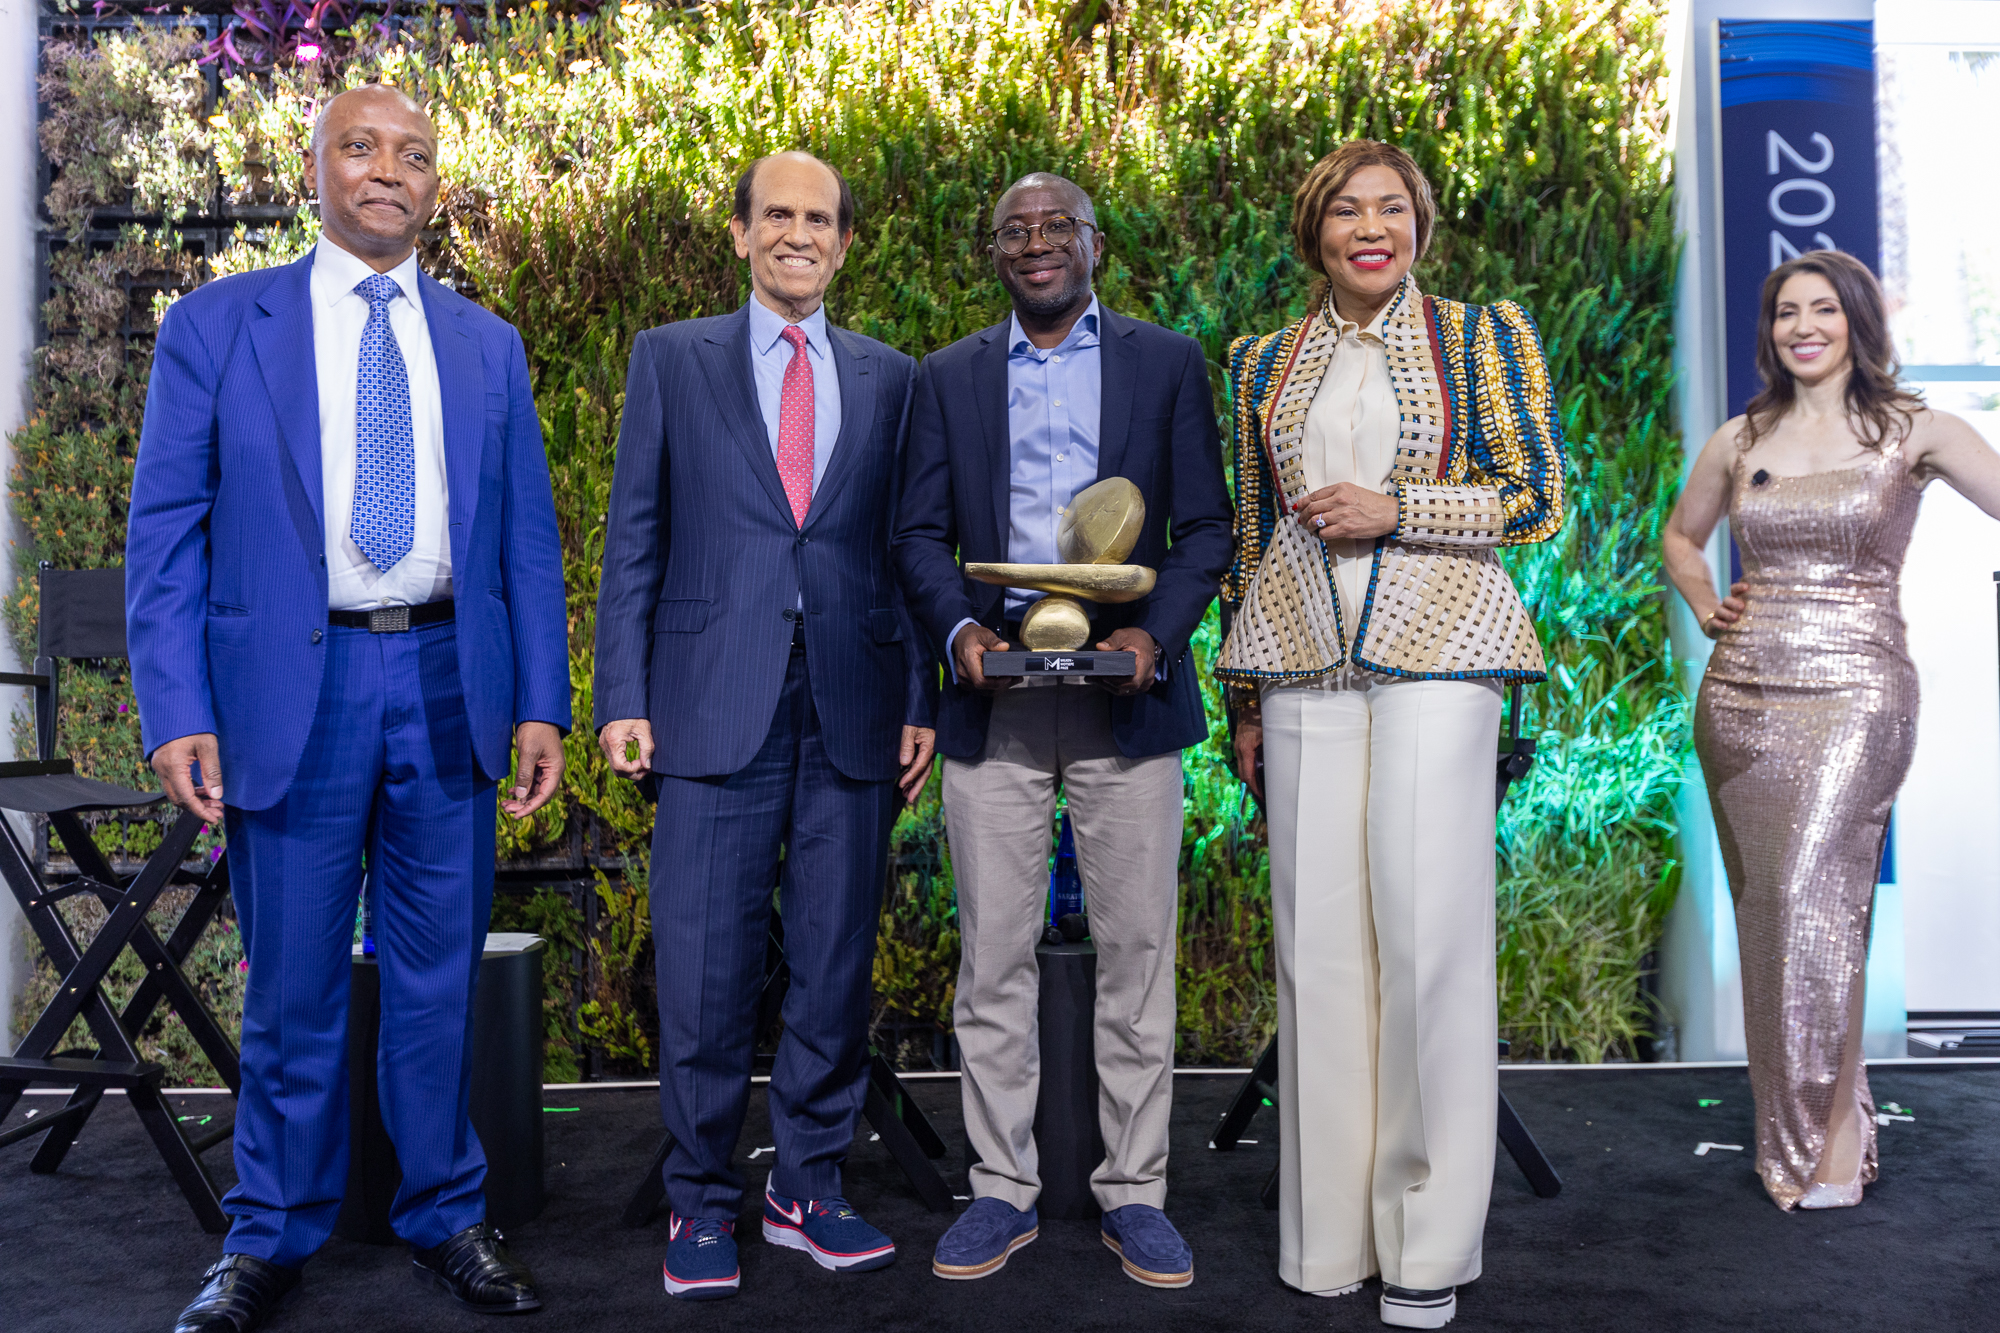
In May 2025, Verto won the $1 million grand prize in the Milken-Motsepe Prize in FinTech. The competition recognised work expanding financial services for small businesses in emerging and frontier markets. At the Los Angeles ceremony, Oyetayo held the award alongside the programme’s founders and organisers.
The work continued into more ordinary corners of business life. In September 2026, Verto announced a multi-currency corporate card with Visa. The proposition addressed international spending from existing currency balances, including the routine purchases that keep a company operating across markets.
For Oyetayo, that extends an earlier concern about African businesses’ limited options for paying online. The subject can sound small beside the language of global trade. Try telling that to a company whose software subscription or supplier payment has failed.
His July 2026 writing also examines the decisions that precede a payment: verifying a business, checking documents, selecting a route and securing approval. He describes Verto using AI in those operations, as well as an internal knowledge tool called Ask Frank. The emphasis is on the administrative work customers experience as waiting.
In the same essay, he reported more than $25 billion in Verto payment volume for 2025. That measures money processed through the service. The figure gives scale to a problem that began, for him, with people he knew trying to pay someone else.
That makes his conversation with Griffin co-founder David Jarvis in 2025 particularly fitting. Two founders working in financial services discussed trust, enterprise sales and the technology behind moving money. Oyetayo’s appreciation for the existing infrastructure came through too: he called Swift “one of the wonders of the modern world.” A founder trying to improve payments can still admire the machinery already carrying them.
Off the clock, still curious
Outside Verto, Oyetayo likes reading, travel and golf. He follows current affairs closely. In a 2023 questionnaire, his tastes ran to nonfiction business books, hip-hop and Succession. Someone interested in both corporate governance and that television programme has ample material for an evening.
He named becoming a father as his personal best achievement. When asked about a philosophy of life, he gave an answer with room for revision: “Be inquisitive, keep an open mind, and always be learning.”
He has described spending time with newspapers and other publications to understand events around the world. The interest reaches beyond the next commercial announcement. For someone whose working day involves different currencies, jurisdictions and trading relationships, curiosity has plenty of places to go. The golf course offers a different set of uncertainties, with the advantage that the ball is usually somewhere nearby.
His professional aspirations remain substantial. In late 2024, he spoke about wanting Verto to become a publicly listed non-bank financial institution, preferably in the United States, within five years. That was an ambition with work attached, rather than an announced listing timetable.
It leaves him with two measures of progress. One is the company he hopes to build. The other is available whenever a customer makes a payment. Somewhere, a business has an invoice, a supplier has a deadline, and the money needs to arrive. Oyetayo’s bet rests on making that sequence reassuringly uneventful.
Read, watch, follow
- Ola Oyetayo on LinkedIn
- Verto / Company website
- Watch: Griffin Uncut / Oyetayo with David Jarvis
- Read: Oyetayo on AI and payment operations
- The conversation about leadership and choosing a market
- The personal questionnaire / First jobs, books and golf
- The longer interview / Banking obstacles and ambitions
- The early WhatsApp group and the business it became
- The interview about making payments as simple as a call
- The September 2026 Visa card announcement