The useful thing about an irritating fee is its honesty. It tells you exactly where the customer and the institution have ceased to be friends. Nik Storonsky found his fee while travelling as a derivatives trader. Each card payment abroad arrived with a foreign-exchange markup, although he knew that banks could exchange currency with one another at far better rates. The arithmetic was plain. The product built around it was plainer: a card, connected to an app, that let people spend abroad without the familiar sting.
That was Revolut in 2015, when Storonsky and software engineer Vlad Yatsenko began the company in London. One supplied the commercial impatience, the other the technical machinery. Their opening proposition was narrow enough to explain in a sentence and broad enough to travel. It acquired customers, and then it acquired ambitions.
Today the travel card has become a platform for payments, subscriptions, savings, trading, business accounts and lending. Revolut ended 2025 with 68.3 million retail customers, $6 billion in annual revenue and $2.3 billion in profit before tax. In 2026 it said the customer count had passed 80 million. The company operates across 40 markets, as a licensed bank in more than 30 of them. Storonsky's irritation has developed a balance sheet.
A physicist learns the price of friction
Storonsky was born in 1984 in Dolgoprudny, north of Moscow. He studied general and applied physics at the Moscow Institute of Physics and Technology, while also taking applied economics and finance at the New Economic School. Both master's degrees arrived in 2007. So did the beginning of his full-time career in London, on the equity derivatives desk at Lehman Brothers.
The timing offered a severe education. Lehman collapsed the following year. Storonsky has recalled trading books moving by hundreds of millions of dollars in a day, a spectacle that made the institution's appetite for risk look less like sophistication than exposure. He moved to Credit Suisse, where his lesson was organizational rather than financial. Internal competition could consume energy that ought to be aimed at the market.
He left in 2013, the year he became a British citizen. Two years later, Revolut launched. The sequence matters because the company inherited the trader's tempo and the physicist's preference for systems. Problems were to be decomposed. Performance was to be measured. Targets were not ornaments for presentations but instruments for deciding who did what next.
“Our mission has always been to simplify money for our customers, and our vision to become the world's first truly global bank is the ultimate expression of that.”Nik Storonsky, at the opening of Revolut's London global headquarters
There was an older rhythm too. Storonsky boxed and swam when young, becoming a regional swimming champion during university. Swimming rewards the mercilessly observable: a turn, a stroke, a fraction of a second. The clock has no department politics. Revolut's operating culture can feel like a stopwatch translated into corporate life.
The card keeps widening
Many companies defend their first success. Revolut kept attaching rooms to it. Currency exchange led to accounts and transfers, then subscriptions, stock and crypto trading, business finance, credit and other services that vary by country. By 2025, eleven product lines each generated more than £100 million in annual revenue. No single feature had to carry the house.
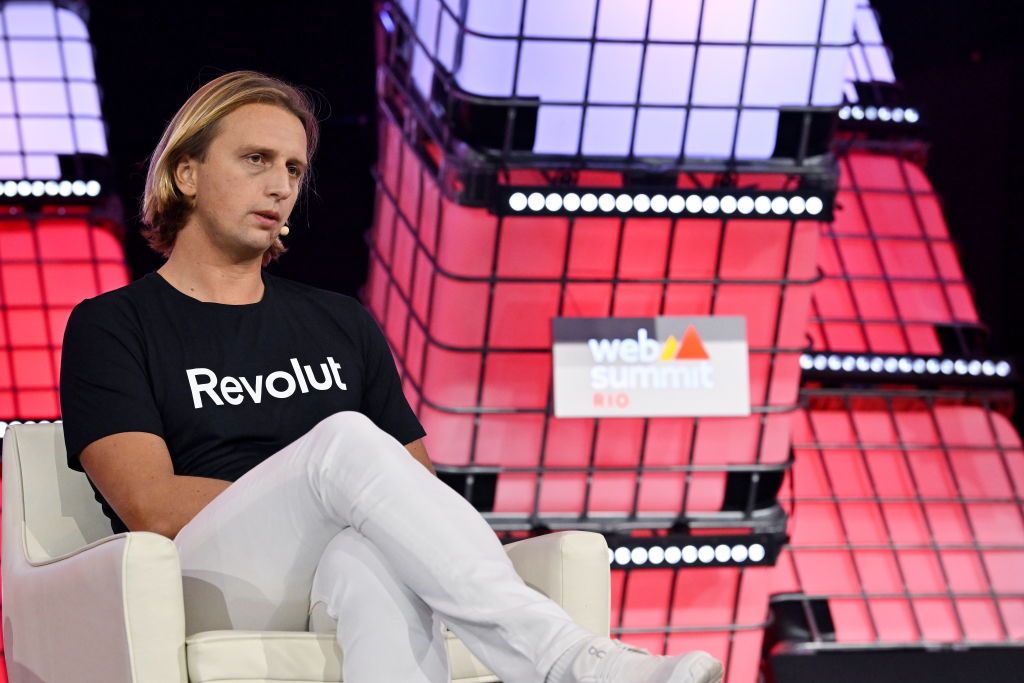
The expansion was geographic as well as functional. A product built to make borders less expensive soon encountered the fact that finance is governed border by border. Licences cannot be copied and pasted. Regulators do not ship quarterly because a product team does. Revolut's effort to secure full banking status in Britain took years and attracted scrutiny of its controls and recordkeeping. The company received a restricted UK licence in 2024 and completed the mobilisation stage in 2026.
Profit changed the quality of the argument. For years, a sceptic could describe Revolut as an attractive interface subsidised by patient capital. Five consecutive years of net profitability made that line harder to sustain. Its 2025 revenue did not depend on one lucky trade or one fashionable product: subscriptions, card payments, wealth services, foreign exchange and business banking all contributed. Customer balances rose 66 percent to $67.5 billion. The little card for travellers had become somewhere tens of millions of people were willing to leave their money. That is a less glamorous metric than app downloads, and a more consequential one.
This is the central contradiction of Storonsky's project. The app promises that money should move with the ease of software. The institution behind it must persuade regulators that every movement is controlled, recorded and understood. Speed wins customers. Deliberation keeps a bank licensed. Revolut needs both muscles, even if they pull in opposite directions.
A culture designed like a machine
Storonsky is unusually explicit about how he wants a company to run. Hire people who can own difficult goals. Give them numbers. Review progress often. Remove bottlenecks. He has used the phrase “self-guided missiles” for senior leaders, a description that is flattering only if one admires autonomy and impact in equal measure.
The output is visible. So is the cost of the method. Revolut's demanding workplace has drawn criticism from current and former employees over the years. Storonsky has defended high expectations and has also written publicly about changing the culture as the company grew. The fair reading allows two facts to occupy the same room: intensity helped produce exceptional velocity, and intensity can become destructive when people are treated as entries on a performance table.
The startup instinct
Ship quickly, quantify progress, widen the product and attack a market before comfort hardens into procedure. →
The banking obligation
Control risk, document decisions, satisfy local rules and preserve trust when speed would prefer an immediate answer.
Storonsky does not conceal the size of his targets. Revolut wants 100 million customers by mid-2027 and entry into more than 30 additional markets by 2030. It has committed $13 billion to global investment over five years. During 2026 it advanced in Mexico, France, Colombia, Switzerland and the United States. Each new flag on the map is also a new set of obligations.
The second experiment
After quantifying a bank, Storonsky turned to the more clubbable world of venture capital. He founded QuantumLight in 2023. The firm's premise is that startup investing, an industry rich in lunches, lore and pattern recognition, can be made systematic. Its AI system, Aleph, examines billions of data points across hundreds of thousands of venture-backed companies. The inaugural fund closed at its $250 million cap in 2025.
It is a revealing sequel. Storonsky does not merely prefer data when data are convenient. He looks for domains that appear stubbornly human and tries to construct a scoring mechanism inside them. At Revolut, the object was banking. At QuantumLight, it is investor judgment. In both cases the proposition is faintly impolite: much of what professionals call wisdom may be habit wearing an expensive jacket.
The link between the two companies is not simply Storonsky's name. QuantumLight publishes operating playbooks drawn from Revolut, including guides to hiring and high performance. The fund therefore offers founders two things at once: capital selected through a model and management ideas collected from an unusually fast-growing company. It is venture investing as a transfer of operating code. Whether startup selection can ever become as systematic as Storonsky hopes will take years to judge, because venture outcomes unfold slowly. His patience for that verdict may be the most interesting variable in the model.
“A decade into this journey, we have only just begun to show what is possible.”Nik Storonsky, on Revolut's 2025 results
Yet models encounter the world eventually. A startup's character is not wholly contained in its growth curve. A bank's credibility cannot be reduced to the number of markets colored on a slide. Storonsky's great advantage is his refusal to be intimidated by institutional complexity. His continuing test is whether complexity sometimes contains information that speed misses.
The race changes when the lane disappears
The early Revolut story had an elegant villain: hidden foreign-exchange costs. The present story is less tidy. Revolut is no longer simply the clever challenger pointing at an incumbent's fees. It holds customer deposits, extends credit, seeks licences and answers to supervisors. It is becoming the kind of consequential institution that customers need to trust on ordinary Tuesdays, when nothing exciting should happen at all.
Storonsky, now a British entrepreneur with a company headquartered in London, has also had to define himself amid events larger than business. In 2022 he condemned Russia's invasion of Ukraine, pledged a temporary Revolut match for donations to the Red Cross appeal and renounced his Russian citizenship. His co-founder Yatsenko is Ukrainian-born. The supposedly borderless world can make biography more, not less, visible.
In June 2026, a jury of European financial journalists named Storonsky European Banker of the Year for 2025, the first time the award went to a neobank founder. The title carries a neat irony. Revolut was built from dissatisfaction with banks. Its founder is now being decorated as a banker.
Perhaps that is what the eleven-year experiment has really accomplished. Storonsky has not escaped banking. He has made its boundaries harder to see from the customer's side while accepting more of its weight on the institutional side. The card became an app, the app became a platform, and the platform is learning to be a bank in dozens of different legal languages.
The swimmer's next lane is the world, which is inconveniently shaped and full of regulators. The clock is running anyway.