Mark Buffington once made his living waiting for something to go wrong. On the West Coast, after graduate school, he traded options at a hedge fund, then started a market-making business of his own. The work rewarded a particular kind of attention: finding a risk that other people had priced too cheaply, buying exposure to it, and waiting. A trader could have an excellent theory and still spend an uncomfortable stretch watching the account shrink.
He described those stretches with the unromantic trader’s word “decay.” An option has an expiration date. Being right eventually can be an expensive way of being wrong today. His education in finance had given him the theory; running his own firm supplied the tuition bill.
Meanwhile, San Francisco was producing another sort of surprise. Google and other young businesses were making markets that had barely existed. Buffington began directing his attention toward the possibility of things going unusually well. The mathematics still interested him. What changed was the human activity behind the numbers. There were people building things he wanted to help succeed.
A return ticket to Atlanta
Atlanta offered a place to pursue that interest. In a 2018 interview, Buffington explained the attraction plainly: “there was a lot of great innovation happening here, and not a lot of capital serving the market.” The observation was both a homecoming argument and an investment thesis. Talent and money did not appear to be distributed in the same proportions.
He also joked about almost letting a baby stroller roll downhill in San Francisco. For a discussion about the allocation of capital, it was a useful reminder that moving cities involves rather more than comparing spreadsheets. His account of the return home included a family, a slope, and the practical attractions of another place to live.
By 2020, he was talking about the region in more granular terms. BIP’s State of Startups work examined venture activity across nine southeastern states. In his view, Atlanta had strengths in financial technology, software tools, and sales automation. A city could have particular industrial advantages that a national conversation about startups barely noticed.
That attention to place gave his investment argument something tangible. A useful business might emerge near customers, experienced employees, and industry knowledge. A fashionable ZIP code was optional. For an investor prepared to look closely, the distance from the Bay Area could itself be interesting.
An investor with a baseball past
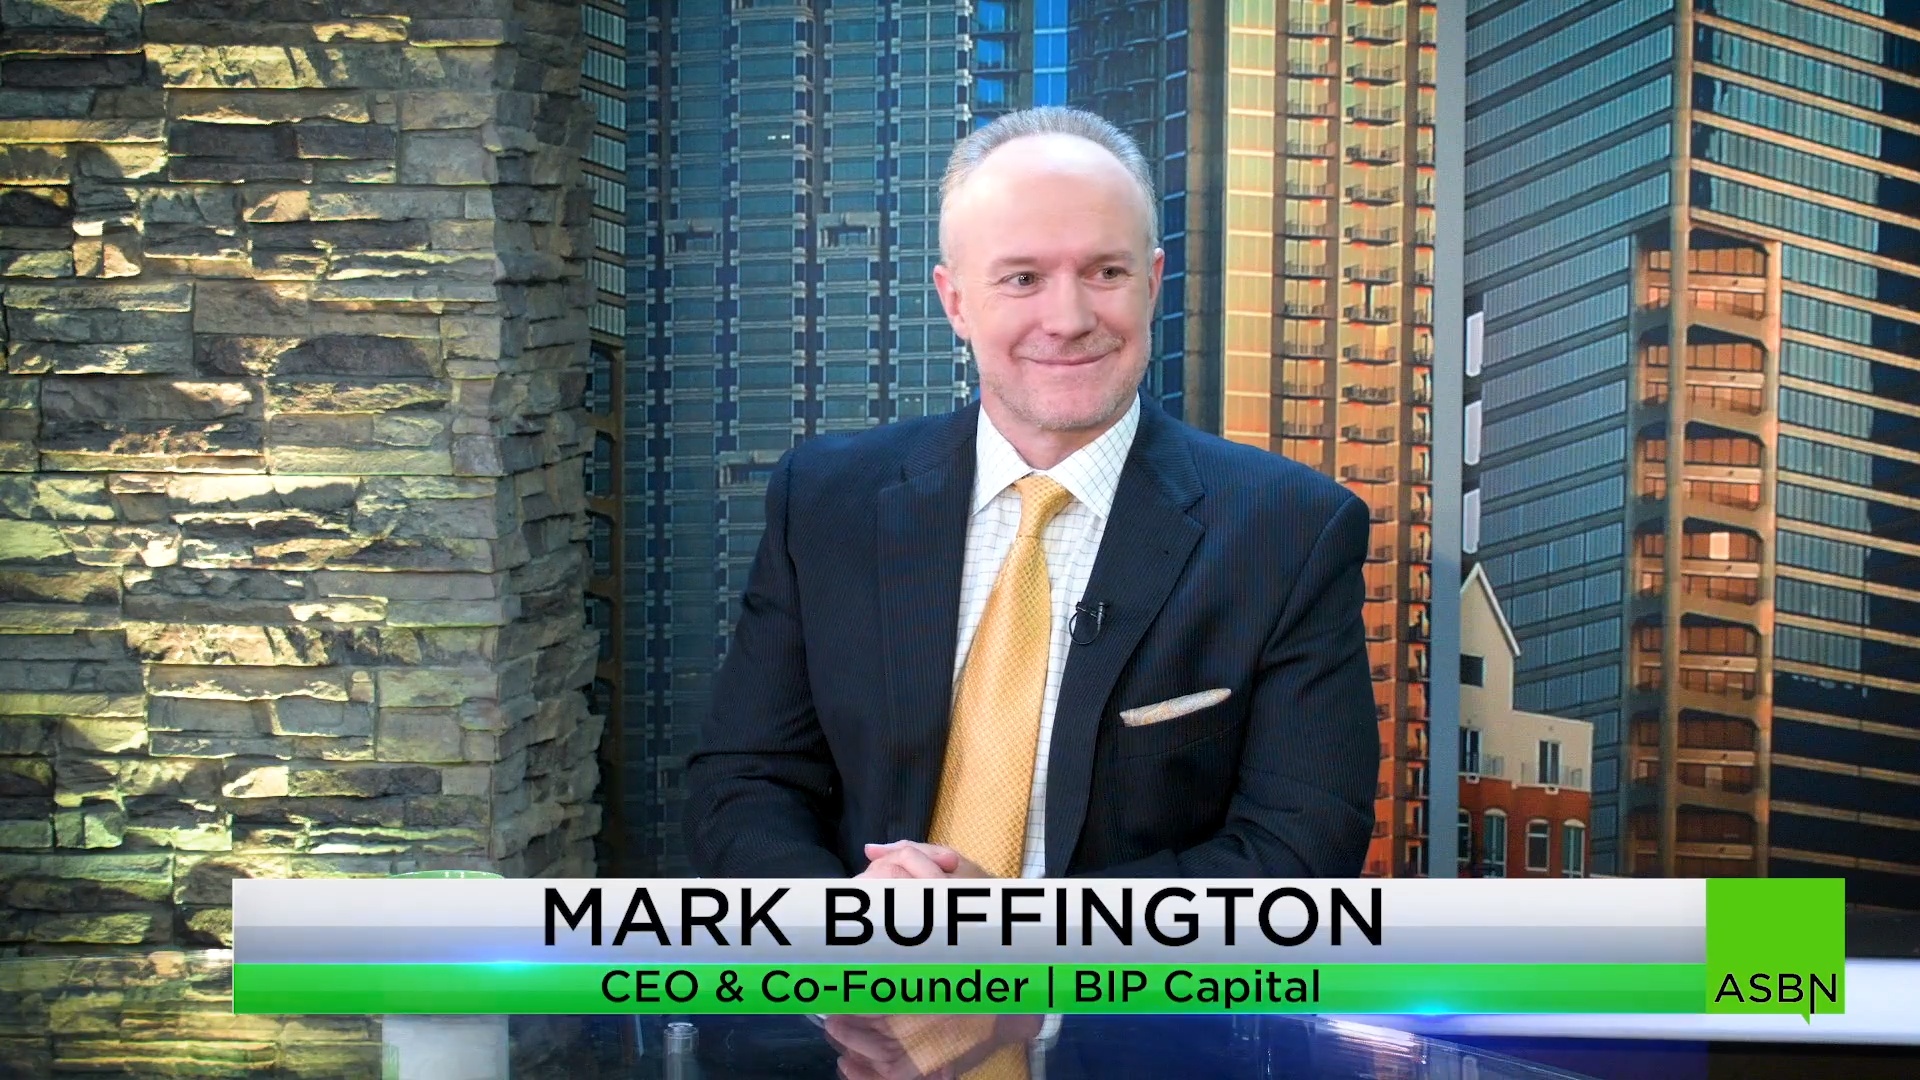
Buffington co-founded BIP Capital in 2006. He is its chief executive and the managing partner of BIP Ventures. His education joins a bachelor’s degree from Georgia Tech with an MBA from Tulane’s A. B. Freeman School of Business. At Georgia Tech, he also lettered in varsity baseball. Before the boardrooms came a different setting for keeping score.
His investment work has ranged across stages and business models. The companies in his professional biography include Cypress.io, ConnexPay, PlayOn, Huddle Tickets, and Tropical Smoothie Cafe. Software testing, payments, school sports, ticketing, and smoothies make an agreeably untidy dinner-party introduction. They also resist the idea that an investor’s working life can always be compressed into one fashionable sector.
His corporate board work includes PlayOn, NFHS Network, AchieveIt, and ConnexPay. Connections to the Buckhead Coalition and Georgia Tech’s College of Computing keep the local thread running through the institutional one. He has built a career that moves between allocating money, working with companies, and participating in the place where he chose to settle.
The customer gets a vote
For all the statistical vocabulary, Buffington’s explanation of a promising startup often begins with a buyer. A large market is attractive only if people inside it have a reason to act. In his writing, he calls them “compelled buyers”: customers who recognize a need and are willing to pay to address it. Admiration, by itself, does not settle an invoice.
He uses a racing analogy to explain the rest: market, team, and business model occupy the roles of track, jockey, and horse. Each changes the meaning of the others. An excellent team can be stranded in an indifferent market. A promising technology can arrive inside a business that has no durable way to sell it.
The interest is in the fit between those parts, and how that fit survives competition. Early entry does not confer permanent ownership of a category. As a market matures, the company needs leadership and a model capable of maturing with it. This makes his optimism conditional in an intelligible way: the opportunity has to hold up when a customer, competitor, or operating problem starts asking awkward questions.
Buying a little more time
Time enters the argument through the structure of the money. Buffington has described BIP as flexible, multistage capital, able to keep supporting a business as its needs change. In conversation with Shiv Narayanan, he explained the practical appeal: a founder who reaches agreed milestones may be able to raise again from an existing partner and spend less time traveling to pitch strangers.
He is careful about the word permanent. Investors still need exits. The purpose of an evergreen structure is to ease the pressure created by a fixed fund ending, so a company’s next decision can follow its development rather than somebody else’s calendar. That is a design choice with consequences for the working week of the person running the business.
His description of the partnership is equally ordinary. He wants people who can get into a room, use a whiteboard, and enjoy solving a hard problem together. He pays attention to people who claim every success while assigning every failure elsewhere. A decade is a long time to share a table with someone whose mistakes always belong to somebody else.
“Getting alignment is important; assessing the risk and gaps is super important.”
Mark Buffington · Extraordinary Pursuits, March 2025
A batting average, rather than a lottery ticket
In March 2025, Buffington took aim at a familiar venture-capital convention: expecting a very small group of investments to generate nearly all the returns. His objection concerned the behavior that belief can encourage. If most companies are treated as prospective write-offs, there is little room left for the founder who could build something valuable without becoming an enormous outlier.
He argues for paying attention to batting average. The former baseball player has found a financial use for the phrase, although the argument extends beyond sporting nostalgia. It asks investors to take responsibility for how often an investment works, alongside the size of the occasional exceptional result.
His position does not remove uncertainty. It changes the questions he wants asked before funding: how much has the business demonstrated, where are the gaps, and what amount of capital matches its readiness? More money can accelerate an already functioning model. It can also enlarge the consequences of an unresolved one. A fundraising announcement offers a crisp number; the company still has to earn its customers afterward.
The founder has to grow, too
By August 2025, Buffington was writing about a related mismatch: a company can grow faster than its founder’s way of leading it. The energy that gets a startup moving can become a constraint if every decision continues returning to the same desk. A founder who was once indispensable everywhere must learn where to stop being indispensable.
His prescriptions are concrete. Hire people whose operating strengths complement your own. Use experienced feedback to expose blind spots. Consider assigning day-to-day execution to a chief operating officer. Judge leadership partly by the capacity of other people to make good decisions. The objective is to keep the founder’s sense of purpose while making space for a larger organization.
There is a personal symmetry here: Buffington is a founder advising founders about the limits of founder instinct. He remains interested in the person with the original conviction, but also in the systems that will carry the business beyond that person’s reach. An idea may begin with one individual. Payroll, customers, and colleagues eventually require a more distributed arrangement.
The machinery behind the promise
Inside BIP, this interest in structure reaches into how information is presented. The firm has described an early difficulty getting clients into funds that turned out to involve onboarding and legal processes. The friction was administrative. Changing the process helped people understand what they were being asked to do. Even an investment business can lose the plot in its paperwork.
That story fits a broader emphasis on making private-market information usable. Reporting, data quality, and a comprehensible interface are part of the relationship with an investor. A sophisticated model provides limited comfort if its reader cannot understand the result. The firm’s stated approach puts technical work behind a relatively simple customer experience.
By December 2024, Buffington was also explaining how AI could assist sourcing, financial analysis, and portfolio monitoring. He called himself an “AI-optimist,” while acknowledging the risks of its applications. His interest lay in improving the quality and speed of decisions. The earlier trader’s appetite for better models was still visible, now applied to a different set of judgments.
The next clock he wants to reset
In February 2026, his Stacked Edge newsletter turned to the future of advisory firms. Buffington argued that licensing more software would be insufficient: firms should build and own the layer of intelligence that connects their work. He envisioned planning that updates continuously, with people spending more time interpreting decisions and less time gathering information.
He reserved a substantial role for human judgment, trust, and creativity. The ambition is an investment organization whose technology improves its ability to serve people through uncertainty. It is a recognizably consistent project for someone who has spent years moving between mathematical models and the imperfect circumstances of actual businesses.
His present also includes a legal dispute. In April 2026, SkillCycle founder Kristy McCann filed a federal lawsuit naming Buffington, BIP entities, and SkillCycle, alleging misconduct connected to control of the company and her removal. An amended complaint followed in June. These are allegations in civil litigation, rather than findings of wrongdoing.
The career leaves an interesting question in view. What can an investor change besides the amount on the check? Buffington’s answers have included geography, the duration of capital, the work after an investment, and the tools used to understand it. His story began with an expiration date. Much of his subsequent work has concerned giving a promising business enough room on the calendar to become a real one.
Keep the conversation going
Read, watch, and follow.
BIP Capital Company website ↗Mark on LinkedIn Professional profile ↗Stacked Edge Essays by Mark Buffington ↗What makes a startup ready for investment? Watch the full interview ↗Batting average and venture returns Extraordinary Pursuits ↗Why investors look to Georgia ASBN interview ↗McCann v. BIP Ventures, L.P. et al. Public civil docket ↗