Louis Hoch helped build a business on the expectation that people would stop opening envelopes, finding their checkbooks and paying bills at the kitchen table. Nearly three decades later, he runs a payments company with a print-and-mail operation. The envelope, it seems, declined to accept its obituary. Hoch has made room for it alongside software, cards and faster ways of moving money.
That accommodation tells you something about his working philosophy. A payment system must deal with people as they are, including their habits, preferences and inconveniently varied needs. The customer may want a digital wallet. The customer may want a check. A founder can spend considerable energy explaining why one of these people is wrong. Hoch would prefer to process the transaction.
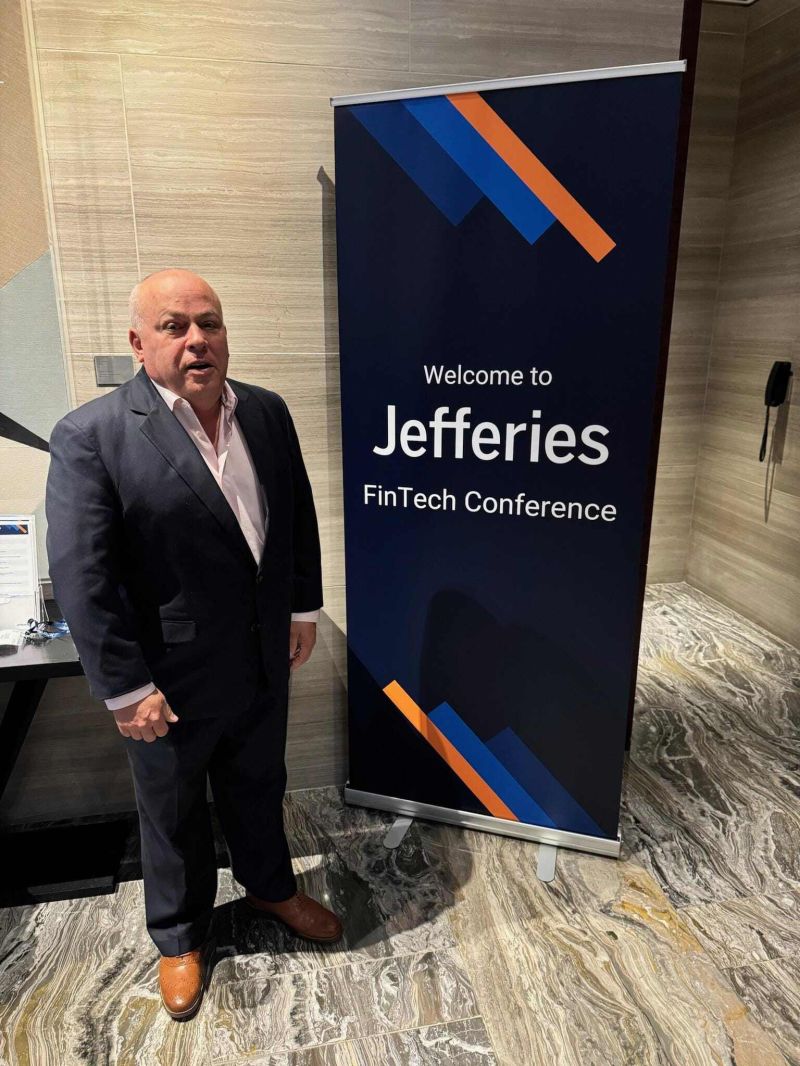
He is the co-founder, chairman, president and chief executive of Usio, based in San Antonio. His career connects the late-1990s electronic billing rush to the less visible machinery inside contemporary financial software. Along the way came changes of name, an inventor credit, a long apprenticeship beside fellow founders, and a persistent interest in giving the person at the other end more than one option.
A checkbook, a kitchen table, an opening
Billserv began in 1998, when electronic bill presentation still had plenty of practical problems to solve. Hoch, Michael Long and David Jones saw an opportunity to move bills online. The underlying task was familiar enough: get the bill to the person who owes the money, then make payment possible. The internet offered new places to do it.
In recalling those beginnings, Hoch described the household ritual of opening bills, writing checks and attaching stamps. His interest was in delivering the bill wherever the payer preferred to encounter it, including a bank website or the biller's own site. The strategic question was whether to pick a winning destination or support several. He favoured several.
Jones remembers the plan taking shape on the back of a napkin after the three had worked in the same broader business orbit. It is a pleasingly modest writing surface for an electronic billing company. More consequential was the shared experience behind the idea: these founders had already encountered one another through technology and telecommunications businesses.
Hoch had held management positions at U.S. Long Distance, Billing Concepts and Andersen Consulting. His education combined computer information systems with international business management at Our Lady of the Lake University. The technical and commercial strands would remain together. Understanding how a system behaves is useful; persuading another business to depend on it requires a different conversation.
The people behind the job titles
Long was central to that education. Their working relationship stretched across U.S. Long Distance and Billing Concepts into the founding of Billserv. When Hoch remembered him in 2022, he called him his “mentor, confidant, friend, and business partner for nearly 30 years.” The list makes the corporate biography sound less like a succession of appointments and more like a sustained collaboration.
Hoch singled out Long's ability to listen to customers, employees and shareholders. Those are three audiences with an impressive capacity to want different things at once. Hoch's recollection places listening alongside the technical work of building the business. A payment can be reduced to numbers. The reasons someone trusts you to handle it are harder to compress.
Another relationship began at university. Peter Kirby, his professor at Our Lady of the Lake, became a mentor, friend and golf partner over a connection lasting nearly 36 years. Kirby also served on the company's board from 2001 to 2016. The classroom relationship had acquired a boardroom address without losing its personal character.
Hoch admired Kirby's approach to strategic planning, organised around Mission, Commitment, Goals and Opportunities. It has the welcome property of being comprehensible without a consultant standing beside it. His account of Kirby emphasised the value of a coach and a voice of reason. Even a founder devoted to innovation appears to have appreciated someone who could make the plan intelligible.
An inventor's name in the paperwork
There is a more literal record of Hoch's technical involvement. U.S. Patent 7,021,530, granted on April 4, 2006, names Louis A. Hoch as inventor. Its subject is the management and processing of stored-value cards and bill payments made from them. The title is unlikely to win a poetry competition. The problem it addresses is much more interesting than the phrasing.
The patent describes connecting cardholders, input devices, payment networks and issuers so that transactions can be routed and verified. That is the unglamorous coordination on which a convenient payment depends. A customer sees a card and a balance. Underneath are separate organisations and systems that must agree on what has happened.
The inventor credit gives his biography a concrete technical marker alongside the executive titles. It also connects an older card-processing problem with his later interest in integrated payments. Across both, the work involves getting distinct components to cooperate closely enough that the person using them has less to think about.
“Innovation is a living thing, right?”
Louis Hoch, speaking on PayPod
When the payment disappears into the product
Hoch became chief executive on August 4, 2016, adding the title to his responsibilities as president, chief operating officer and vice chairman. Long remained chairman. By then the business operated as Payment Data Systems. In June 2019 it announced the Usio name, with the new stock symbol taking effect on July 1 alongside a planned Nasdaq closing-bell appearance.
The name came from “fusion,” reflecting a collection of payment technologies, products and people. It is a short word for a business that takes rather longer to explain. Card issuing, payment acceptance, bank transfers and billing services sit behind experiences that often carry somebody else's brand. The customer may recognise the software and never encounter the processor's name.
MoviePass offers a useful example. Hoch has explained how a subscriber's card transaction reaches Usio, which asks MoviePass whether the purchase fits the subscriber's available credits. Usio also checks that the company has the funds required to cover it. The theatre receives payment through the card system while the subscription service applies its own rules.
For Hoch, that is the attraction of embedded payments: the financial machinery fits the product's workflow. His recurring concern is whether the payment technology supports the software provider's relationship with its customer. Getting the transaction through matters. So does preserving the experience that brought the customer there.
- 01 / The cardA subscriber requests a cinema purchase.
- 02 / The decisionUsio routes authorisation to MoviePass for a credits check.
- 03 / The paymentAvailable company funds are checked and the theatre is paid.
A simplified account of the workflow Hoch described on PayPod.
Let the recipient choose
The same principle has a different expression in government disbursements. Usio's Consumer Choice offering allows recipients to select a payment method. A notice can send someone to a site carrying the programme's branding, where options can include a physical card, a virtual card or a bank payment. The infrastructure accommodates the recipient's choice.
A physical card can be useful even when a virtual one is available. A bank transfer can suit someone who has no interest in another card. Building these options into a programme requires more work than declaring a single method mandatory. It also acknowledges that receiving money is a personal experience, however large the programme distributing it.
Hoch's own description of value creation extends beyond shareholders to employees and customers. He has argued for an environment where technical staff feel comfortable sharing ideas. That is a practical management requirement for a business selling adaptation: the next awkward customer workflow may require someone inside the company to propose a different way of handling it.
The utility bill comes round again
In September 2026, Usio announced that Harris Computer had named it a preferred payments service provider for its utility software. The partnership brings Usio's payment capabilities into Harris's utility customer information system platform. For a founder whose early work concerned electronic bills, the utility payment remains a productive place to look.
The partnership joins billing software with several ways of paying, including cards and bank-based payments. Its appeal follows the same logic as the earlier business: the bill should meet the payer somewhere useful. The distribution has changed, and the software is different, but the question of how a customer gets from an amount owed to an amount paid remains.
The 2026 numbers give that continuing work a measurable setting. Usio reported second-quarter revenue of $23.7 million, up 19% from a year earlier, and approximately $0.3 million in net income. In October, it reported third-quarter ACH processing records, with transaction count up 39% and dollars processed up 26% year over year. These describe the company's activity, rather than its founder's personal wealth.
More transactions. More money moved.
Year-over-year growth. Bars share a 0-50% scale. Processing volume is distinct from revenue.
A future with room for the old furniture
Hoch has spoken about biometric tokens, digital wallets and artificial intelligence working together in future payments. He has also expressed interest in stablecoins as another potential payment channel. These are aspirations about where the infrastructure could go. His discussion of them sits alongside a business that continues to support much older methods.
There is a useful discipline in that combination. A prediction about tomorrow does not pay today's utility bill. People still need systems that accommodate the accounts, cards and documents they already have. The founder who began with an electronic alternative to the envelope has kept working on the connections between those worlds.
For all the vocabulary surrounding financial technology, Hoch returns to an ordinary human preference: people like having a say in what happens to their money. His career has been spent translating that preference into software and operations. The future can arrive in a wallet, on a card or through a bank account. Apparently, it may still occasionally require a stamp.
Keep the conversation going ↗
- Explore UsioCompany website
- Louis Hoch on LinkedInPersonal profile
- Louis Hoch on XPersonal profile
- The tech behind MoviePass and government payoutsPayPod / Interview & transcript
- Choosing customers and building for the long runThe Remarkable SaaS Podcast / Episode 399
- Watch Usio’s videosCompany YouTube channel
- Inside the stored-value card inventionU.S. Patent 7,021,530
- The Harris utility-software partnershipSeptember 2026 / Company announcement
- Usio’s second-quarter figuresAugust 2026 / Results
- The October ACH updateOctober 2026 / Company announcement