Consider the small indignity of owning a fraction of something. A credit union buys a stake in a loan pool. The transaction closes. Then come the payments, the ownership calculations, the changing balances, and the monthly reports. Buying the asset was an event. Understanding it becomes a recurring appointment.
LoanStreet Inc. has built its business around that appointment. It brings loan trading, servicing, reporting, and analytics into one platform for financial institutions. The interesting idea is that finding a buyer and keeping that buyer properly informed belong to the same job.
- Lenders can sell or buy loan interests to manage liquidity and diversify portfolios.
- LoanStreet links the deal to its continuing administration and performance data.
- Its analytics expanded in 2024 because clients wanted the same view of their entire loan books.
The paperwork has a long memory
A participation lets an institution sell an interest in a loan it has already originated. The seller can release cash and reduce a concentration. The buyer can put available funds to work in assets beyond its own lending footprint. Both acquire a continuing need to agree on what happened.
That is where a marketplace becomes more complicated than a list of things for sale. LoanStreet supplies standard agreements, due diligence information, and help from its trading and execution team. Institutions can evaluate consumer loan pools or commercial loans, with opportunities spanning mortgages, auto loans, and other asset classes.
The company says its standard agreement helps transactions close in days rather than weeks or months. That is a claim about reducing negotiation, not a promise that every loan will find a willing buyer. A reusable contract removes one source of delay. It cannot make two institutions agree on price.
Keep the record connected.
An illustrative $1 million pool. Move the slider to change the interest sold.
Ownership changes; the underlying pool still needs payments, records, and reporting. Example only, with no fees or losses modeled.
An engineer, a lawyer, and a shared record
Co-founder Ian Lampl’s background offers a clue to this combination. He studied electrical engineering at Princeton, became a lawyer, and served as Deputy Chief Counsel in the Treasury office that implemented TARP. The career joins systems thinking with the fine print of financial transactions.
His fellow founder, Chris Wu, brought software experience. In a 2015 biography, Wu connected his interest in community lenders to working in his family’s retail store. Between them, the founders had reasons to care about both the plumbing of credit and the businesses dependent on it.
The company reports more than 1,300 registered institutions and now describes customers in the United States, Canada, and Europe. The word “registered” matters: it describes the network’s reach, without telling us how frequently each institution trades.
registered institutions
Company-reported network size
The useful part happens next month
LoanStreet’s reporting product consolidates monthly information across loan purchases and sales, including transactions brought onto the platform from elsewhere. It provides loan-level payment details and accounting entries. A common data model gives an institution a way to reconcile information arriving from several counterparties.
Commercial servicing addresses another layer: interest calculations, borrower requests, payments, covenants, and documents. The current software handles bilateral, club, and syndicated loans. Borrowers can submit draw requests and covenant documents through a portal; lenders and agents see information according to their permissions.
The latest product description includes an AI credit agreement reader that extracts terms for review, with confidence scores and links back to the document. That review step is useful. Credit agreements contain consequential details; getting information into a system should still leave someone accountable for checking it.

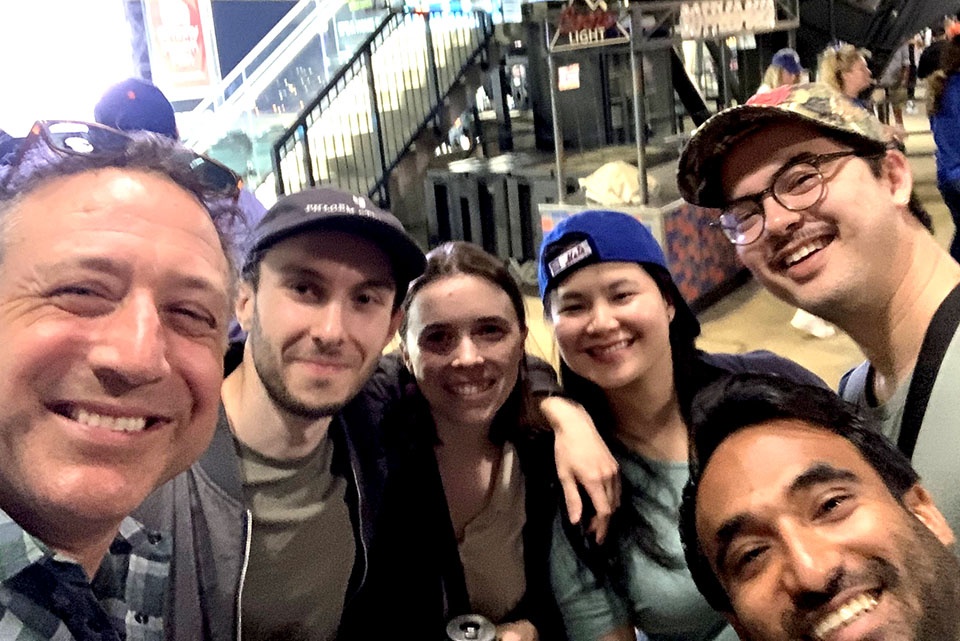
The people behind this software span lending, technology, operations, and law. LoanStreet’s careers page emphasizes learning and collaboration, alongside lunch-and-learns and remote team events. These are the company’s stated priorities. Its own team photograph supplies the less formal evidence: financial software people also go out together.
Customers asked for the rest of the book
Performance Analytics began with loan participations in December 2022. By January 2024, LoanStreet had extended it to institutions’ entire loan portfolios. Lampl said customers wanted the same analysis for directly originated loans and loans acquired outright from third parties. An adjacent need became a larger product.
The tools examine returns, prepayments, and charge-offs, and project cash flows under different assumptions. This matters because a loan’s coupon does not tell its whole economic story. Paying a premium, absorbing losses, or receiving principal earlier than expected can change what the institution earns.
There is a practical lesson here for software builders: an existing customer may reveal the next market by asking to use a useful tool on more of the work already on their desk.
Registration is free. LoanStreet describes fixed, flat fees for participation sales and optional paid servicing, reporting, and analytics. Buyers should compare the services they need with the staff time those services might save. The company’s $25 million Series B, announced in February 2022 and led by Portage Ventures, funded further investment in the platform.
The handoff is the next frontier
On September 28, 2026, LoanStreet announced a partnership with Prodeal, whose virtual data rooms support commercial origination, underwriting, and closing. LoanStreet handles the subsequent servicing and portfolio work. The announcement starts with taking the products to market together; clients will help shape how the platforms connect.
“The strongest lending programs are built to enable scale.”
Ian Lampl · Prodeal partnership announcement, September 2026
The competitive field includes ALIRO by LendKey, which also offers loan trading and post-sale services, and Versana’s syndicated-loan data connectivity. LoanStreet’s appeal lies in its particular combination of a lender network, standard documentation, administration, and portfolio analysis. Institutions should compare that combination against the workflows they actually need.
The fit depends on usable data, acceptable fees, appropriate counterparties, and credit judgment. An attractive screen cannot repair weak underwriting or create liquidity on demand. LoanStreet’s more persuasive proposition is modest: when institutions share a loan, the information should travel with it, every month until the work is done.