Larry Fink had already learned how to make money when he discovered how much he could lose. In the second quarter of 1986, his department at First Boston lost $100 million. A successful bond trader had encountered an awkward fact: a good record could coexist with a poor understanding of what might happen next. The number would become a recurring character in his account of himself. It was an expensive guest, and it stayed.
Two years later, Fink and seven partners founded BlackRock. The firm began in fixed income, with risk analysis at the center of its work. Decades of acquisitions, software development and client relationships followed. But the founding question remains unusually easy to state: how well do you understand the investments you are asking other people to trust?
That question has acquired a large audience. Fink is still BlackRock’s chairman and chief executive. His letters now range across corporate purpose, retirement, climate, technology and the ownership of economic growth. To understand the voice that addresses those subjects, it helps to begin with the trader whose confidence had outrun his calculations.
An expensive education
Fink grew up in Van Nuys, in California’s San Fernando Valley. His father ran a shoe store; his mother taught English. He studied political science at UCLA, graduating in 1974, then completed an MBA in real estate in 1976. Wall Street was a destination encouraged by professors, rather than a childhood inevitability.
He joined First Boston in New York in 1976 and built a career in mortgage-backed securities. The work connected the ordinary business of paying for a home with the financial machinery that packages and trades those payments. Understanding real estate was useful. Understanding what changing interest rates could do to the package was essential.
Then came the loss. Fink later described the failure as an inability to appreciate changing markets and the surrounding political and regulatory environment. His team had failed to manage the risks. The admission matters because it places the problem inside the organization’s judgment. Markets could change; the firm’s understanding had to change with them.
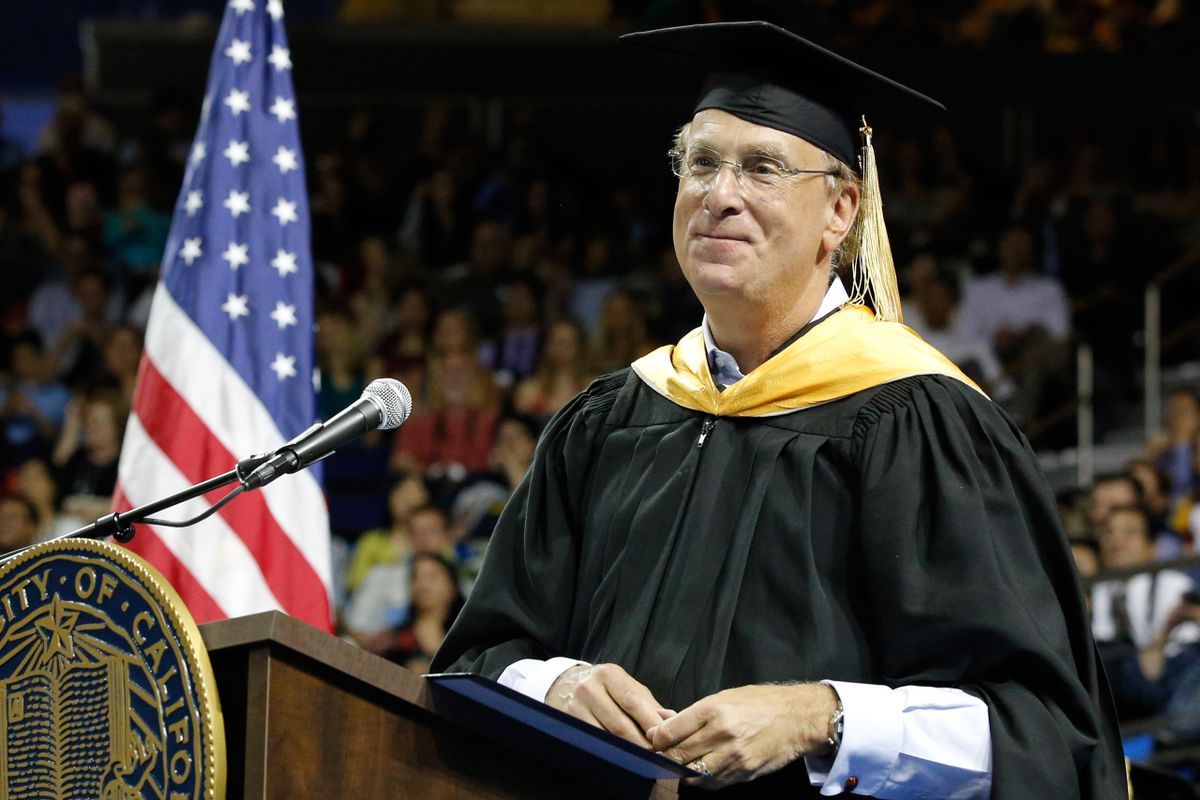
Returning to UCLA for commencement in 2016, he gave the graduating class a compact version of the lesson: “Humility is being able to admit that you were wrong.” There is a certain courtesy in bringing students an example of failure after they have spent years trying to avoid it.
Eight founders and a better set of questions
BlackRock’s founding group included Robert Kapito, Susan Wagner, Barbara Novick, Ben Golub, Hugh Frater, Ralph Schlosstein and Keith Anderson alongside Fink. Listing them is a useful correction to the solitary-founder version of business history. Eight people launched the firm in 1988. Its subsequent scale can make the original partnership disappear from view.
The early company combined investing with a belief that technology could improve the picture investors had of their holdings. BlackRock developed Aladdin to manage portfolios and risk. During the 1990s, it began offering the system’s capabilities to clients. A tool for doing the work became something other institutions could buy.
Aladdin now connects investment processes through shared data, spanning portfolio construction, risk analysis, operations and accounting. Its users include institutions making their own investment decisions. That gives BlackRock a second relationship with finance: it manages money and supplies technology used to manage money.
An editorial map of the relationships, not a measure of assets or returns.
The distinction helps explain Fink’s durability. A biography organized only around his market opinions would miss the infrastructure. Software turns the recurring task of checking exposures into an ongoing business relationship. It also gives the founding concern about incomplete understanding a practical expression. The questions have somewhere to live besides the chief executive’s memory.
When scale becomes a public role
BlackRock went public in 1999, ending that year with $165 billion under management. Its combination with Merrill Lynch Investment Managers expanded the business in 2006. The 2009 purchase of Barclays Global Investors brought iShares and systematic investing capabilities. An enterprise with fixed-income roots acquired a much wider place in ordinary investment portfolios.
Index investing brought its own problem of responsibility. In his 2018 CEO letter, Fink explained that an index fund generally keeps holding a company while it remains in the relevant index. An active manager can sell over disagreements about strategy. The continuing shareholder has stronger reasons to engage with the company about its future.
His argument extended to employees, customers and communities. A company’s ability to prosper, he wrote, depended partly on its contribution to the society around it. The letter put an investment executive into a debate about what corporations owe and to whom. Large asset managers had become participants in that argument by virtue of the shares they managed.
- 1986The First Boston loss raises the risk question.
- 1988Eight partners found BlackRock.
- 1999The firm lists on the New York Stock Exchange.
- 2009Barclays Global Investors brings iShares.
Fink’s letters consequently occupy an unusual genre. They are management correspondence with an audience beyond management. Their influence follows from the investments behind them, while their claims about society invite judgments that cannot be settled by a quarterly earnings number.
Six words, several arguments
In 2020, Fink put a short proposition into his CEO letter: “Climate risk is investment risk.” He asked readers to consider infrastructure, insurance, mortgages and the long periods over which investment assumptions have to hold. The subject entered through the same door as interest rates: what might change the value of an asset?
The formulation joined a financial argument to a political subject. BlackRock’s sustainability approach became a focus of conservative criticism, while the broader debate asked how far investment managers should go in influencing corporate conduct. The promise of assessing risk had reached questions on which clients, politicians and the public could disagree.
“Climate risk is investment risk.”
Larry Fink, 2020 CEO letter
By June 2023, Fink said he had stopped using the term ESG because it had become politicized. He maintained that BlackRock’s position on the underlying issues had not changed. That episode reveals a limit to the tidy origin story: risk analysis does not provide a vocabulary everyone accepts. Sometimes the vocabulary itself becomes the argument.
The permission to reconsider
Bitcoin offered another public test of Fink’s assumptions. He moved from skepticism to support, acknowledging in a July 2024 television interview that further study had changed his view. BlackRock’s spot Bitcoin ETF business gave that change a concrete commercial setting. A revised opinion could become a product clients could hold.
The episode is interesting without requiring anyone to share his conclusion about the asset. An executive whose words carry weight had acknowledged an earlier error in public. That bears a family resemblance to the UCLA speech, although changing a market opinion and recovering from a trading loss are different experiences.
In an October 2025 interview, when reminded that he had not always supported crypto, he answered, “I grow and learn.” A four-word reply is a convenient philosophy. The harder work is allowing new information to alter a business already built around older habits.
The next portfolio has fewer ticker symbols
Fink’s recent expansion reaches investments that do not sit neatly on a stock exchange screen. BlackRock completed its acquisition of Global Infrastructure Partners in October 2024. Preqin followed in March 2025, and HPS Investment Partners in July. Together, the deals extend the firm’s reach into infrastructure, private-market data and private credit.
Each fills a different position. GIP adds infrastructure investment expertise. HPS adds private financing capabilities. Preqin supplies information about markets where the data can be harder to assemble and compare. The combination reflects an ambition to serve more of a client’s portfolio, including assets outside listed stocks and bonds.
In his 2025 letter, Fink compared the difficulty of pricing private investments with buying a home before easily available neighborhood data. It was a revealing analogy for a former real-estate MBA student. The old concern about information was finding another market to work on. Better visibility was again part of the proposed business.
Who gets to own the future?
By the third quarter of 2026, BlackRock reported approximately $15.5 trillion under management and $205 billion in quarterly net inflows. Those are client assets and client flows. They should be kept separate from company revenue, corporate ownership and the personal wealth of its chief executive. The distinctions become more necessary as the numbers become harder to imagine.
Approximate client assets under management.
A management figure, separate from Fink’s personal wealth.
Fink’s 2026 annual letter argues for broader access to long-term investing. He describes a widening difference between people who own assets and people whose income comes primarily from work. His proposed response involves helping more people participate in capital markets and remain invested over time.
The aspiration and the commercial opportunity travel together. More investors can mean more customers for an asset manager. A wider ownership base is also a public proposition whose value has to be judged beyond the fortunes of any single firm. Fink’s position makes him both an advocate and an interested participant.
His appointment alongside André Hoffmann as interim co-chair of the World Economic Forum in August 2025 added another venue for those arguments. The former bond trader now works across conversations involving business, government and civil society. The distance from the trading desk is considerable; the concern about an uncertain future remains familiar.
There is a pleasing complication in his self-description as a long-term optimist. His professional story keeps returning to a failure of foresight. Confidence survived, but it acquired a requirement: keep examining what could go wrong. Forty years after the bad quarter, that requirement is still the most useful way into Larry Fink’s story.