A courtyard is an unusual place to look for an oil-and-gas investor’s ambitions. There is no drilling inventory to count, no production curve to inspect, no acreage position to assemble. There are places to sit. Yet when Kyle Miller and his wife, Katy, committed $5 million to a courtyard at SMU’s Cox School of Business, he described its promise in terms that a founder would recognize: companies that might begin over coffee.
It was a small, revealing shift in perspective. Miller had already built and sold substantial energy businesses. Here he was considering the business that had yet to exist, the introduction that had yet to happen. A shaded seat has a pleasingly modest job description. It only has to persuade someone to stay a little longer.
Miller’s career runs between these two settings: the operating assets of Silver Hill Energy Partners and a Dallas university whose classrooms, boards and athletic programs have repeatedly drawn him back. Follow that route and the familiar story of a large energy transaction becomes more personal. It becomes a story about what gets assembled around it.
A finance degree, then the other side of the desk
Miller earned his BBA in finance at SMU in 2001. His professional beginnings were in Houston, at Wells Fargo Bank and Wells Fargo Energy Advisors. He later became a vice president at Energy Spectrum Advisors in Dallas, then a principal and senior vice president at Energy Trust Partners.
At Energy Trust, his responsibilities included business development and helping oversee upstream private equity funds. Upstream is the industry’s shorthand for finding and producing oil and gas. The terminology makes the business sound like a geography lesson; the work asks investors to judge assets, operating plans and the people responsible for both.
Those roles gave Miller a career in the financing and evaluation of energy businesses before he founded one himself. The sequence matters. Silver Hill would combine investment decisions with ownership and operation, putting the financial plan and the field operation within the same enterprise.
In 2011, Miller founded Silver Hill. Dallas remained its base. The early business concentrated on the Delaware Basin in West Texas, building operating companies and joint ventures around unconventional oil, natural gas and associated infrastructure. Silver Hill I and II were separate vehicles within that effort. The founder’s work now included bringing together the assets that another investor might eventually want to own.
The acreage that made the arithmetic change
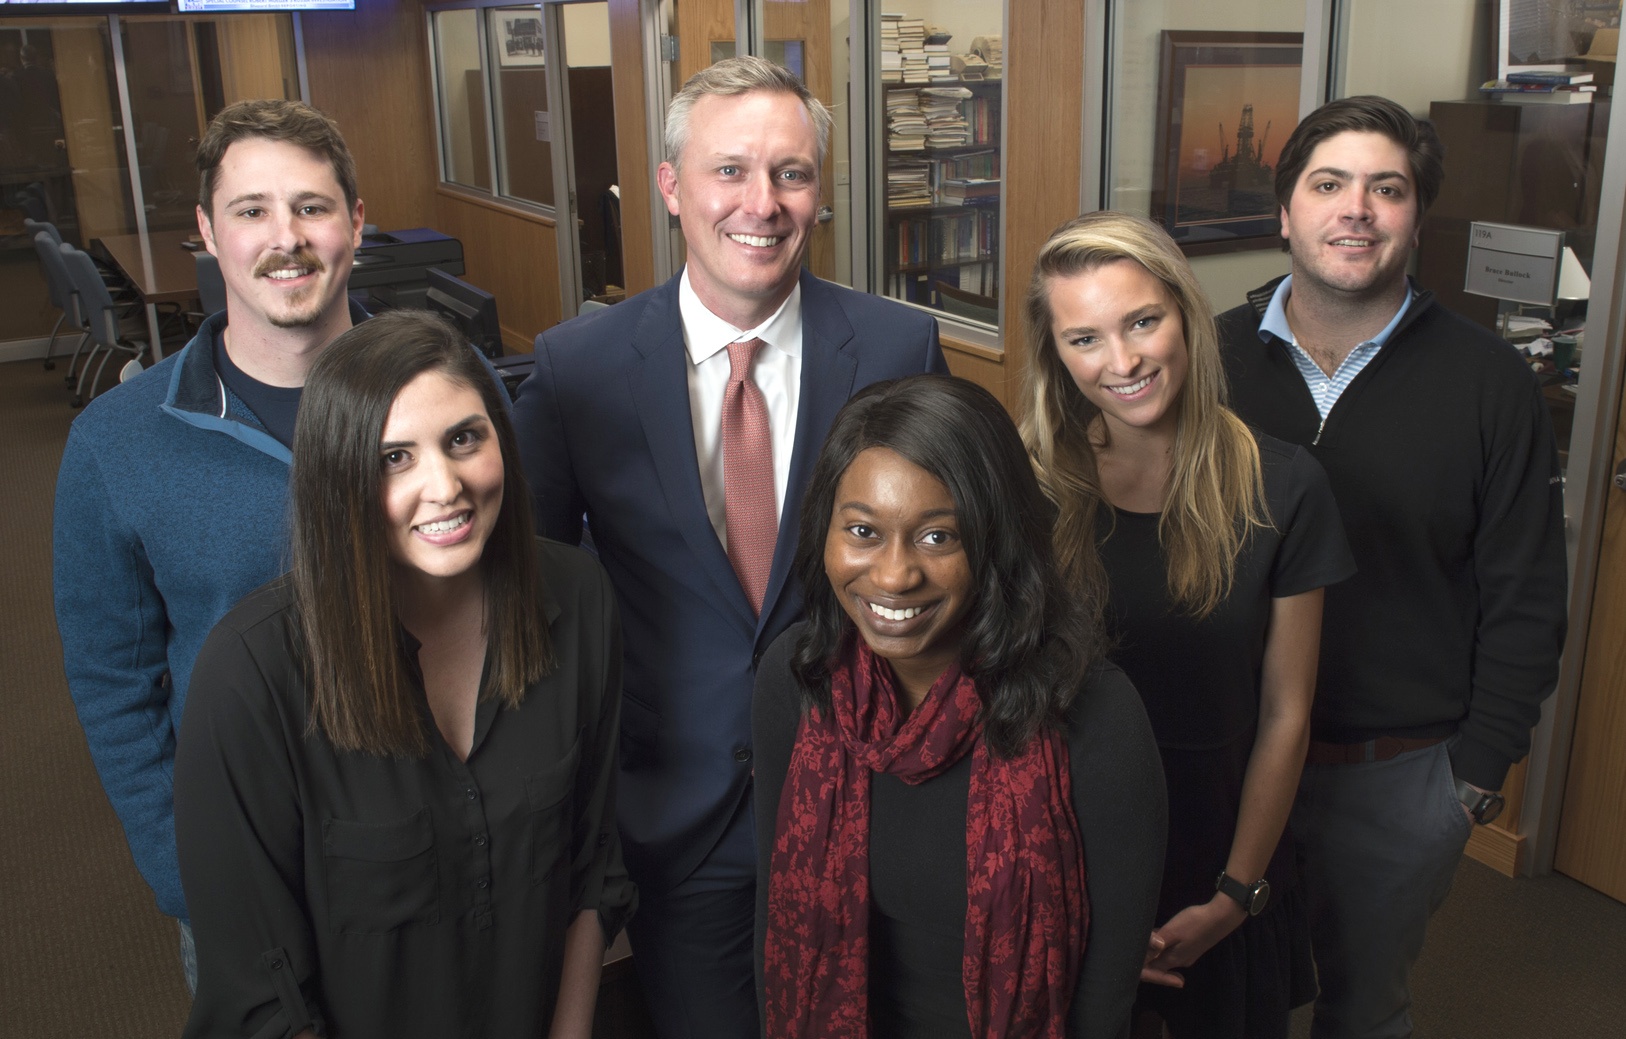
In October 2016, RSP Permian announced agreements to acquire the two Silver Hill businesses for approximately $2.4 billion in cash and stock. The announced package included about 41,000 net acres in Loving and Winkler counties and production of roughly 15,000 barrels of oil equivalent per day.
The scale is easier to understand when the figures are kept apart. Acreage described the land position. Daily production described what the assets were already delivering. The consideration combined cash with shares in the buyer. Each number answered a different question about the business Miller and his colleagues had assembled.
A deal of that size can make the preceding years disappear from view. The announcement is tidy; an operating company is less obliging. Silver Hill’s early history included acquiring and developing properties, establishing joint ventures and building related infrastructure. The transaction gathered that work into a price that could fit in a headline.
Miller’s professional identity also extended beyond the upstream assets. He created, managed and sold midstream and minerals joint ventures supporting the operating businesses. That broader set of activities helps explain the company he continued to build after the Delaware Basin sale: one concerned with the connections around production as well as production itself.
Roman numerals, returning investors
Silver Hill kept going. Its later partnerships extended the enterprise beyond its first Delaware Basin chapter. By July 2024, it had closed Silver Hill IV with $1.13 billion in capital commitments. The fourth partnership was also the company’s second institutional private equity fund, a distinction worth preserving when reading the Roman numerals.
Its investors included endowments, pension funds, foundations and family offices. A majority were returning investors. The sum attracted attention, but the composition supplied another useful detail: institutions that had participated before were committing again.
The fundraising announcement described seven large upstream acquisitions since August 2021, two supporting midstream projects and numerous minerals and royalty acquisitions. It also described a completed investment cycle in South Texas. Miller was continuing to buy, develop and sell, with different assets moving through that process at different times.
There is a rhythm here that a single exit obscures. A founder can sell one set of properties while preserving the organization’s capacity to evaluate the next. Silver Hill’s numbered partnerships record those successive rounds of capital and activity. They make the career read less like a finish line and more like a series of decisions about where to begin again.
Buying the pipes along with the wells
Silver Hill entered North Dakota’s Bakken through a transaction with Liberty Resources II that closed in March 2024. The acquisition included upstream properties and all of Liberty Midstream Solutions. In practical terms, the package brought together producing assets with gas gathering, gas processing and water logistics.
The announced upstream position covered approximately 84,000 net acres and more than 300 gross operated drilling locations. Silver Hill planned to finance the acquisition with partnership equity and senior bank debt, and to use the position as a starting point for further investments in the area.
This is a particularly clear example of the way Miller’s company approaches an operating platform. The acquisition reached beyond the wells into the systems serving them. A production forecast may be the glamorous document in the room, but a gathering system has the useful habit of moving the actual gas.
The company’s stated strategy includes acquiring, improving and developing assets, with attention to landowners, employees, contractors and operating communities. Those commitments describe its intended approach. The Bakken transaction supplies a concrete picture of the assets involved: rights and properties, infrastructure and a plan for additional development.
An October sale, and another chapter still open
In October 2026, Centalion acquired Silver Hill’s upstream and midstream natural gas portfolio in Texas and Louisiana. Most of that Haynesville position had been assembled through acquisitions between late 2021 and mid-2023. During Silver Hill’s ownership, production rose from under 100 million cubic feet per day to more than 300 million.
The company operated as many as four rigs and expanded midstream and saltwater-disposal capacity. The sale involved approximately 72,000 net acres and about 300 gross operated development locations. It was another instance of assembling a position, developing it and transferring the resulting business to a new owner.
Silver Hill’s remaining operated portfolio was in the Bakken and Eagle Ford. It comprised roughly 115,000 operated net acres, about 1,000 gross drilling locations and approximately 22,000 barrels of oil equivalent per day, along with two midstream businesses. By then, the firm had raised approximately $4.2 billion in institutional equity across five partnerships.
These figures put Miller’s current role in perspective. The Delaware Basin transaction remains an early landmark, but his company has continued through additional basins and capital partnerships. The latest sale closes one asset chapter while substantial operations remain on the page.
The institution he keeps returning to
SMU appears throughout Miller’s public life. In 2015, Cox recognized him as an Outstanding Young Alumnus. In 2018, a donor effort led by trustee Tucker Bridwell assembled more than $5 million in tribute gifts honoring him. The principal beneficiaries were an energy management program and scholarship fund bearing Miller’s name.
The program connected business education with the energy industry through the Maguire Energy Institute. The scholarship fund supported undergraduate and MBA students. Some of the tribute also supported an indoor athletics facility. Finance, energy and the Mustangs were all present in the same gift.
By 2026, Miller served on SMU’s Board of Trustees, including its Athletics and Academic Affairs committees, and as vice chair of the Cox Executive Board. Cox selected him as a Distinguished Alumnus that year. These are continuing institutional responsibilities alongside the donations and recognition.
His family’s connection to the university stretches across generations. His father, David B. Miller, earned both undergraduate and MBA degrees there; his uncle Alan is also a Cox alumnus. In talking about his father, Kyle has emphasized the importance of one’s word and integrity. It is an account of inheritance measured in conduct as well as affiliations.
A place for the company that does not exist yet
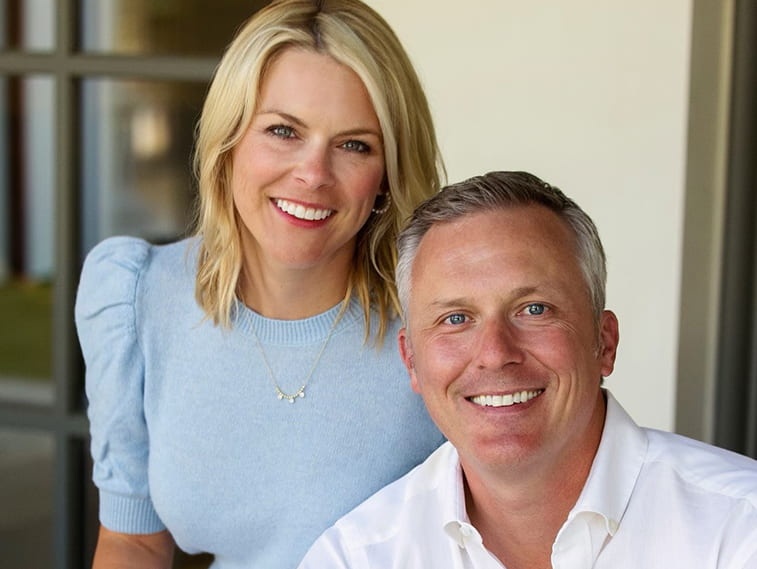
The courtyard gift adds a quieter ambition to this record. Miller and Katy supported a gathering place within Cox’s renovation and expansion, giving students, faculty and visitors somewhere to spend time together. His explanation allowed for a wonderfully uncertain outcome.
“We can’t wait to see what future Fortune 500 companies get their start over coffee in the courtyard.”
Kyle Miller, on the courtyard gift
No one can underwrite that coffee with much precision. The attraction is the possibility: a conversation can turn into a collaboration, and a collaboration might eventually acquire an address, employees and a balance sheet. Miller has spent his career assembling businesses whose assets can be counted. Here, the useful thing being provided is an opportunity to meet.
There is room in that picture for both the energy executive and the alumnus. One builds an operating position. The other helps build the setting in which someone else might find a beginning. The courtyard has no production target. It has chairs, shade and permission to linger.