Fifty years after his high school baseball team’s 1975 championship, Michael Greer took part in a reunion game with his old teammates. By then, he had spent decades in financial services and energy investing. There were companies to his name, acreage transactions in his biography, and funds with Roman numerals marching through their titles. He still had a reason to go back to the ballfield.
A reunion game is a pleasingly awkward kind of anniversary. The calendar supplies the occasion; the players supply the willingness. Greer enjoyed watching baseball as well as playing it, but this particular return put him among people who knew him before the executive title. The 50-year reunion belongs near the beginning of his story, even though it came near the end.
He co-founded Waveland in 2000. From Irvine, California, the business connected private capital with American energy projects. Its working relationships extended well beyond its office, into oil and gas basins where operators, acreage, engineering, and investment decisions had to meet. The distance between a California desk and a producing well was part of the job.
Before the funds had Roman numerals
Greer’s career in securities stretched back to 1981. Early registrations included American Growth Fund Sponsors and Private Ledger Financial Services. He was registered with Dunham & Greer Investment Counsel from November 1985 to July 1989. The sequence places his later energy work inside a longer financial-services career.
He passed the Series 7 general securities examination in August 1987 and the Series 24 general securities principal examination in October 1988. Those dates precede his next company by less than two years. In 1989, he founded Energy Partners, Inc., serving as its president until Benton Oil and Gas Company acquired it.
Further securities registrations took him through firms including Cullum & Sandow, Coleman & Company, and Centennial Capital Management. Waveland came in 2000, after years of work across this financial landscape. His Waveland Capital Partners registration ran from February 2002 to April 2025. A founder’s date of incorporation can look like an opening scene. Here, it arrives well into the working life.
His transaction history included a 35,000-acre position in southeastern Oklahoma divested to Chesapeake Energy and 120,000 acres in south-central Kansas sold to Royal Dutch Shell. The buyers and locations show another side of his career: preparing and transferring energy assets, alongside the work of organizing investment capital.
These two acreage transactions describe the size of the land positions involved. They give the career a geographical shape, with separate projects and separate counterparties. Acreage is a useful measure of a position’s extent; understanding its value requires much more than a map. That distinction helps keep a business biography grounded when the figures grow large.
A founder among colleagues
The Waveland photograph catches Greer standing at a table, one hand extended above the work surface. Maps fill the wall behind him. Three colleagues are visible around the table. There is a conference speaker, a notebook, and a pair of glasses. The objects are ordinary; together they make the business easier to picture than a list of investment terminology does.
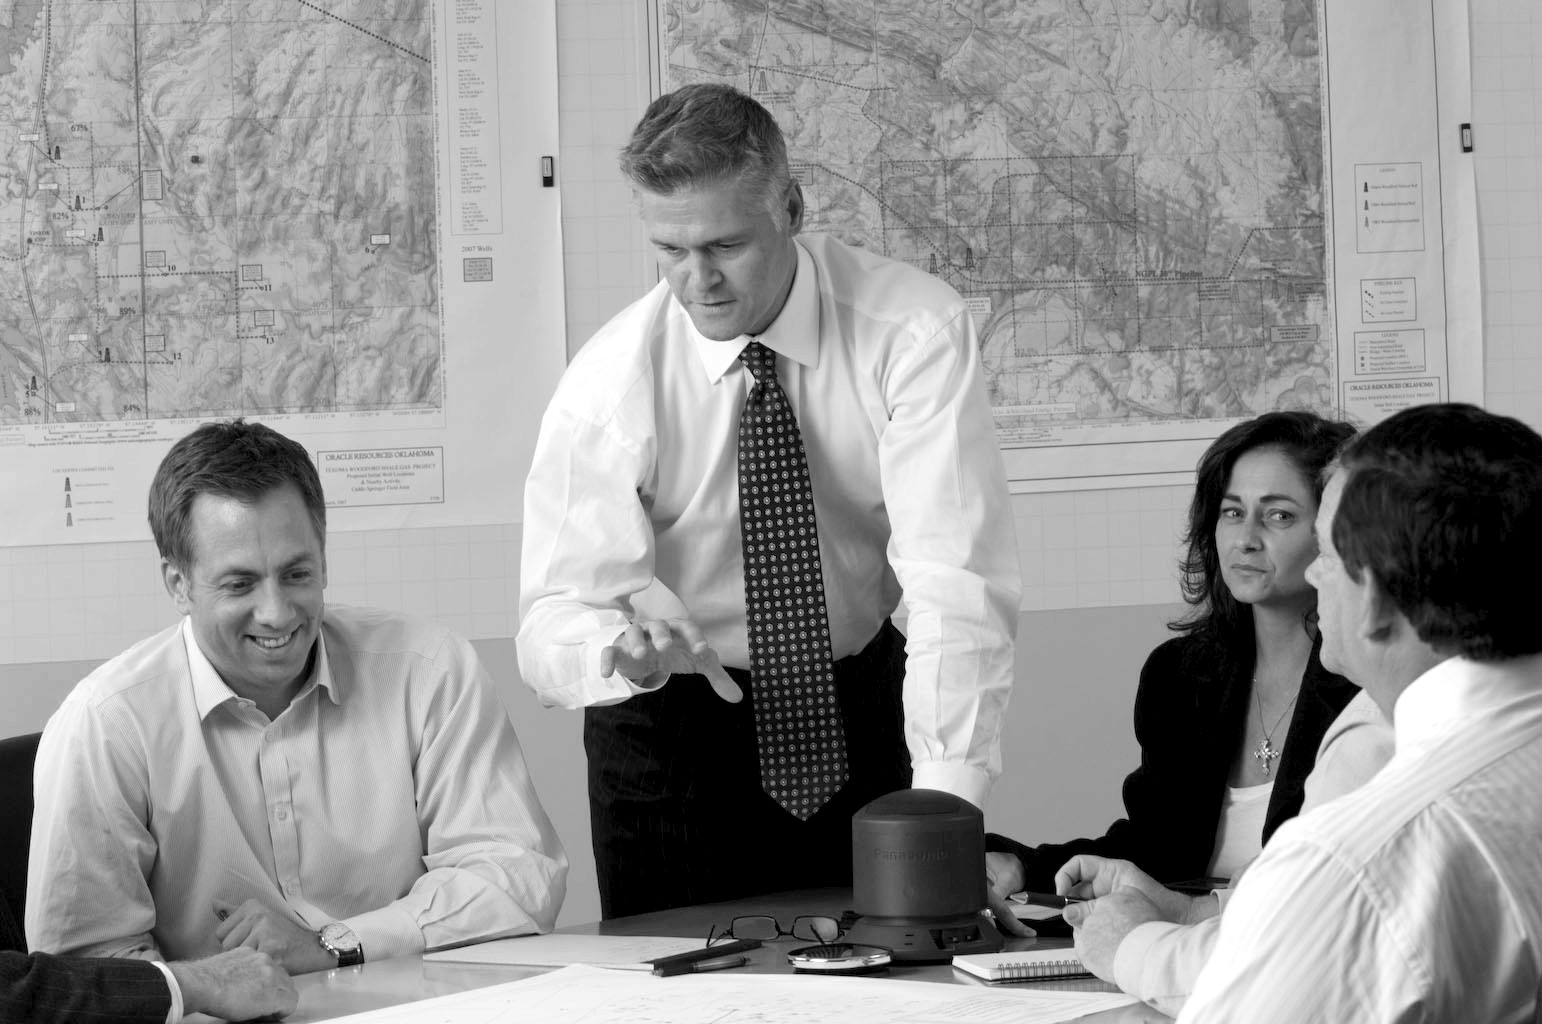
Energy finance gives several kinds of expertise a place at that table. Someone must evaluate the assets. Someone must organize the capital. Someone must manage the administrative and investor relationships that make an investment business function. The photograph does not explain a particular transaction, but it does offer a useful view of colleagues sharing a working space.
One continuing relationship was with Vickie Greer, Waveland’s fellow founder and chief operating officer from its inception. She became CEO in April 2025. Their responsibilities had appeared together in earlier offerings, including Resource Partners VI’s 2021 filing, which identified Michael as CEO and Vickie as COO. The leadership transition took place within a business she had helped build.
The operator has a different job
In May 2017, Waveland joined Trilantic North America and management in announcing an equity commitment to DJR Energy. The newly formed Denver company focused on New Mexico’s San Juan Basin. David H. Lehman, a geologist and entrepreneur with more than 40 years of industry experience, led DJR as CEO.
The initial proceeds supported an acquisition of assets from a private exploration and development company. Waveland brought a financial partnership; DJR brought an operating management team. That division of responsibilities is essential to understanding Greer’s business. An energy investment firm can participate in a project without directing every operation in the field.
The DJR partnership announcement gives names and roles to a process that otherwise disappears behind the word “investment.” Capital moved toward an asset acquisition through a company led by people with geological and operating experience. Greer’s firm was one participant in that arrangement. The work depended on the other participants having their own jobs to do.
Give the forecast some opposition
In 2018, Waveland Resource Partners IV closed after reaching a funding limit reported as $78.8 million. Its assets spanned the Permian Basin in West Texas, the Anadarko Basin in western Oklahoma, and the San Juan Basin in northwestern New Mexico. The plan was to acquire, develop, and sell projects over three to five years.
Greer described testing each prospective project against 10-15 modeling scenarios. The variables included hydrocarbon prices, reserve estimates, reinvestment rates, and exit valuations. A forecast had to face several versions of the future before a project could be assessed.
“Every prospective project is subjected to 10-15 distinctive modeling scenarios”
Michael Greer, 2018
Each variable asks a separate question. What price might the commodity command? How much can the reserves produce? What happens if operating cash is reinvested at a different rate? What might a buyer eventually pay? A handsome spreadsheet can be excellent company until someone changes an assumption. The questions are what make it useful.
His 2018 explanation is revealing because it describes a procedure rather than simply announcing a result. The scenario count was a feature of project evaluation, not a promise that uncertainty had been removed. Prices and valuations remained variables. The stated acquisition-and-sale timetable was a plan, with the usual distance between a plan and an eventual outcome.
Four named variables across 10-15 scenarios. A process description, not a performance forecast.
Keep the date beside the number
Resource Partners VI launched in June 2021. The original offering set out a $100 million amount. By August 31, 2023, when it closed to new investors, subscriptions totaled $135 million. The difference was $35 million, or 35 percent above the target. These are fundraising figures, and they belong to that particular offering.
“We appreciate the broad participation in our recently closed fund,” Greer said. At the time, the fund held minority equity interests in 122 wells in North Dakota’s Bakken Shale. Its stated approach combined operating income distributions with reinvestment in additional assets assembled for a potential sale.
The September 2023 announcement also put Waveland’s cumulative capital deployment above $760 million since inception. That was a firm-wide historical figure. It should sit beside the date, just as the well count should. An investor profile becomes clearer when its numbers retain their labels instead of being allowed to wander into one another.
A separate 2024 performance report described the asset holdings behind several Waveland funds, including interests in DJR and Bakken holding companies. The legal entities carried different parts of the portfolio. Those details help explain why an individual fund, an operating company, and the investment sponsor cannot be treated as interchangeable names for the same thing.
The work continues beyond a tenure
The projects developed during Greer’s career had later chapters. DJR merged with Enduring Resources IV in December 2023. Waveland’s Resource Partners IV account places that merger within the longer development of its San Juan Basin investment. The original 2017 partnership had become part of a broader operating business.
At the end of 2025, after Greer’s tenure, Waveland completed a sale of certain Williston Basin assets. Non-operated working interests went to Wellspring Energy Resources; mineral interests went to Mesa Minerals Partners. The assets came from Resource Partners II, III, IV, and V. Financial terms were not disclosed.
Vickie Greer was CEO for that transaction announced in January 2026. It adds a useful final business chapter to this profile because it follows assets through time while keeping responsibility in the proper period. A founder helps create the organization. Colleagues and successors continue making decisions after his tenure ends.
Back to the old team
Greer also left a little humor in public view. In a LinkedIn reply, he wrote, “this getting old thing is overrated!” The line needs little assistance. It is the sort of joke that sounds particularly at home beside a baseball reunion held half a century after a championship.
His public profile contains the smaller gestures of professional life, too: congratulations to a contact, an invitation to talk with another. Such exchanges are modest, but they belong in a story about relationships. An executive’s name appears on documents; a colleague’s name appears in a greeting.
Return, finally, to the reunion game. The investment chapters have their own dates and measures. The baseball anniversary offers another way to see the span of a life: people gathering again around something they once did together. Greer had gone on to build businesses. He was also still willing to turn up with his old team.