A truck has two biographies. One is written in kilometres, repairs and the fading paint on its cab. The other begins when somebody buys it to earn a living. Kogta Financial works at the meeting point of those two stories. Its proposition is easy to understand: a vehicle can have plenty of useful work left in it, even when its next owner needs help paying for it.
- Used vehicles accounted for 69% of Kogta’s loan book in March 2026.
- Its borrowers include transporters, farmers and small-business owners.
- Expansion depends on capital, local knowledge and repayments arriving on time.
Three years behind the wheel
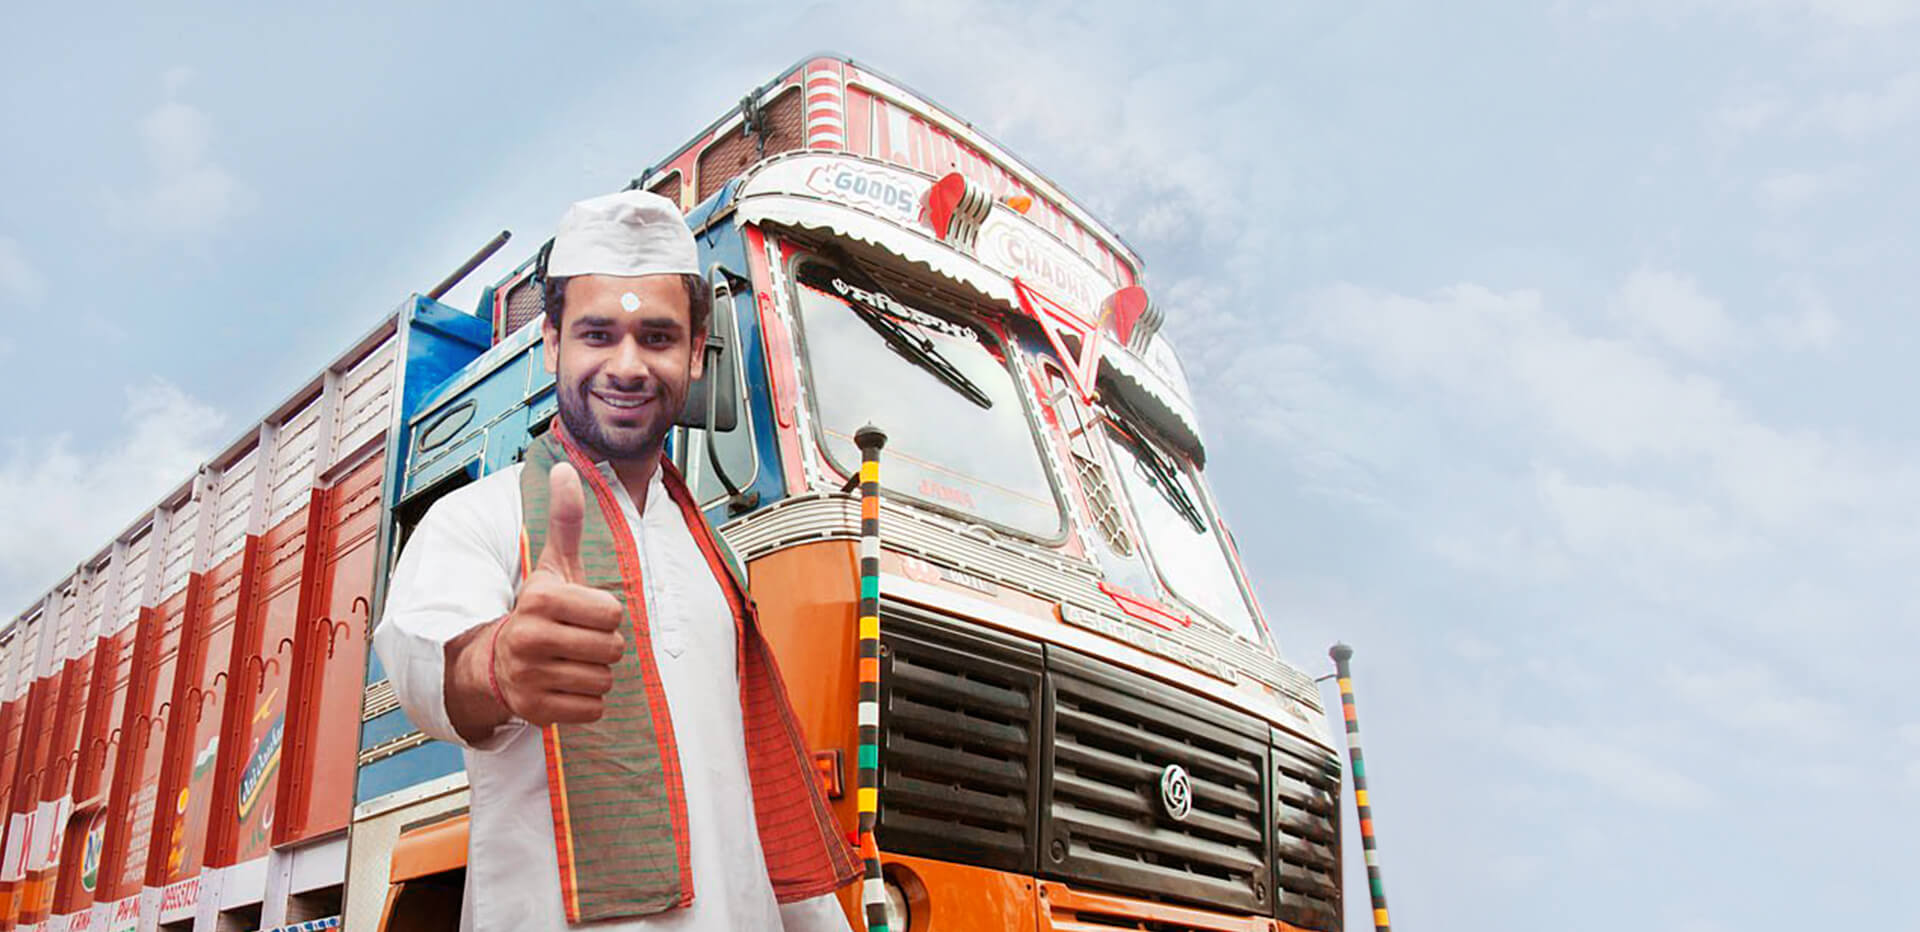
There is an unusually revealing detail on Kogta’s heavy commercial vehicle loan page. First-time buyers are eligible, but they need three years of driving experience. Think about the distinction. Someone can be new to owning a truck while already knowing the work. Ownership history and operating experience answer different questions. The loan product makes room for that difference.
The same offering includes customers without conventional income proof. That does not mean the borrower escapes scrutiny: the page also lists identity and address documents, bank statements and conditions on vehicle age. What changes is the doorway. A customer whose livelihood is difficult to describe through a neat salary slip can still be considered.
This helps explain Kogta’s place in the market. It is a non-banking financial company, or NBFC, providing secured vehicle and business credit. Its own history names small road transporters, taxi operators, farmers, retail traders and small industrial entrepreneurs among the people it serves. These are borrowers whose purchase may also be their means of earning.
Kogta has company in this market. SK Finance also offers vehicle and secured business loans. Kogta’s particular emphasis is the combination of used assets, eligible first-time owners and local assessment. Its appeal has to be judged against a borrower’s alternatives, rather than assumed from the size of a funding round.
The branch and the machine
Kogta was incorporated in Rajasthan in 1996 by Banwari Lal Kogta, Bal Mukund Kogta and Radha Krishan Kogta. Commercial vehicle finance operations began in 1998. The interval matters: this business had an operating history long before its institutional funding announcements became news.
Its published strategy emphasises contiguous expansion after understanding local market dynamics. There is a sensible operating idea here. Opening the next branch nearby gives a lender a chance to extend knowledge of customers and assets into adjacent territory. The company couples that physical presence with an internally developed ERP platform and risk-based pricing tied to the borrower and product.
Arun Kogta, now managing director and CEO, joined in 2004. His responsibilities include business development, credit, risk and collections. Varun Kogta, the whole-time director and CFO, is a chartered accountant with experience on banking audit teams. Their published biographies show the two sides of the task: finding lending opportunities and keeping the institution capable of funding them.
The company describes its culture as “freedom to grow”, with professional managers and system-led meritocratic operations. Its careers material stresses participation and learning. These are the employer’s stated ambitions, rather than a verdict on every employee’s experience. They also identify what expansion requires: decisions that can travel beyond the founding family.
The lender needs a lender
A lending company has to sell confidence twice. The borrower must trust the offer. The institutions providing capital must trust the lender. Kogta’s first institutional investment came from IIFL Seed Ventures in October 2016. Morgan Stanley participated in a roughly ₹154 crore round in 2018; Creador joined a ₹300 crore Series C in 2019.
The 2019 announcement already contained the balancing act. Arun spoke of increasing penetration “without compromising on credit quality”. The emphasis was on stronger systems and processes as well as expansion. A bigger map was only part of the ambition.
In March 2022, an ₹846 crore Series D led by Multiples brought in CPP Investments and included an exit for IIFL. In June 2024, Ontario Teachers’ Pension Plan announced an ₹1,230 crore investment, equivalent to $148 million. It acquired a significant minority stake.
Both transactions included capital for growth and exits for existing shareholders. So the announced amounts should not be read as cash entirely available for new loans. The 2024 deal provided partial exits for Morgan Stanley and Creador; Kotak Investment Banking advised on the transaction. At that point, Kogta reported more than 325,000 customers served cumulatively.
Someone can be new to owning a truck while already knowing the work.THE OWNERSHIP GAP
The price of getting moving
The product range follows working assets: heavy and light commercial vehicles, multi-utility vehicles, cars, tractors and construction equipment, alongside secured MSME loans and loans against property. Tractor finance advertises monthly or quarterly instalments. The MSME offering lists retailers, manufacturers, traders and service providers, with requirements including business experience and clear property title.
There is no single interest rate that describes this business. Kogta says pricing reflects risk. Its public fee schedule lists processing fees with a ₹2,500 minimum and an upper percentage of 2%, alongside valuation, registration and other charges. Taxes are additional. The EMI alone therefore does not describe the cost; the individual offer and applicable charges matter.
The repayment still has to arrive
The scale is substantial. At March 2026, Kogta had ₹8,300 crore in assets under management and 276 branches. Used vehicles represented 69% of the portfolio, new vehicles 14%, and property-backed MSME lending 17%. ICRA’s June 2026 report also shows gross non-performing assets rising from 2.6% in FY2024 to 3.8% in FY2026.
That pairing deserves attention. Expansion creates more earning assets, while overdue loans expose its limits. A financed truck still depends on paid work, maintenance and a borrower’s cash flow. Collateral cannot make an interrupted livelihood produce its next instalment. Lending against property likewise requires more than a valuable address.
The useful lesson to copy is specific: recognise relevant experience, understand the local market and build the systems before stretching the network. It depends on disciplined assessment and collections. Without those, an overlooked customer can become a misunderstood risk. Kogta’s story keeps returning to a practical question: what will this asset earn in its next owner’s hands?
Visit Kogta · Vehicle loans · Business loans · Loan charges · Company blog · Company news
LinkedIn · X · Instagram · Facebook · Kogta on YouTube