The old ballpark, the new ambition
A baseball stadium is an unusually cheerful place to contemplate mortgage servicing. Yet in August 2018, on the former Charlotte Knights stadium site in Fort Mill, South Carolina, Kevin Brungardt was talking about the future of an office. RoundPoint was breaking ground on a three-story headquarters. The proposed building would contain 150,000 square feet. The conversation reached considerably further than the floor plan.
Brungardt wanted a workplace that his children, grandchildren and their children might choose. “I want to leave that type of legacy,” he said. It was a striking ambition for a business whose everyday vocabulary includes unpaid principal balances and servicing rights. Those terms seldom find their way onto greeting cards. Still, a mortgage company can shape the life of a household long after the keys change hands.
The building offered a way to see the scale of what he had been doing. Brungardt had joined RoundPoint as chief executive in 2010. Eight years later, the company was planning a $34 million headquarters project. A career spent working through the machinery of housing finance had acquired a very visible construction site. Today, his work at Charlotte homebuilder SavAlex Homes supplies another, more literal expression of that connection to housing.
A career behind the monthly payment
Before RoundPoint, Brungardt held senior jobs at CitiMortgage and Fannie Mae. At CitiMortgage, he was managing director and head of national fulfillment operations. His earlier Fannie Mae responsibilities included its Servicing Asset Management group, which oversaw servicers’ performance in limiting credit losses across a mortgage book of nearly 18 million loans, representing $2.7 trillion in principal balance.
That was the scale of the book within his remit, rather than money he personally lent or owned. The distinction matters. Mortgage servicing is a business of responsibilities: collecting payments, maintaining records and managing the relationship between borrowers and the institutions with a financial interest in their loans. A balance can fit in a spreadsheet cell. The arrangements underneath it rarely do.
At Fannie Mae, he also belonged to the team that helped develop, implement and administer the Home Affordable Modification Program and the Streamlined Modification Program. His background brought together the handling of existing loans and the operations that move new mortgages through a lender.
His education ran through finance and economics: a BBA in finance at the University of North Texas, an MS in economics at the University of Texas at Dallas, and the Stanford Executive Program. By the time RoundPoint appointed him in June 2010, he had more than 15 years of executive experience. The job called for someone familiar with several parts of a mortgage business at once.
The decision to grow a month at a time
RoundPoint had been founded in 2007. Its early work included specialty servicing of distressed assets acquired in bulk. In 2012, the company changed its approach, pursuing partnerships with roughly 30 to 35 mostly midsized independent mortgage bankers. It would acquire servicing rights on newly originated mortgages as those loans were sold into the agency market.
The attraction, as Brungardt described it, was the ability to add business regularly, through a flow of new originations rather than relying on large purchases. A monthly rhythm could make expansion more methodical. It also meant the company’s growth depended on relationships with other lenders, alongside its own ability to look after the loans arriving.
There was an unromantic condition attached. Brungardt warned that a servicer needed compliance and customer service infrastructure before expanding. Both required time and money. It is an observation with little use on a motivational poster, but considerable use when the next batch of customers turns up. In this version of growth, the plumbing has to arrive before the housewarming.
That sequence helps explain his operating emphasis. More loans meant more obligations, and the systems had to bear them. The co-issue program, through which servicing rights accompanied new mortgage production, became an important part of RoundPoint’s expansion. Growth involved securing a recurring place in other companies’ workflows.
Bulk purchases
New mortgage servicing rights
Keeping the customer after the closing
In May 2016, RoundPoint brought in Kelli Yarbrough as vice president of loan retention. Her remit included customer contact and establishing an origination division to serve existing portfolio customers who might refinance. Brungardt had identified borrower retention as an increasingly important competitive issue for servicers.
There is a useful business question inside that appointment. When a borrower needs another mortgage, does the relationship continue with the company already handling the existing loan? RoundPoint wanted to make that possible. Offering a mortgage within a broader homeownership marketplace was part of Brungardt’s stated approach.
A year later, the company took on a different kind of relationship. Shared-equity provider Point selected RoundPoint as its sole servicer. Point’s product involved homeowners exchanging a share of their home’s equity for capital. The agreement put RoundPoint to work supporting an asset class outside the familiar monthly mortgage arrangement.
The partnership joined a young financial product to an established servicing operation. Point’s executives emphasized both asset-management experience and the technical capacity to work with something new. For Brungardt, the transaction fitted an interest in housing innovation. It also made his marketplace ambition more concrete: the company was extending what it could administer for homeowners and financial partners.
Capital, desks and the people in them
The expansion required financing of its own. In August 2018, RoundPoint announced a $94 million private placement of convertible preferred stock. The planned uses included expanding its mortgage servicing rights co-issue program, funding other corporate initiatives and repaying certain debt. It was capital for the institution doing the servicing, distinct from the mortgages it serviced.
At the same time, the headquarters plan put a physical address on the company’s ambitions. South Carolina announced the project in May 2018, describing a $34 million investment and projecting 1,100 new jobs. These were announced plans. They should be read as expectations attached to the project, rather than a count of positions already filled.
By the groundbreaking, Brungardt was talking about the employees as the reason to build. The proposed workplace belonged in a mixed-use development, with a setting intended to accommodate more than the working day. His remarks placed the company’s people inside the growth story, alongside the portfolio and the investment.
The numbers help establish the business’s reach. In May 2018, RoundPoint serviced more than $75 billion in mortgage assets and was licensed in all 50 states. The following year, he was recognized among the Charlotte region’s Most Admired CEOs. There was a local workplace to run inside the national operation.
Announced August 2018
Reported May 2018
A national business changes hands
In August 2020, Freedom Mortgage and RoundPoint completed their merger. RoundPoint became a wholly owned subsidiary. At completion, its servicing and subservicing portfolio stood at approximately $75 billion in unpaid principal balance. Freedom’s combined owned and subserviced portfolio was approximately $310 billion.
Those figures describe two different perimeters: RoundPoint’s business and the combined Freedom business. Neither is a valuation of Brungardt’s stake or a measure of his personal wealth. Their significance lies in the number of mortgage relationships and the operational work brought together.
The combination gave Freedom an active subservicing platform and expanded its co-issue origination network. Brungardt, still identified as RoundPoint’s CEO in the announcement, described the prospect of combining the companies’ resources and expertise. Freedom chief executive Stan Middleman pointed to the more than 378,000 customers joining its ecosystem.
For Brungardt’s career, the transaction marks a clear milestone after a decade leading RoundPoint. The firm he had joined in 2010 was now part of a larger mortgage organization. His later work would return the focus to Charlotte and to a much smaller unit of housing activity: the individual development site.
The view from a Charlotte building lot
SavAlex Homes was founded in 2023. A December announcement that year identified Brungardt as its managing member. The business was acquiring residential lots in Charlotte, including the Grier Heights and Elizabeth Acres area, with the intention of adding homes. Its finance head, Trey Brungardt, described that transaction as the company’s third acquisition of lots in the neighborhood that year.
The company also listed activity in places including Biddleville, Druid Hills, NoDa and Lower South End. Here the geography becomes specific enough to walk around. Instead of a portfolio distributed across the country, the conversation concerns a collection of lots, nearby amenities and the practical question of where another home can be built.
In July 2024, Brungardt appeared with Russell Fergusson as part of SavAlex’s development team at a community meeting connected to a Charlotte rezoning petition. That is a different setting from a national mortgage transaction, with its own audience and its own questions. The common thread is the work of getting housing from an intention into an operating reality.
His public activity now includes SavAlex projects and its construction team. The change in scale gives the career a particular shape. He has worked on the administration of housing debt, the growth of a national servicing business and the development of homes. Each reaches the household from a different direction.
“I want to leave that type of legacy.”
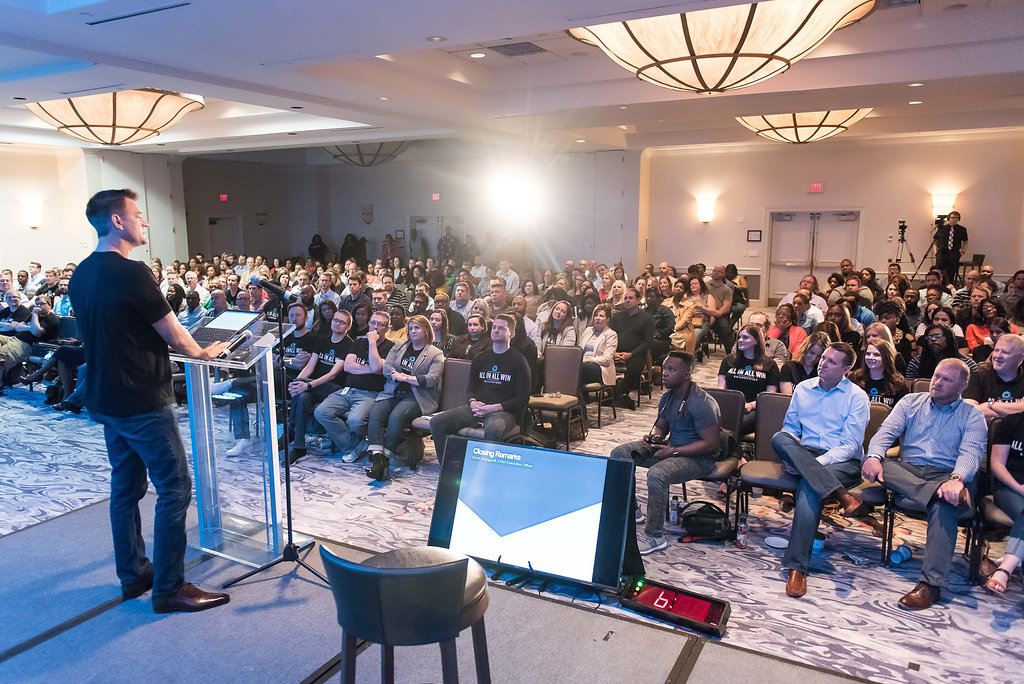
Kevin Brungardt / Fort Mill groundbreaking, 2018
The family name on the plans
There is a personal detail inside the newer company’s name. Brungardt has explained that SavAlex combines Savannah and Alexandra, the names of their daughters. After years in an industry fond of initials, acronyms and carefully neutral corporate names, two family names make a rather warmer signboard.
It also recalls the ambition he voiced at the old ballpark. In 2018, he imagined successive generations wanting to work at the company whose headquarters was taking shape. With SavAlex, the family connection is present before anyone opens the door. That does not establish what comes next, but it gives his stated interest in legacy a tangible form.
The work remains practical. Homes need land. Mortgage businesses need capital. Expanding either requires people who can execute the plan. Brungardt’s career has repeatedly put those requirements next to broader ambitions about homeownership. The details have changed from servicing rights to neighborhood developments, and from a national platform to particular streets in Charlotte.
At the former stadium, the future was a building drawn to accommodate a growing company. In his newer chapter, the buildings are homes. A mortgage executive who spent years dealing with what happens after a purchase is now involved in making places available to purchase in the first place. There is a certain satisfaction in a career that eventually comes around to the front door.