A tax notice arrived in Jessica Chen Riolfi’s mail. She sought a second opinion and learned that her returns had been filed incorrectly for three years. For someone who had spent a career working on financial products, this was a particularly pointed piece of correspondence. Expertise in the industry had not spared her from needing better help with her own paperwork.
By then, she was building Uprise, a company concerned with the decisions people struggle to make about money. Tax emerged as a recurring obstacle in that work. Her own experience supplied a vivid example of the problem she was hearing about from customers: a person can do the responsible thing, hire help, and still discover that important details have gone astray.
The interesting question in Jessica’s career is how she responds when the details refuse to fit the plan. Her work has taken her from international money transfers to consumer financial products, then into founding a company whose audience and offering have changed. Across those moves, she has kept returning to the person who has access to a financial tool and still needs help deciding what comes next.
A mother’s advice, with a much larger audience
Her first example of useful financial guidance was close to home. Jessica’s mother, an immigrant who worked at the FDIC, taught her about banking, saving and taxes. The lesson came with a relationship: someone knew her circumstances, had knowledge to share, and could offer it at the appropriate moment.
Jessica has described the ambition behind Uprise as “scaling my mom.” It is a charming phrase for a demanding task. A mother does not wait for a daughter to complete a questionnaire before recognizing that she could use some guidance. Nor is the value of the conversation exhausted by delivering a technically correct answer. The answer has to land in a life.
That household example helps explain the kind of service Jessica wants to build. Knowing what is possible and knowing what to do are different stages of a decision. A product may make the first stage easier while leaving the second to the user. Her ambition asks a company to take responsibility for more of the distance between the two.
She also grew up in a Chinese-American household with a close interest in what was happening across the Pacific. Visits to Shanghai gave her a memorable view of economic change: the city she encountered in the early 1990s looked very different when she returned about a decade later. An aunt proudly showing a newly built home made the change personal.
Fifteen countries, then the unfinished question
Jessica’s education includes a BA from Dartmouth and an MBA from Harvard Business School. Her early career included J.P. Morgan and eBay. In 2015, she joined the company then called TransferWise, now Wise, where international expansion gave her a practical way to work on access to financial services.
By February 2018, she was leading its Asia business, with responsibility for 15 countries, including India and China. She spoke about smaller companies as places where someone could raise a hand and take responsibility. Fewer established structures meant more room to act, along with fewer places to hide behind an established procedure.
Her operating interests also left a written trail. She published essays about international expansion and startup culture, then about autonomous product teams at Earnin. Those are subjects concerned with how decisions get made: which market to enter, how people give feedback, how much authority a team should hold.
The writing gives the career more texture than a row of company names. A financial product needs an organization behind it, and an organization needs ways to hear uncomfortable information. Decisions about teams and culture affect whether that information travels far enough to change the product.
Jessica went on to serve as Head of Product at Earnin and as chief of staff to the Head of Product at Robinhood. Across those businesses, she encountered customers whose questions extended beyond the products themselves. Having access to a service did not settle what they should do with their financial lives.
For a product operator, that is an awkward boundary. The screen may work perfectly. The customer may still be unsure. Jessica’s move toward founding grew from paying attention to the uncertainty that remained after fintech had made so many individual actions easier.
The customers who changed the plan
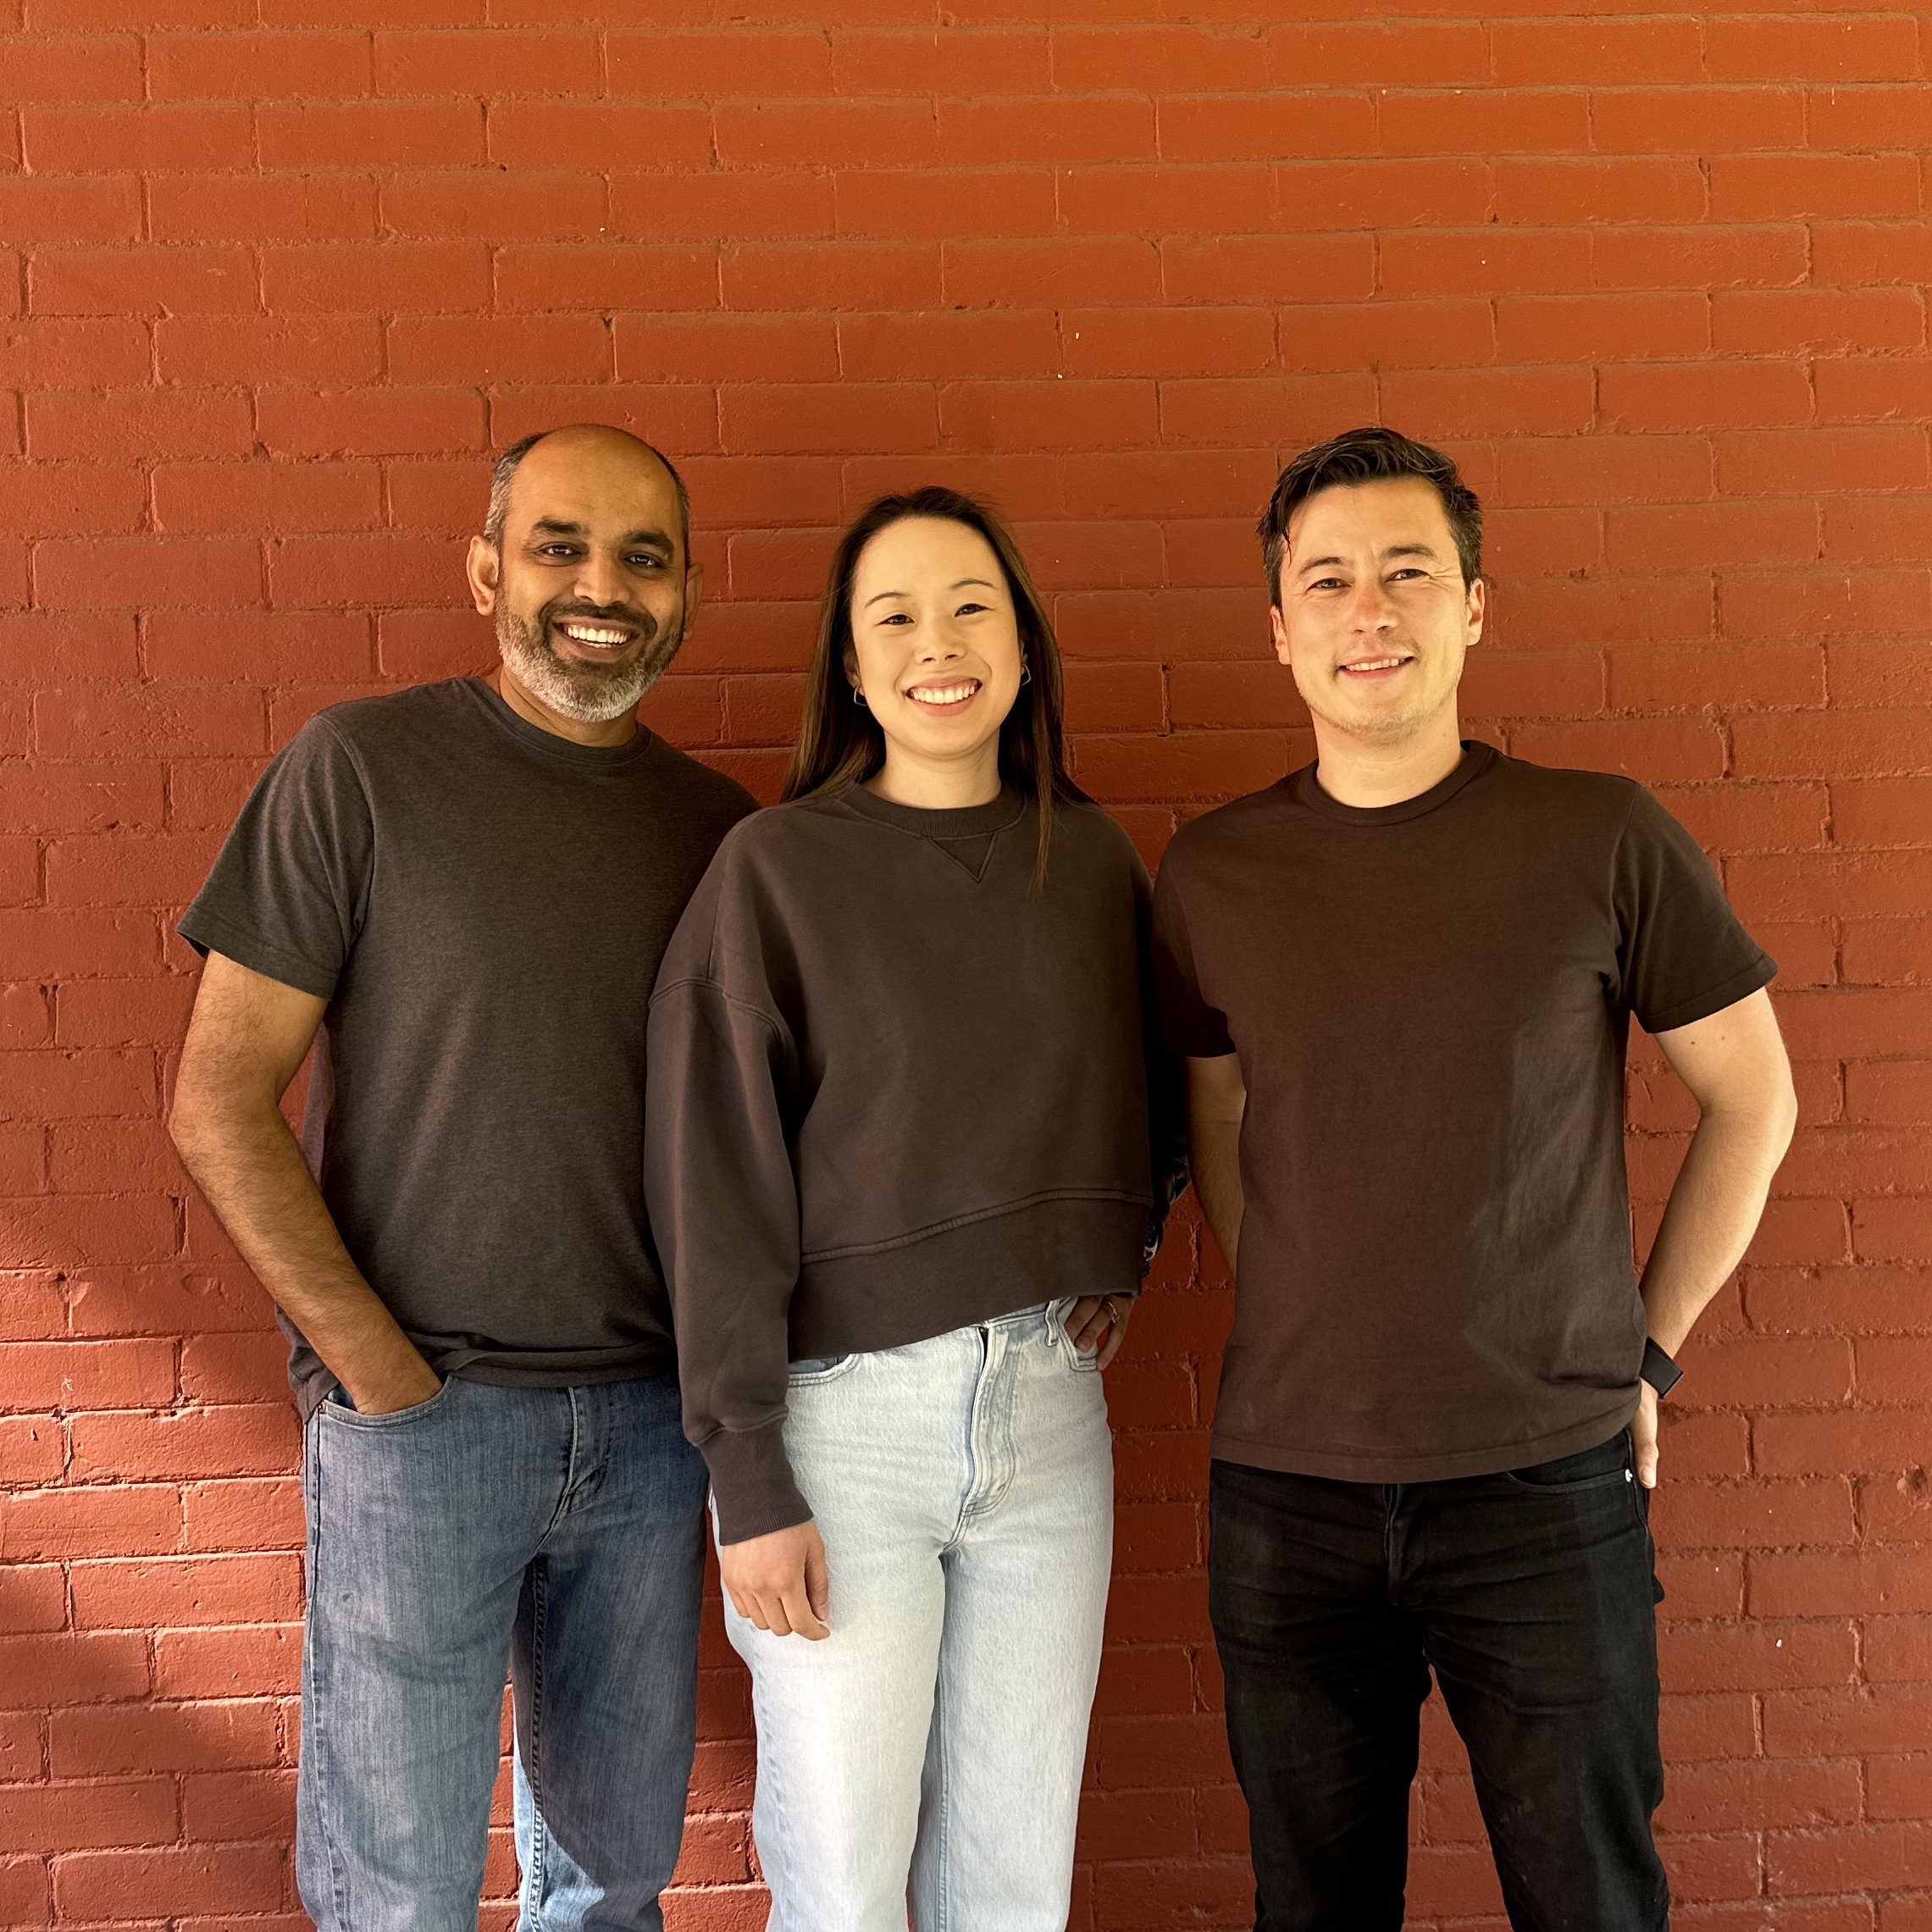
Jessica co-founded Uprise in 2021. Chris Goodmacher brought experience from Justworks; Nanthakumar Muthusamy joined the founding team with an engineering background. The company’s early public pitch concerned making financial planning available to people who had traditionally been outside the audience for private wealth services.
In 2022, Jessica announced a $1.4 million pre-seed round and a waitlist of more than 7,000 people. She thanked beta customers for spreading the product by word of mouth. That early audience was useful for more than proving that people might sign up. It gave the team people to listen to.
Small business owners repeatedly brought a particular complication: their business and personal finances had to be considered together. A decision made for a company affected the person who owned it. The boundary that divided providers and products could make the owner do the work of joining everything back up.
Jessica’s team followed those questions. In October 2024, she announced a $3.3 million seed round led by Blank Ventures and described Uprise’s embedded advisory offering for small business platforms. Partners included Fundera by NerdWallet, Heard and Carry. The company was moving toward customers through services they already used.
For Jessica, this meant working on two relationships at once: the relationship with the person seeking advice and the relationship with the platform delivering it. The company had to make sense in somebody else’s product. A founder’s own vision could only take the conversation so far.
- 2021-22Individual planningStart with wider access to financial guidance.
- 2024Business + personalBuild around the owner’s combined finances.
- 2025-26Tax + advisoryDeliver through existing platforms and relationships.
The stranger on the other side of the call
There is an amusing complication in this part of her story. Jessica has said she made career switches partly to avoid talking to strangers. “I don’t want to do sales,” she wrote, recalling an earlier preference. Founding eventually put sales and partnerships at the center of her working life.
The admission is more revealing than a polished claim to enjoy every aspect of entrepreneurship. A person can care deeply about the result and still dislike some of the activities needed to get there. Building a company forces those preferences into negotiation with the work.
In a January 2025 conversation about her career and Uprise, Jessica discussed learning through iteration, finding co-founders and the role of investors. The founder’s job keeps changing as the company learns. Tasks once treated as someone else’s specialty can become the next thing that needs doing.
Her HoneyBook launch offered a concrete example of partnership work. Jessica described spending months with photographers, consultants and coaches to understand their financial concerns, then developing an offering for that platform’s customers. The partnership was announced in December 2025. Tax filing and year-round guidance would sit alongside the tools those independent professionals used to run their businesses.
Jessica reported that every pilot user rated the experience 10 out of 10. It is a company-reported result from a pilot, rather than a score for all customers. Its place in her account is nevertheless clear: the early conversations helped shape a service people wanted enough to recommend expanding.
When tax moved to the center
By 2026, Jessica was describing Uprise as a tax firm for people with complicated earning arrangements, such as business ownership, property or stock compensation. Her argument concerns the space between straightforward filing software and expensive concierge service. People in that space still need someone who understands their circumstances.
She wrote that Uprise had worked through the previous tax season manually before building more of the platform. In May 2026, she reported 3.5 times year-over-year revenue growth after its first season at scale. The figures are her account of company performance; the sequence also shows her preference for learning the work before automating it.
The tax notice in her own life sits naturally beside that approach. Paperwork carries decisions already made, but the service around it has to understand the circumstances that produced those decisions. A return is a record. The person behind it is still making plans.
Jessica continues to argue for human involvement alongside AI. Her public discussions of the technology emphasize oversight and the need for customer context. An advisor can ask a follow-up question, hear an incomplete explanation and take responsibility for working through it. Those actions are part of what she is trying to preserve as the operation grows.
“You don’t get a sticker for how you did it.”Jessica Chen Riolfi
No sticker for the approved process
Founding has required another adjustment. Jessica says she has had to unlearn the assumption that there is a correct way to do everything. Education rewards following a process; a company eventually has to produce an outcome.
She has also written publicly about being a founder and a mother, and about finding company in the VC Backed Moms community through Bridgette Farrer Muir. Her account leaves room for both ambition and the value of time with family. The calendar, as ever, is less accommodating than the mission statement.
There are lighter details, too. Her Medium biography declares an enthusiasm for Broadway musicals. Her public profile lists English, Mandarin Chinese and Portuguese. These glimpses do not explain a business model, but they restore a person to the collection of roles, rounds and partnerships.
Jessica’s story is still being revised by the work. She began with an example of advice she trusted, built financial products, and found herself responsible for a company serving people whose questions crossed familiar boundaries. Now tax sits near the center. The next decision belongs to a customer with a life to run and paperwork to finish. She wants useful help to be there when it arrives.