Juan Jurado-Blanco had done the work. He had earned a couple of hundred dollars in restaurant tips. He also had a credit card bill due. The paycheck would arrive in another week. Those three facts could coexist quite peacefully in a payroll system. In a worker’s bank account, they were rather less compatible.
The encounter with that delay became part of the origin of Clockout, the company he co-founded and now leads. Its subject is earned wage access: letting people obtain a portion of pay they have already earned before the scheduled payday. Jurado-Blanco’s route into the business began with the experience of waiting. His route through it has involved changing who provides the service, who repays the money, and whose name appears on the screen.
There is something faintly comic about the calendar’s authority here. A restaurant shift can be over; a bill can be ready; the earnings must observe office hours. Jurado-Blanco took that ordinary inconvenience seriously enough to build around it. The resulting story stretches from South Florida workplaces to Chattanooga and meetings with banks and credit unions. The question at its center is still small enough to fit on a restaurant receipt.
The price of getting paid sooner
One conversation supplied a particularly sharp version of the problem. A restaurant co-worker told Jurado-Blanco she would sacrifice 20 percent of her tips if she could receive them immediately. That was a price she was willing to pay for timing. For someone considering a business, it was also an unusually direct statement of demand.
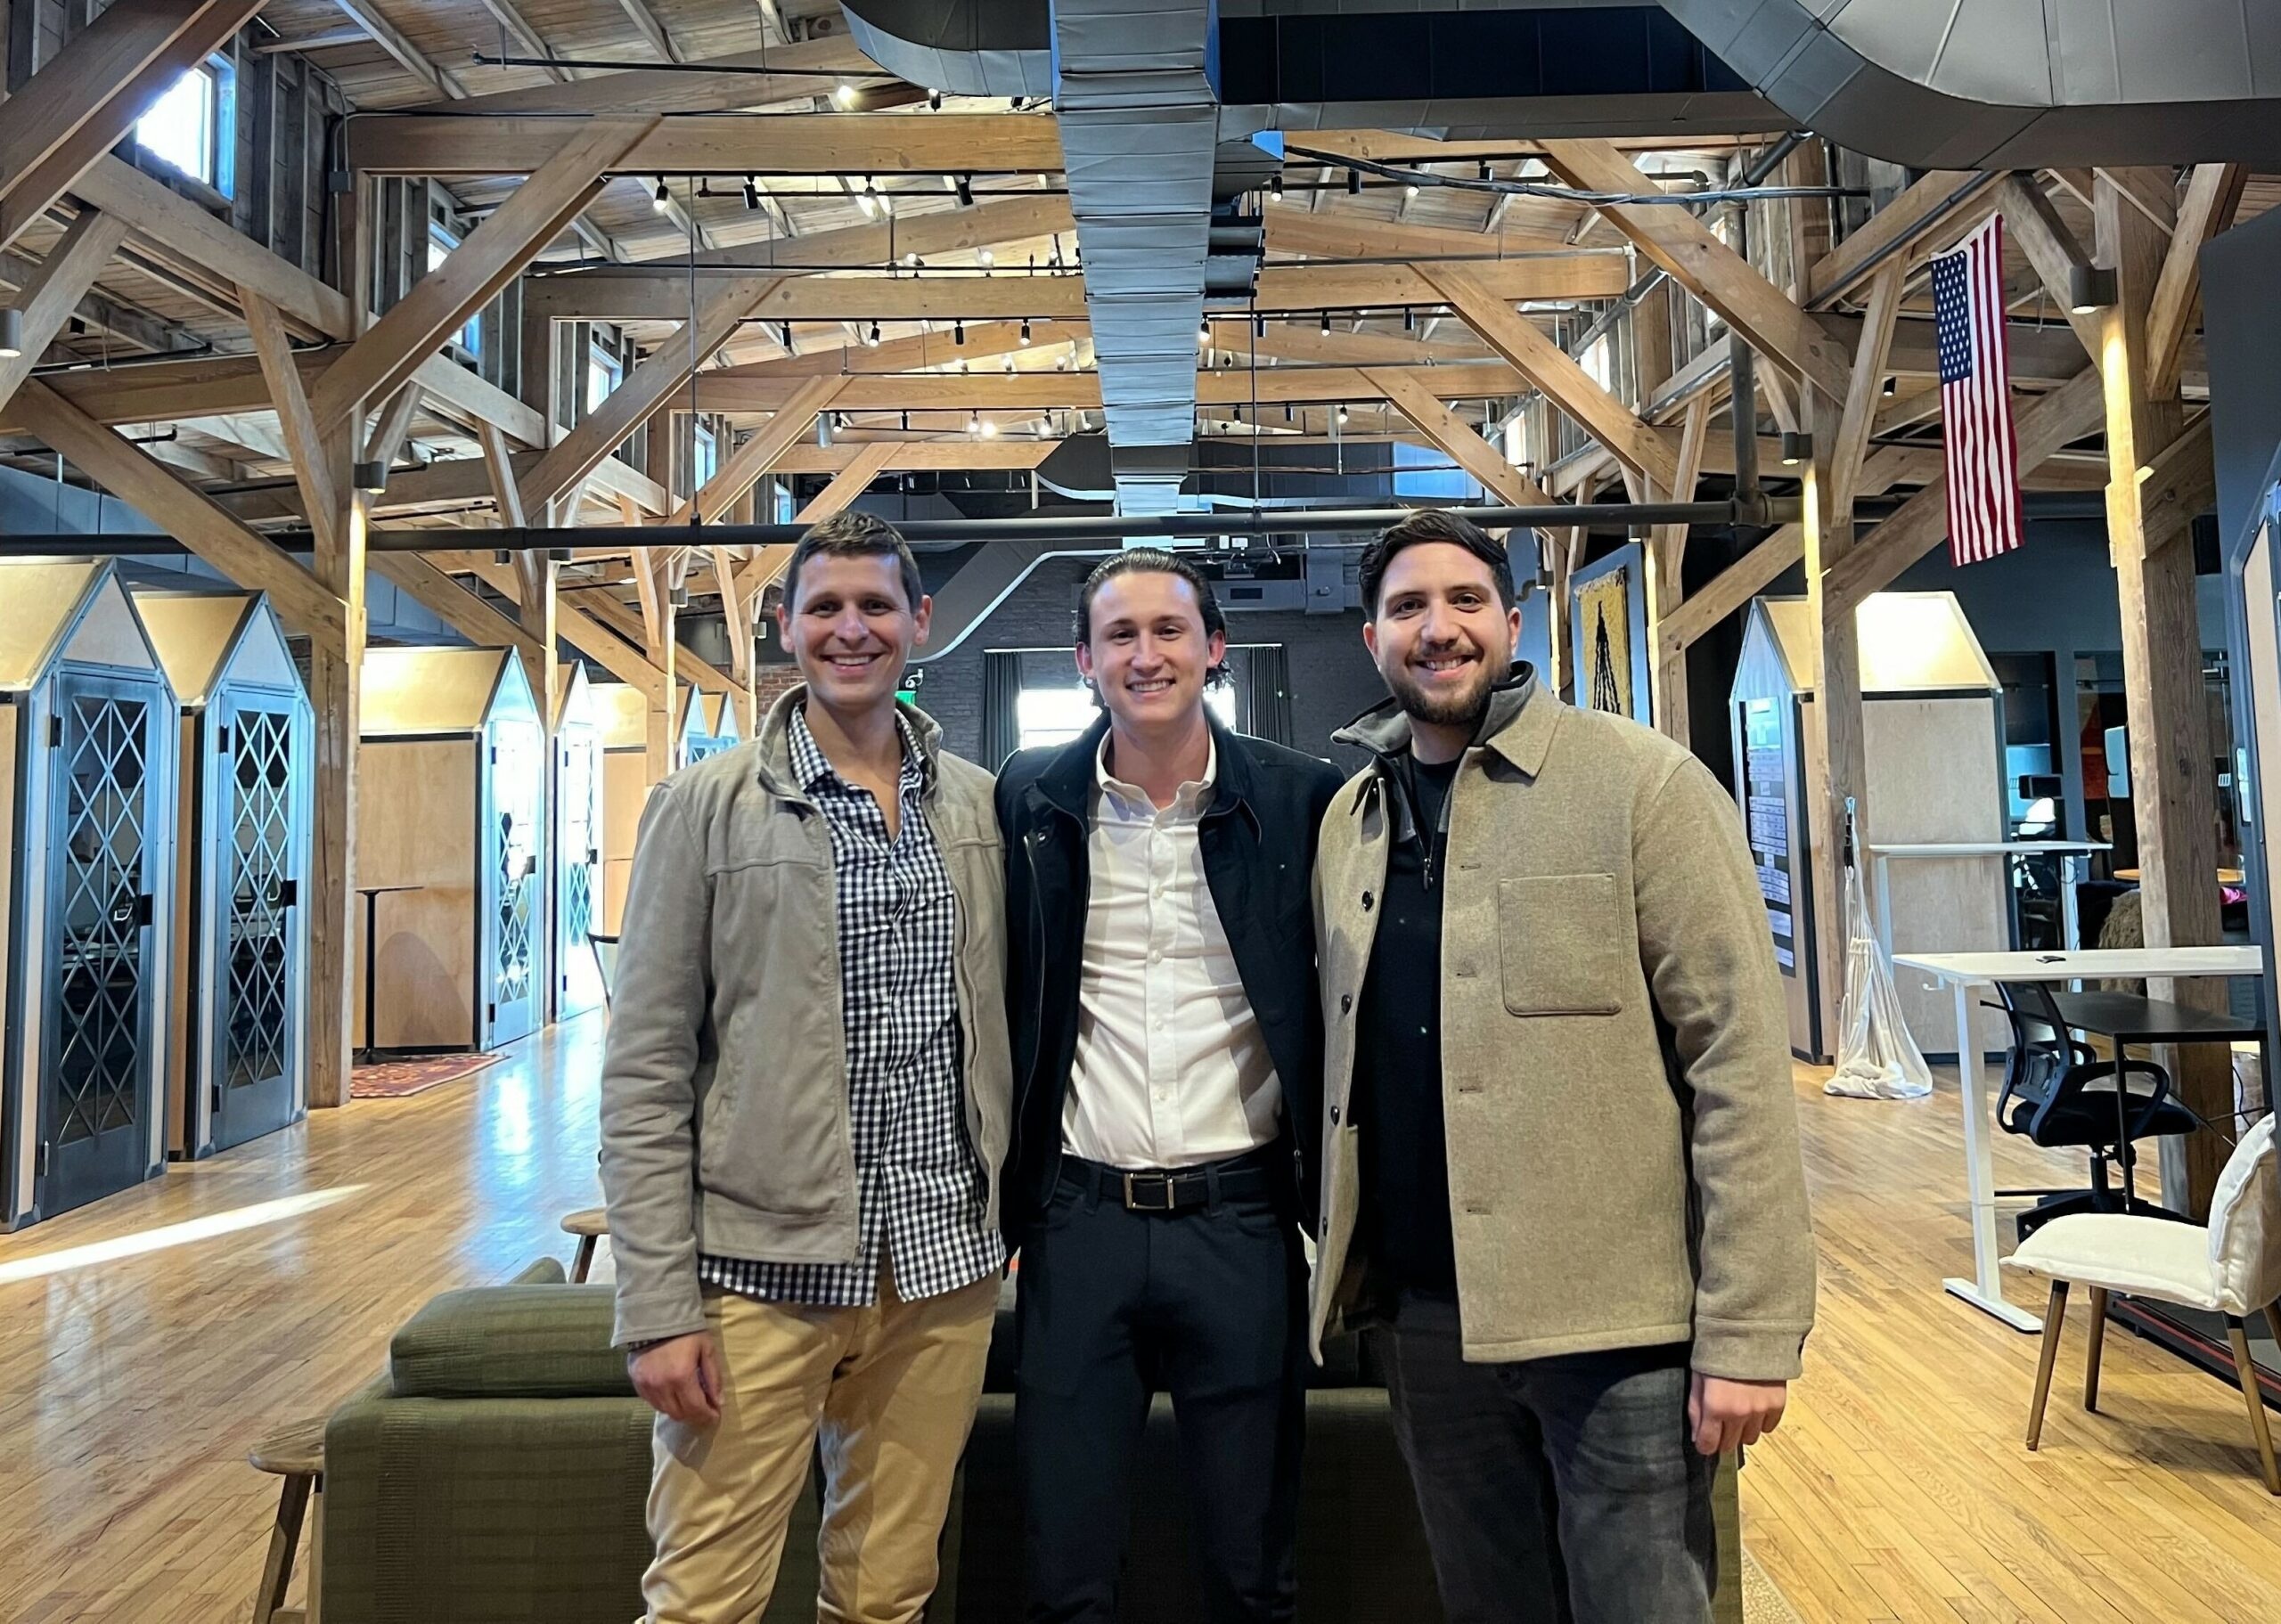
He teamed up with Anthony Tardugno, a childhood friend from Venezuela. Their early plans included giving workers a way to receive earnings and send money to family abroad. The first reported workplace customer was Carmela Coffee in east Boca Raton. Eight of its ten employees were already using the platform when the company’s early progress was described in November 2022.
That little coffee-shop number gives the beginning a useful scale. A service introduced to ten people can be discussed in terms of actual participation. The founder has somewhere to start asking what works, what takes too long, and what someone will use again after the first demonstration. A large market estimate cannot supply those answers on its own.
The co-worker’s proposed sacrifice also puts an uncomfortable question beneath the product: how much should speed cost? A person can value immediate access highly without wanting to surrender a substantial part of the earnings. Building a workable service means attending to both halves of that sentence. The delay creates demand; the price determines what kind of answer the company is offering.
A friendship with a payments habit
Clockout was not Jurado-Blanco and Tardugno’s first attempt at a payments business. They had worked on Walla Payments, conceived as a multicurrency version of Venmo. The shared interest was already there: moving money between people and places with less difficulty. Clockout gave that interest a more specific setting, the interval between a shift and a paycheck.
In 2022, they also participated in Techstars’ Farm to Fork accelerator, focused on the future of food and agriculture. A company concerned with restaurant workers’ earnings had a concrete connection to that world. The restaurant supplied more than an origin anecdote. It supplied the first environment in which the service had to make sense.
Jurado-Blanco’s public background has other practical details. His LinkedIn profile lists University of Florida attendance from 2021 to 2024. It also describes a summer 2016 volunteering program involving landscape maintenance and trail work at preserves near Gainesville. His language listings include English and Spanish at native or bilingual proficiency, with elementary Chinese.
Those details give him a life beyond the pitch without requiring a grand theory of his character. He describes himself as an ambitious entrepreneur and problem-solver. The work of a founder tests such descriptions in less elegant language: another integration, another conversation, another version of a process that seemed simple until someone actually tried to use it.
The first change happened behind the counter
Clockout’s early arrangement required employers to repay the funds advanced to workers. By October 2023, it had changed that arrangement so the employee repaid Clockout automatically when paid. Jurado-Blanco explained that the previous approach had created friction with larger employers, involving compliance and operational work and extending sales cycles.
This was a change in the machinery behind the service. For a worker, the attraction was earlier access to earnings. For an employer, introducing that benefit could entail additional work. Jurado-Blanco’s team had to deal with both experiences. A willing employee does not complete an employer’s implementation.
At that point, Clockout reported having advanced $130,000 since its January launch and being in the process of onboarding 1,400 employees from 20 partner employers. Those are historical snapshots, attached to the earlier workplace model. They show a company already putting money through its system while still altering how that system operated.
A founder’s attachment to an idea becomes visible in these adjustments. The starting problem can remain compelling even when the initial method is cumbersome. Here, the team removed a repayment obligation from the employer rather than asking enthusiasm for the benefit to carry the extra administrative burden. The change addressed a specific obstacle that Jurado-Blanco could describe.
The earned-pay question stayed at the center. The place people encountered the service moved.
The idea inside an app he already used
A later change concerned distribution itself. Jurado-Blanco has described using Zelle and wondering what would happen if banks and credit unions offered wage access. The thought was practical: the institution already had a relationship with the account holder and a digital place where that person managed money.
By February 2025, Clockout was presenting this banking approach. Customers would connect payroll through their institution’s digital platform, with direct deposit part of the setup. The employer would no longer have to introduce the product. Clockout was moving closer to the account where the wages would ultimately arrive.
That also changed the founder’s audience. An employer might assess wage access as an employee benefit. A bank could assess it alongside deposits, customer engagement, and its other digital services. The worker’s timing problem was being translated into a proposition for a different organization, with different reasons to say yes.
The institution’s app offers a familiar entrance. Familiarity alone cannot establish that a product will succeed, but it changes what the customer is asked to do. The company’s banking approach places wage access beside existing account activity. The founder’s task becomes making the underlying connection work while the institution manages its customer relationship.
“Our brand is not there, right?”
Juan Jurado-Blanco, discussing Clockout’s white-label product in 2026
Letting someone else’s name take the screen
Clockout’s white-label approach gives the bank or credit union the visible identity. Jurado-Blanco has explained that an institution can choose the product’s name and presentation. That is a particular sort of founder’s bargain: build the technology, then let the customer’s institution introduce it as its own service.
The controls reflect that arrangement. Clockout’s current product materials describe institutional settings for pricing and advance limits, along with an administrative dashboard. Its public demonstration describes repayment when the paycheck is deposited. Each piece belongs to the work of operating the service after the attractive idea has been approved.
For Jurado-Blanco, this makes the business less dependent on winning a separate place on someone’s phone. It makes relationships with banking technology providers more consequential. Clockout’s industry profiles list partners including Q2, Jack Henry, Alkami, and Candescent. Such connections form the route into existing digital banking systems.
The invisible parts deserve attention precisely because customers are unlikely to admire them. People generally open a banking app to accomplish something. An infrastructure company earns its place by helping that action happen. There is little theatrical glory in a repayment process that runs as intended, which is probably how the customer would prefer it.
Capital, colleagues, and a room full of bankers
In June 2025, Clockout announced a $2 million seed round led by Cofounders Capital. Participants included Brickyard VC, Market Square Ventures, LaunchTN, OneSixOne Ventures, and Erez Capital. The company said the investment would support product development, partnerships, and team expansion.
The financing widened the circle around the childhood friends’ business. It also put resources behind a model requiring cooperation with financial institutions. Those partnerships demand more than a good account of the original problem. They require people and software capable of carrying the proposition into an institution’s daily operations.
That summer, ICBA recognized Jurado-Blanco, Vladimir Dumitrean, and Tardugno with its ThinkTECH All-Heart award, sponsored by Wipfli. The recognition concerned passion, empathy, and commitment to making a positive impact. It arrived through an accelerator devoted to community banking, placing the founder team in the industry they were now trying to serve.
Jurado-Blanco subsequently appeared with chief revenue officer Armando Quintana in banking interviews and was listed as Clockout’s presenter at FinovateFall in September 2026. The event’s company profile reported a team of ten and $3 million raised to date. These are company-reported figures, a dated view of the operation rather than a measure of its founder’s personal wealth.
The week is still the point
The public pitch has accumulated the vocabulary of banking infrastructure. Jurado-Blanco now speaks to organizations that must consider integrations, administration, deposits, and customer relationships. The restaurant story remains useful because it keeps the purpose of those conversations understandable.
A worker’s earnings and a bill’s due date can sit on opposite sides of a scheduled payday. Clockout’s proposition is to give financial institutions a way to address that interval. Whether the service reaches someone through a workplace or a bank affects the business behind it. The original experience supplies the reason to keep working on the arrangement.
Jurado-Blanco’s path contains several revisions of the answer. He and his colleagues changed repayment, changed distribution, and made room for another institution’s brand. The consistency sits in the question he brought out of his restaurant work. The shift was finished. The money had been earned. Why should another week have the final say?