The kitchen floor was sticky. Outside, golfers were thirsty. Somewhere between those two conditions, a boy in Oak Brook, Illinois, had discovered a business. James Brickman mixed powdered lemonade, enlisted his twin sister and a neighbor, and carried a table and folding chairs out toward the seventh hole at Midwest Country Club. The stand lacked permission. Its customers lacked a convenient alternative. It was a small enterprise with an unusually clear understanding of location.
Years later, Brickman remembered correcting his neighbor’s sales pitch: ice cold, rather than nice cold. Even a lemonade operation, apparently, required supervision. He recalled charging about a quarter a cup and taking roughly $30 a day with tips. “I’ve always been a saver,” he said. The joke was that he might still have the proceeds.
The boy eventually became the co-founder of a public homebuilder. The sticky floor disappeared from the business model. The questions about where to sell, what to charge, and when to hold onto money remained.
A retirement with an early checkout
Brickman earned both his BBA and MBA at Southern Methodist University. By 1976, he was working as a building superintendent in Dallas, an occupation he later enjoyed setting beside his graduate education in finance. It is an appealing combination: one part spreadsheet, one part finding out what actually happens on a construction site.
His work spread across offices, apartments, condominiums, single-family houses, land entitlements and property management. At Princeton Homes and Princeton Realty, he served as chairman and chief executive. He had experience with buildings that would be sold, buildings that would be rented, and the money required to get either kind out of the ground.
He also had a deadline for himself. He wanted to retire from homebuilding by 50. In 2000, at 48, he managed it. In the account he later gave, satisfaction did not survive the achievement for very long. He quickly became bored.
Retirement had removed the work without removing his interest in it. He began buying distressed debt and making other real estate investments. A creditors’ committee introduced another kind of problem to investigate. The career that followed would use both the construction experience and the appetite for financial detail he had carried away from it.
“Nothing substitutes for effort.”
James Brickman, on advice to his younger self, 2019
The Green, the Brick, and the bad timing that helped
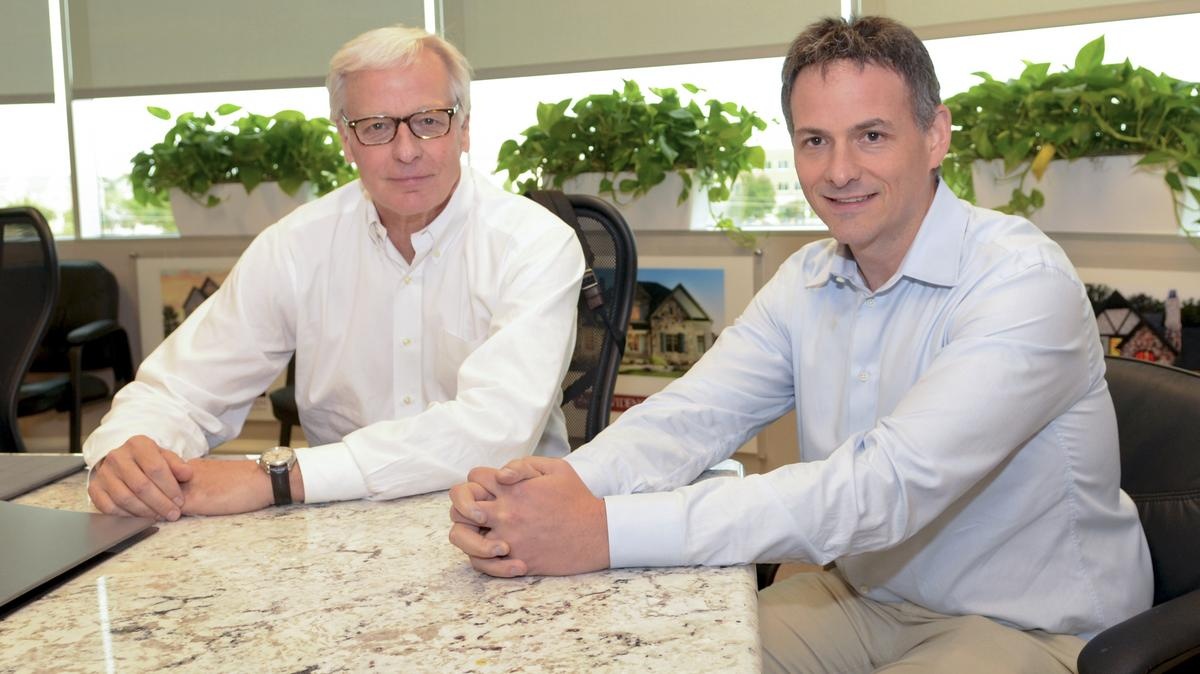
In 2002, Brickman began working with David Einhorn on research into a financial company. They became collaborators and friends before becoming partners in the housing business. Their eventual company name retains a small record of the relationship: Green comes from Greenlight Capital, Einhorn’s investment firm; Brick comes from Brickman. A branding committee could have made considerably more work of it.
Then housing collapsed. In 2008, the two started the real estate equity fund JBGL. Brickman became its founding manager and advisor. Its work included purchasing lots and lending to distressed builders at a time when conventional financing was hard to obtain.
The sequence matters. An empty lot can look like a liability to a lender trying to reduce exposure and like inventory to a developer who knows the local market. Neither view removes the risk. They imply different timetables, resources and obligations. Brickman’s years in development gave him a way to examine opportunities beyond the distressed price.
In 2014, JBGL entered the public markets through a reverse recapitalization, becoming Green Brick Partners. Brickman became a director that October. The public company gave his second act another source of capital and a new set of administrative demands. A former retiree now had shareholders waiting for quarterly reports. There are quieter ways to keep busy.
A neighborhood runs on a different clock
At Green Brick, his responsibilities have included major investment decisions, capital allocation, strategy and relationships with the company’s builders. Those duties place him at the junction of two businesses that buyers often experience as one: making a lot ready for a house and building the house that will occupy it.
Green Brick buys land and develops much of its own lot supply. Its builders serve different buyers through brands including Trophy Signature Homes, CB JENI, Normandy, Southgate, Centre Living, The Providence Group and GHO. The organization can bring shared capital to those businesses while retaining their distinct products and local knowledge.
Owning land has consequences. Money goes into the ground before it returns through a closing. Roads and utilities have to arrive before a neighborhood can function. The reward for getting the decisions right may come years after the purchase; the cost of getting them wrong can arrive rather sooner.
Brickman has made that long view explicit. Speaking in September 2026, he described community development horizons of eight or ten years, sometimes longer. Pools, landscaping and entrances belong within that calculation. They help establish the place a buyer will inhabit after the model-home visit is over.
- 01AcquireCommit capital to the location.
- 02DevelopTurn land into buildable lots.
- 03BuildMatch a home to its buyer.
The scale changed substantially during his first public-company decade. Green Brick delivered 655 homes in 2015 and 3,783 in 2024. Its 2024 shareholder letter placed land development at the center of its explanation for that growth. The claim carries a practical test: can the company keep choosing and developing locations that buyers will want, at prices that leave room for a return?
There is a revealing companion to that preference for patience. In their 2022 shareholder letter, Brickman and Einhorn explained that the company did not provide earnings guidance because they considered pressure to meet short-term expectations a poor way to run a long-term business. That choice leaves investors to judge actual results and the decisions behind them. A long horizon still needs an accounting.
The floor plan gets personal
Brickman’s interest in houses also has a domestic address. In a 2015 interview, he described helping design neighboring homes for himself and his daughter in Highland Park. The houses opened onto a shared backyard, giving him a place to spend time with his grandchildren. Here was a land-use decision with unusually familiar end users.
He explained that designing homes invites a builder to consider how he would live in the space, even when the future resident will be somebody else. That observation connects the investment work to a less abstract question: where will people actually put their lives?
His public recollections include room for modesty. He plays piano and rates his own ability poorly. During college travels through Europe, he once intended to reach Rome by train, fell asleep, and woke in Naples. Someone who would spend decades studying locations had, on that occasion, delegated navigation to a timetable and a nap.
Asked how he motivates people, he answered, “Hopefully by example, more than words.” It is a useful standard for someone whose responsibilities include choosing partners and entrusting them with capital. His stated preference gives colleagues something concrete to assess: what he does when a decision becomes difficult.
The buyer still has a monthly payment
A development horizon measured in years does not make the immediate market disappear. Green Brick’s second quarter of 2026 showed both demand and the expense of keeping it moving. Net new orders rose 19% from a year earlier. Incentives on new orders remained at 9%.
The company delivered 1,047 homes and produced $471 million in home closing revenue. It also delivered its first homes in Houston. Growth was continuing, with affordability and economic uncertainty still part of the conversation.
Those figures put a limit on the romance of patience. A buyer signs on the basis of a household budget. A builder may love a location and still need an incentive to close the sale. The long-term land decision and the short-term payment calculation have to meet at a price both sides can accept.
Making room for the next builder
In his September 2026 NYSE interview, Brickman described the ingredients behind the business as “capital and people.” He talked about experienced leaders who could execute complicated developments. It was a concise description of the work he had been assembling since returning from retirement.
On October 15, Jed Dolson became co-chief executive alongside him, following an announcement framed as part of long-term succession planning. Dolson had joined in 2013 as head of land acquisition and development, then moved through regional leadership and operating roles. The shared title followed years of responsibility within the same business.
There is a consistency in that choice. The company’s next phase includes someone who knows the ground as well as the organization above it. Brickman remains co-founder, co-CEO and director. His second act has reached the point where building a company also means deciding how its experience carries forward.
The lemonade stand depended on being in the right place when a customer needed a drink. A residential community asks much more of its builder: capital, infrastructure, judgment, and years of work before the last house is sold. Brickman’s career has enlarged the question he first encountered beside the golf course. He is still occupied with what makes a location worth investing in, and what it takes to stay long enough to find out.