The revealing moment in Ivan Soto-Wright’s story comes when he discusses the company that bought his first startup. Plum had been a competitor to Saveable, his automated savings business. Asked why the other company had done better, he offered an unusually economical explanation for a founder: “They, they executed better than me.”
There is room for a whole business education in that sentence. Financial expertise, a useful idea and the determination to start a company had carried him some distance. Persuading people to use what he had built proved a separate occupation. His next business, MoonPay, would make the act of getting started its principal product.
It would also make him conspicuous. There would be celebrity investors, expensive digital collectibles and a Miami life that bore little resemblance to his early career advising pension funds. Behind the photographs sits a persistent commercial question: how much trouble will someone tolerate before deciding that the financial future can wait until tomorrow?
The competitor who did it better
Soto-Wright’s route into finance began with economics at The George Washington University, where he graduated Phi Beta Kappa with Special Honors. He also studied Philosophy, Politics and Economics at Oxford. The combination put questions about money alongside questions about institutions and who gets to participate in them.
He is American, with a Canadian mother and a Venezuelan father. His working life took him to London and Redington, the investment advisory firm. There, his subject was the architecture of large portfolios: strategic asset allocation and portfolio construction for pension funds and insurers. The sums were institutional; the eventual beneficiaries were people saving for a distant future.
Saveable brought the problem closer to the individual. Starting in 2015, he tried to automate the movement of money into savings. Plum acquired the business in 2018. His subsequent account of the experience was candid about execution and distribution. Knowing what people ought to do with their money had not made getting them to do it straightforward.
That earlier venture gives the MoonPay story a useful beginning. Saving requires someone to postpone a purchase. Crypto attracts someone who already wants to make one. A service that helps an existing intention become a completed transaction begins with a different kind of customer energy.
A button with expensive plumbing
MoonPay launched in 2019. Soto-Wright and his fellow founders built a way to purchase cryptocurrency using familiar payment methods. A customer could arrive through another company’s website or wallet and use the financial tools they already recognized. The interface could be small. The arrangements behind it required considerably more work.
The buy-crypto button at Bitcoin.com became part of the company’s origin story. A website could supply the audience; MoonPay could handle the purchasing step. Rather than requiring every wallet or digital asset business to reproduce the same payment machinery, the company offered infrastructure they could incorporate into their own products.
For Soto-Wright, that arrangement gave the distribution problem a practical answer. Customers were already gathering elsewhere. MoonPay could meet them at the moment of purchase. It is easier to explain a new financial service when someone is actively looking for the thing it enables.
By November 2021, the business had raised a $555 million Series A, led by Tiger Global and Coatue, at a $3.4 billion post-money valuation. Those are financing figures from that moment, rather than a running estimate of either the company’s value or its founder’s wealth. They marked a change in the scale of the undertaking.
November 2021
at that financing
The earlier identity still mattered to him. He later described sleeping on a tatami mat during his London years to economize on rent. “I came from that bootstrapper mindset,” he said. The anecdote is an interesting companion to the funding announcement: a founder’s preferred account of himself can remain thrifty after the numbers become rather less modest.
When the customers had fan clubs
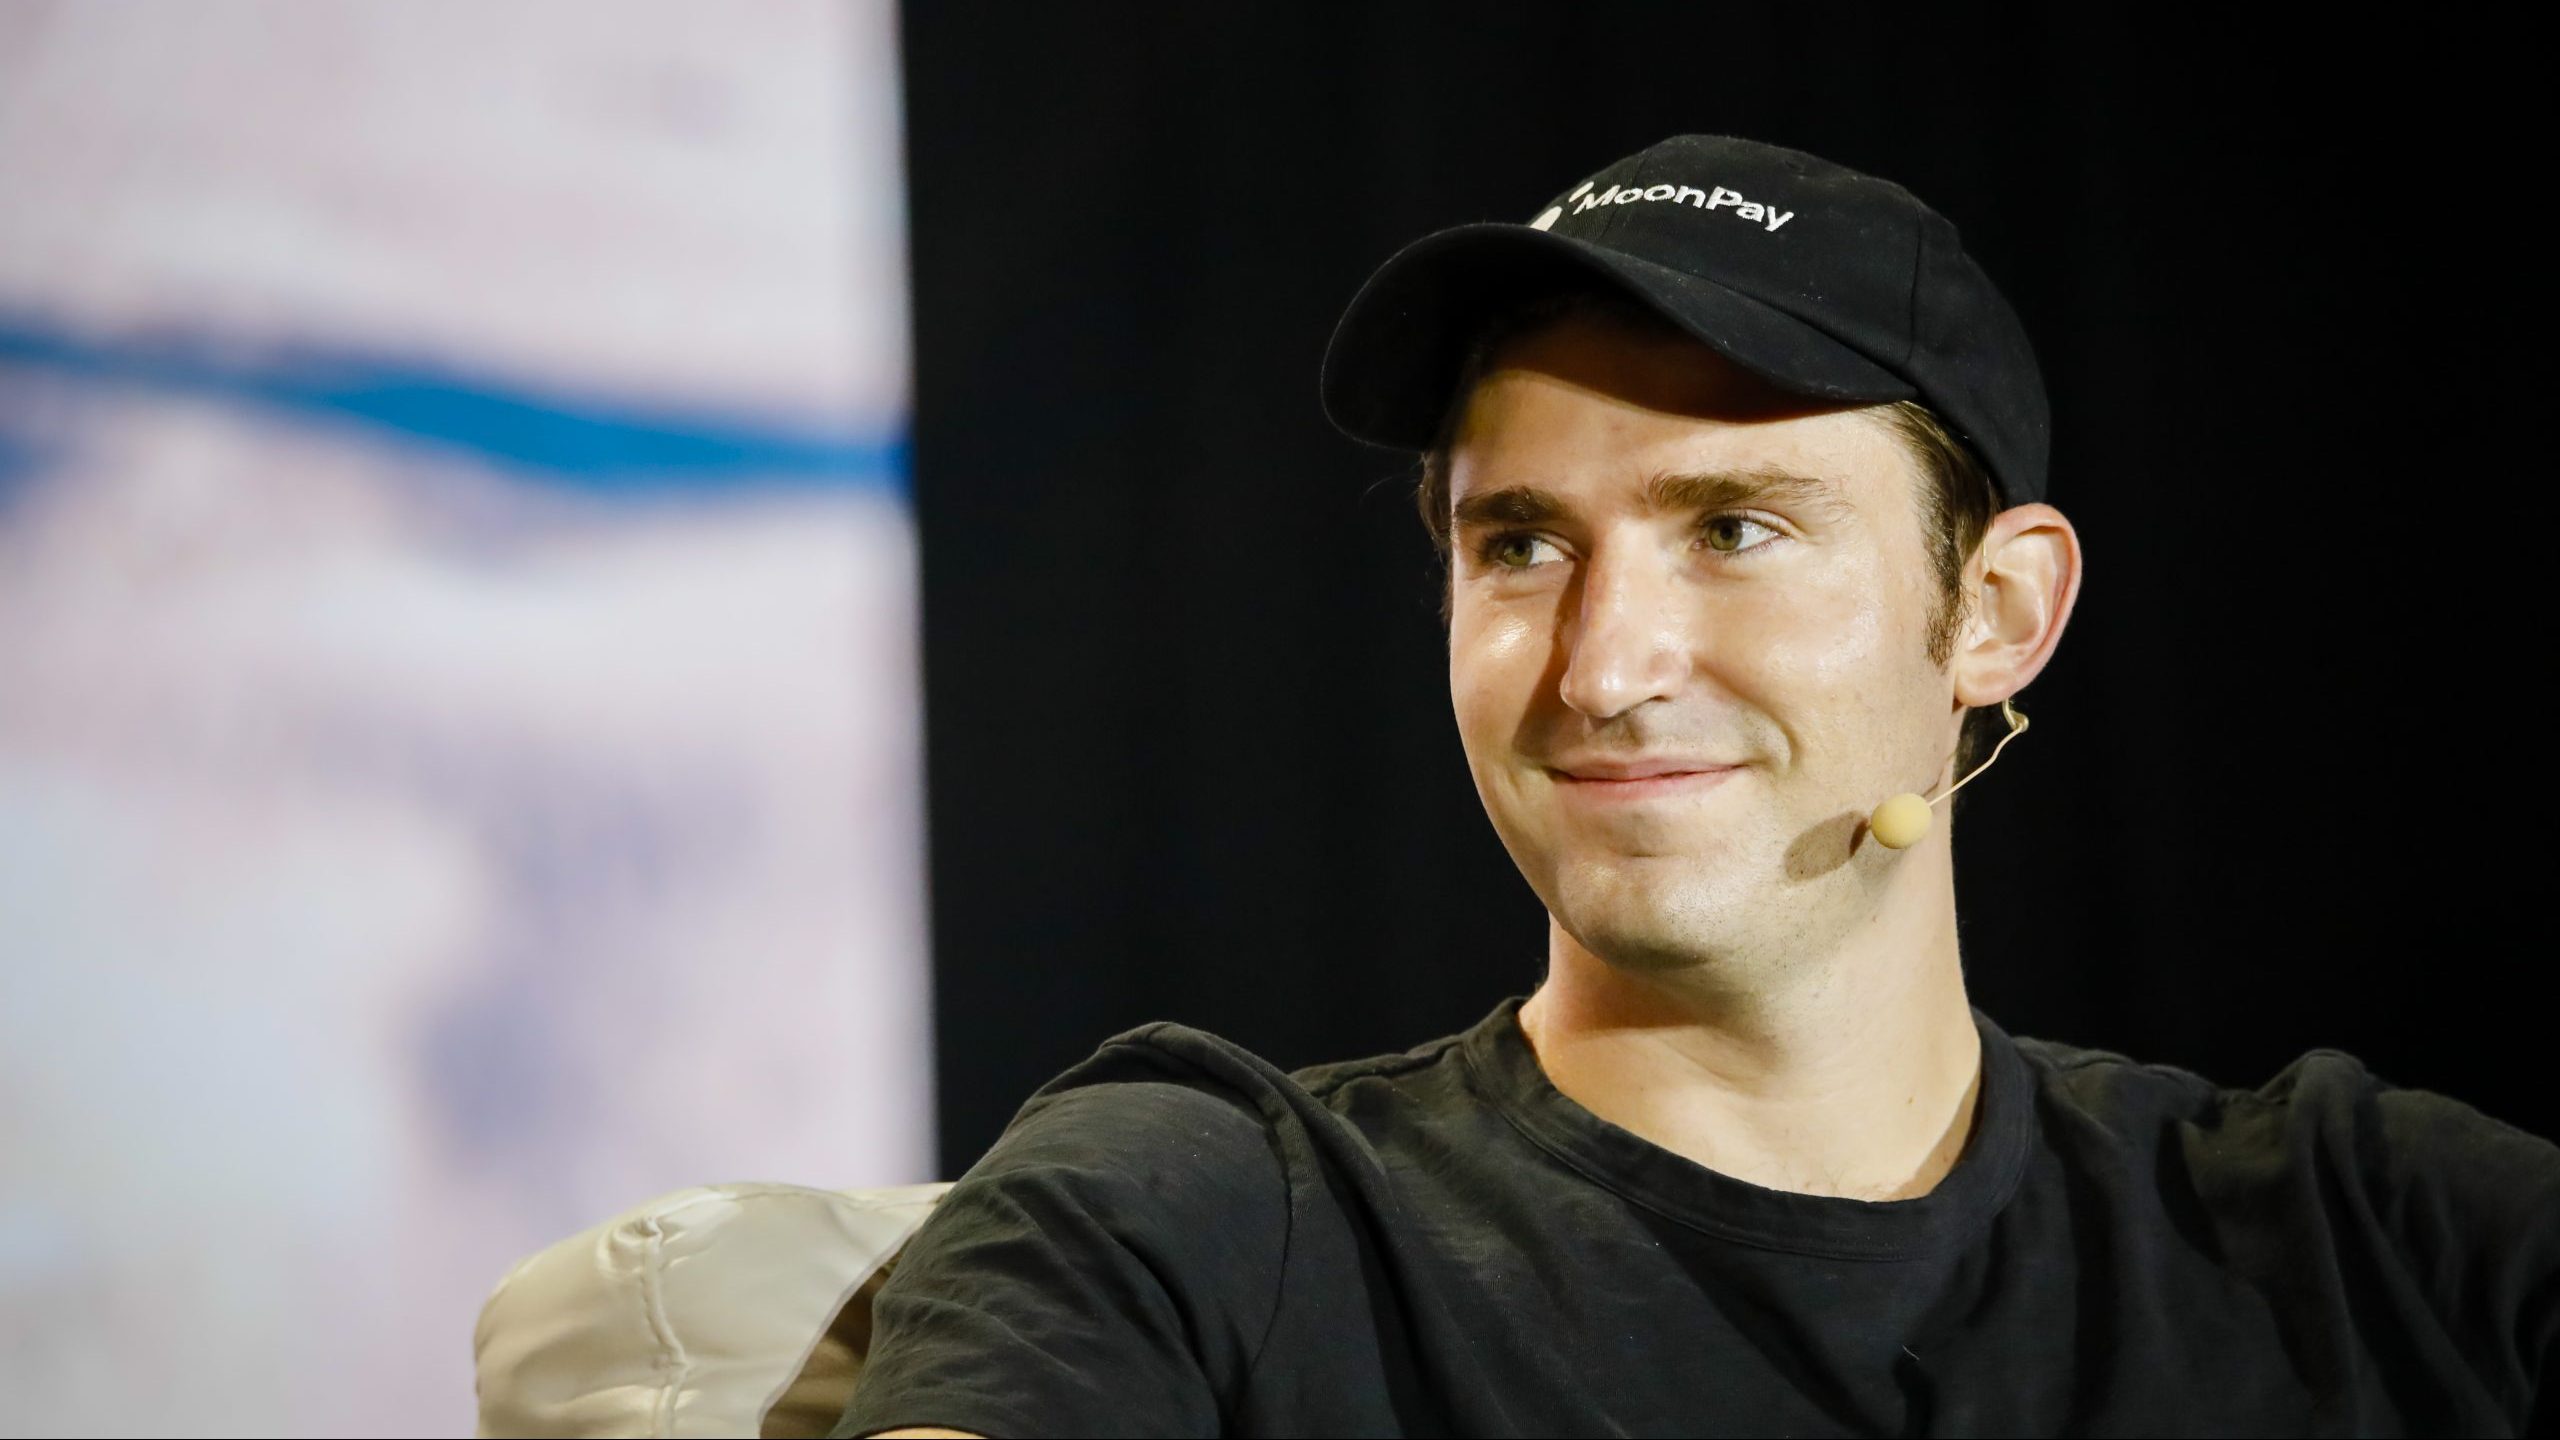
In April 2022, MoonPay disclosed that more than 60 figures and organizations across entertainment, sports and media had invested $87 million. The roster included Justin Bieber, Snoop Dogg and Maria Sharapova. That investment formed part of the $555 million Series A. Adding the two together would produce a more exciting number and a less accurate account.
The connections were part of a deliberate commercial ambition. Artists and athletes had audiences; audiences might want digital collectibles, access or new ways to support creative work. MoonPay wanted a role in the transaction. Its NFT Checkout product offered card purchases, while its concierge service helped high-profile customers buy NFTs.
Soto-Wright’s reasoning extended beyond payments. He wanted the brand to “permeate culture.” A transaction processor is rarely the principal attraction in a room full of musicians. Attaching it to the objects and experiences people want can change how often they encounter it, and whether they remember its name.
He participated personally, collecting NFTs through an account called ivanhodl. In March 2022, he said he intended to dedicate the collection and profits from its sales to charitable causes. That was an announced intention, with no fixed completion schedule. The distinction matters when a public promise is also part of a company’s cultural moment.
“I came from that bootstrapper mindset.”
Ivan Soto-Wright, reflecting on his early career
The strategy also gave the company a particularly visible test. Attention can introduce a financial product. Continued use requires a reason to return. As crypto markets faltered in 2022, the celebrity photographs could not settle the larger question of how durable the underlying demand would become.
The money has somewhere to go
The next phase is easier to follow through two acquisitions. In January 2025, MoonPay bought Helio in an all-equity deal valued at $175 million. Helio supplied crypto payment services for merchants and creators. Its work extended the company’s role from helping someone acquire a digital asset to helping a seller accept one.
In March came Iron, a stablecoin infrastructure platform. The acquisition added tools for business payments, treasury management and moving money across borders. For a founder associated with digital collectibles, this was a change of emphasis toward the less photogenic business of making funds arrive where they were supposed to.
A stablecoin is designed to track a reference asset, often a currency. The commercial proposition here concerns movement: collecting money, converting it, sending it and making it available to the recipient. Those are familiar financial jobs, even when the technology used to perform them is newer.
- 01BuyFamiliar payment methods
to digital assets - 02AcceptMerchant checkout
Helio · 2025 - 03MoveBusiness payment tools
Iron · 2025
A May 2025 Mastercard partnership set out a further connection: cards linked to stablecoin balances, with conversion to ordinary currency when spent. The stated opportunity involved Mastercard’s acceptance network. It described the reach of the proposed payment connection, rather than proving that every merchant had independently adopted a new crypto product.
MoonPay Enterprise followed in August 2026, built on Iron. Its purpose was to bring business stablecoin infrastructure into a unified offering. A finance team does not necessarily want to assemble several specialist providers just to complete one payment. Soto-Wright’s expanding company was increasingly selling the prospect of fewer separate arrangements.
Back among the institutions
By September 2026, MoonPay had signed a definitive agreement to acquire North Capital, a private-markets infrastructure business. Completion remained subject to regulatory approvals and other closing conditions. The announcement pointed toward securities brokerage, investment advisory capabilities, custody and secondary trading, including support for tokenized securities.
The trajectory has an almost circular quality. Soto-Wright began by advising institutions on portfolios. He moved toward consumer savings, then crypto purchases, digital collectibles and business payments. Now the company he leads is seeking infrastructure for capital markets. The institutions have returned to the picture, equipped with different software.
MoonPay said in that September announcement that it served more than 35 million customers in 180 countries and more than 1,500 enterprise clients. Those were company-reported figures. They give a sense of the scale at which the original purchasing problem now sits, without answering every question about how the newer businesses will perform.
A larger collection of capabilities also asks more of a founder. Payments, commerce and securities each have their own customers and operating demands. Connecting them commercially is harder than putting them beside one another in an announcement. Soto-Wright’s task is increasingly to make the company’s expanded scope useful to the people actually using it.
A different sort of stage
There is another way to measure the distance he has traveled. As a teenager in Boston, Soto-Wright participated in Junior Achievement. In April 2026, he delivered a keynote at its Greater Miami company competition. That year’s program involved 2,054 students across 20 schools, creating 70 student-run businesses.
The setting brings entrepreneurship back to a manageable scale: finding a customer, building something to sell and working with other people. His family foundation supports mentorship and educational opportunity. Adrianna and Natalie Soto-Wright serve as directors. The founder’s story becomes part of a family effort to give young people an early encounter with building a business.
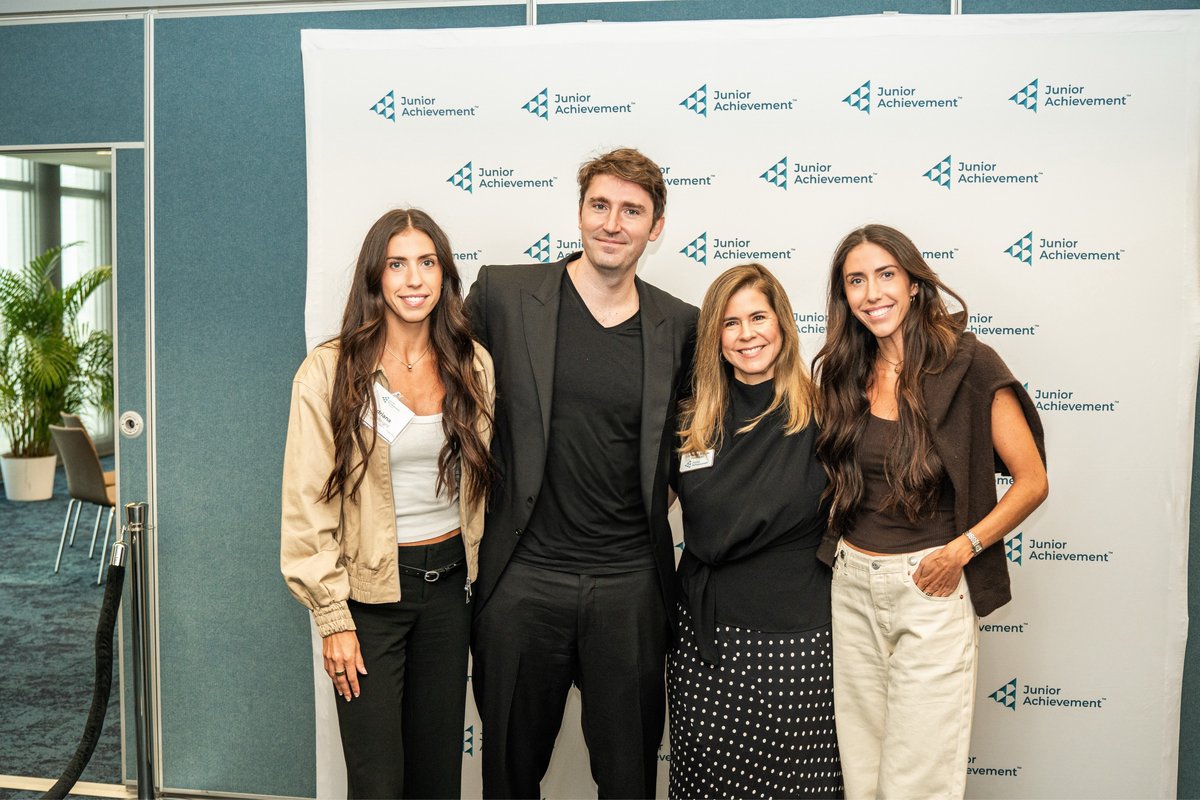
For those students, the useful part of his experience may be the unsuccessful beginning. A sale to a better-executing rival is less cinematic than a financing round. It also offers something a young entrepreneur can examine: the gap between an idea and the work required to persuade someone else to care.
That gap has followed Soto-Wright through each chapter. The scale has changed, and so have the people on the other side of the transaction. His original customer wanted to put money aside. His later customers wanted to buy crypto; businesses now want to move it. Each still reaches a moment when the process must be simple enough to finish.