On day 17 of a 30-day experiment, Humphrey Yang found out what three earlier YouTube videos had failed to tell him: strangers would listen to him explain money. His TikTok about personal finance drew roughly three million views. At the end of the month, he had about 120,000 followers. A challenge he had set for himself had become a job description he never planned to write.
The numbers make for a neat origin story, but they hide the more useful part. Before there was an audience, there were friends asking him questions. What is a credit score? How does this investment work? Yang had worked as a financial adviser, and he liked turning the answer into something a person could use. He made videos partly so he could send the explanation once instead of repeating it over coffee.
That instinct still shapes his work. A complex idea enters the frame; an ordinary object comes out of it. A phone becomes a stock. Grains of rice stand in for immense sums of money. The viewer gets a picture before a vocabulary lesson. Yang’s talent is not that he can make arithmetic disappear. It is that he can make someone willing to look at it.
The household where money was always a topic
Yang grew up in the San Francisco Bay Area with a practical education in caution. His father had experienced poverty in Shanghai, gone to Taiwan, worked as a fighter pilot and later built an aviation business in the United States. At home, the lesson was to spend only when a purchase was necessary. Yang has described asking, even as a small child, whether the family was doing well financially. He did not always get a direct answer.
He also found a child’s way into commerce: selling soda to classmates in elementary school. The operation was small, but the question underneath it was large. What will someone pay for a thing that is suddenly convenient? It is the sort of question Yang still asks, only now the objects are cars, homes, credit cards or a gold bar sold back to a dealer.
His father’s habits left him frugal. In a later interview, Yang described delaying purchases for a day, a week or even a month to see whether he still wanted them. That discipline had another effect: he was hesitant about investing. Saving felt safer than putting money into a market whose prices could fall. It took study, work and data to change his mind.
My friends would ask me finance questions all the time, so I made this channel so I could send them videos…Humphrey Yang
A finance degree, an adviser’s desk, and a different question
Yang studied finance at Loyola Marymount University. Around the time of the 2008 financial crisis, that meant learning his subject while the subject was on the front page. He later entered Merrill Lynch’s financial adviser program and passed the Series 7 and 66 licensing exams. The job, which he held for roughly a year and a half, exposed him to investing data and the daily work of guiding clients.
It also taught him what he did not want his career to be. He has said that the adviser program put heavy emphasis on prospecting for clients and maintaining relationships. He came to believe that many people could understand a low-cost index fund without buying an elaborate explanation of one. At the same time, he has acknowledged that advisers can help with more complicated planning. The distinction matters: a simple video can clarify an idea; it cannot learn every detail of a person’s life.
After Merrill Lynch, Yang moved through the Bay Area’s technology world. He worked in mobile games, including roles at Kabam and Machine Zone. He later co-founded Craft & Oak, a custom print business. None of these positions looks like a prescribed route to teaching finance on a phone screen. Together, they gave him practice with customers, digital products, testing and the uneasy art of making something people will actually choose.
The first three videos went nowhere
In 2019, after hearing a podcast discussion about scaling work through media, Yang tried YouTube. He made three videos. Each drew around 10 views, he recalled, because he sent them to about 10 friends. The audience was technically complete; it simply consisted of everyone he already knew. He set the project aside.
Later that year, he searched TikTok for personal finance and found little there. The platform was full of young people and fast jokes, and Yang saw room for a different kind of clip. He decided to make one finance video every day for 30 days. His first, about credit scores, was rough by his own assessment, yet it reached around 10,000 viewers. On day 11, a post crossed 100,000 views. On day 17 came the one that reached about three million.
He continued posting daily well beyond the month. The streak eventually lasted 265 days. The work was experimental in a literal sense: try a topic, see what holds attention, adjust the next one. In a longer interview, he laughed at one early comparison of Bitcoin and Pokémon cards, a combination he later considered a poor topic. His curiosity was broad; his judgment about what served viewers became more exact with practice.
The iPhone that stood in for a stock
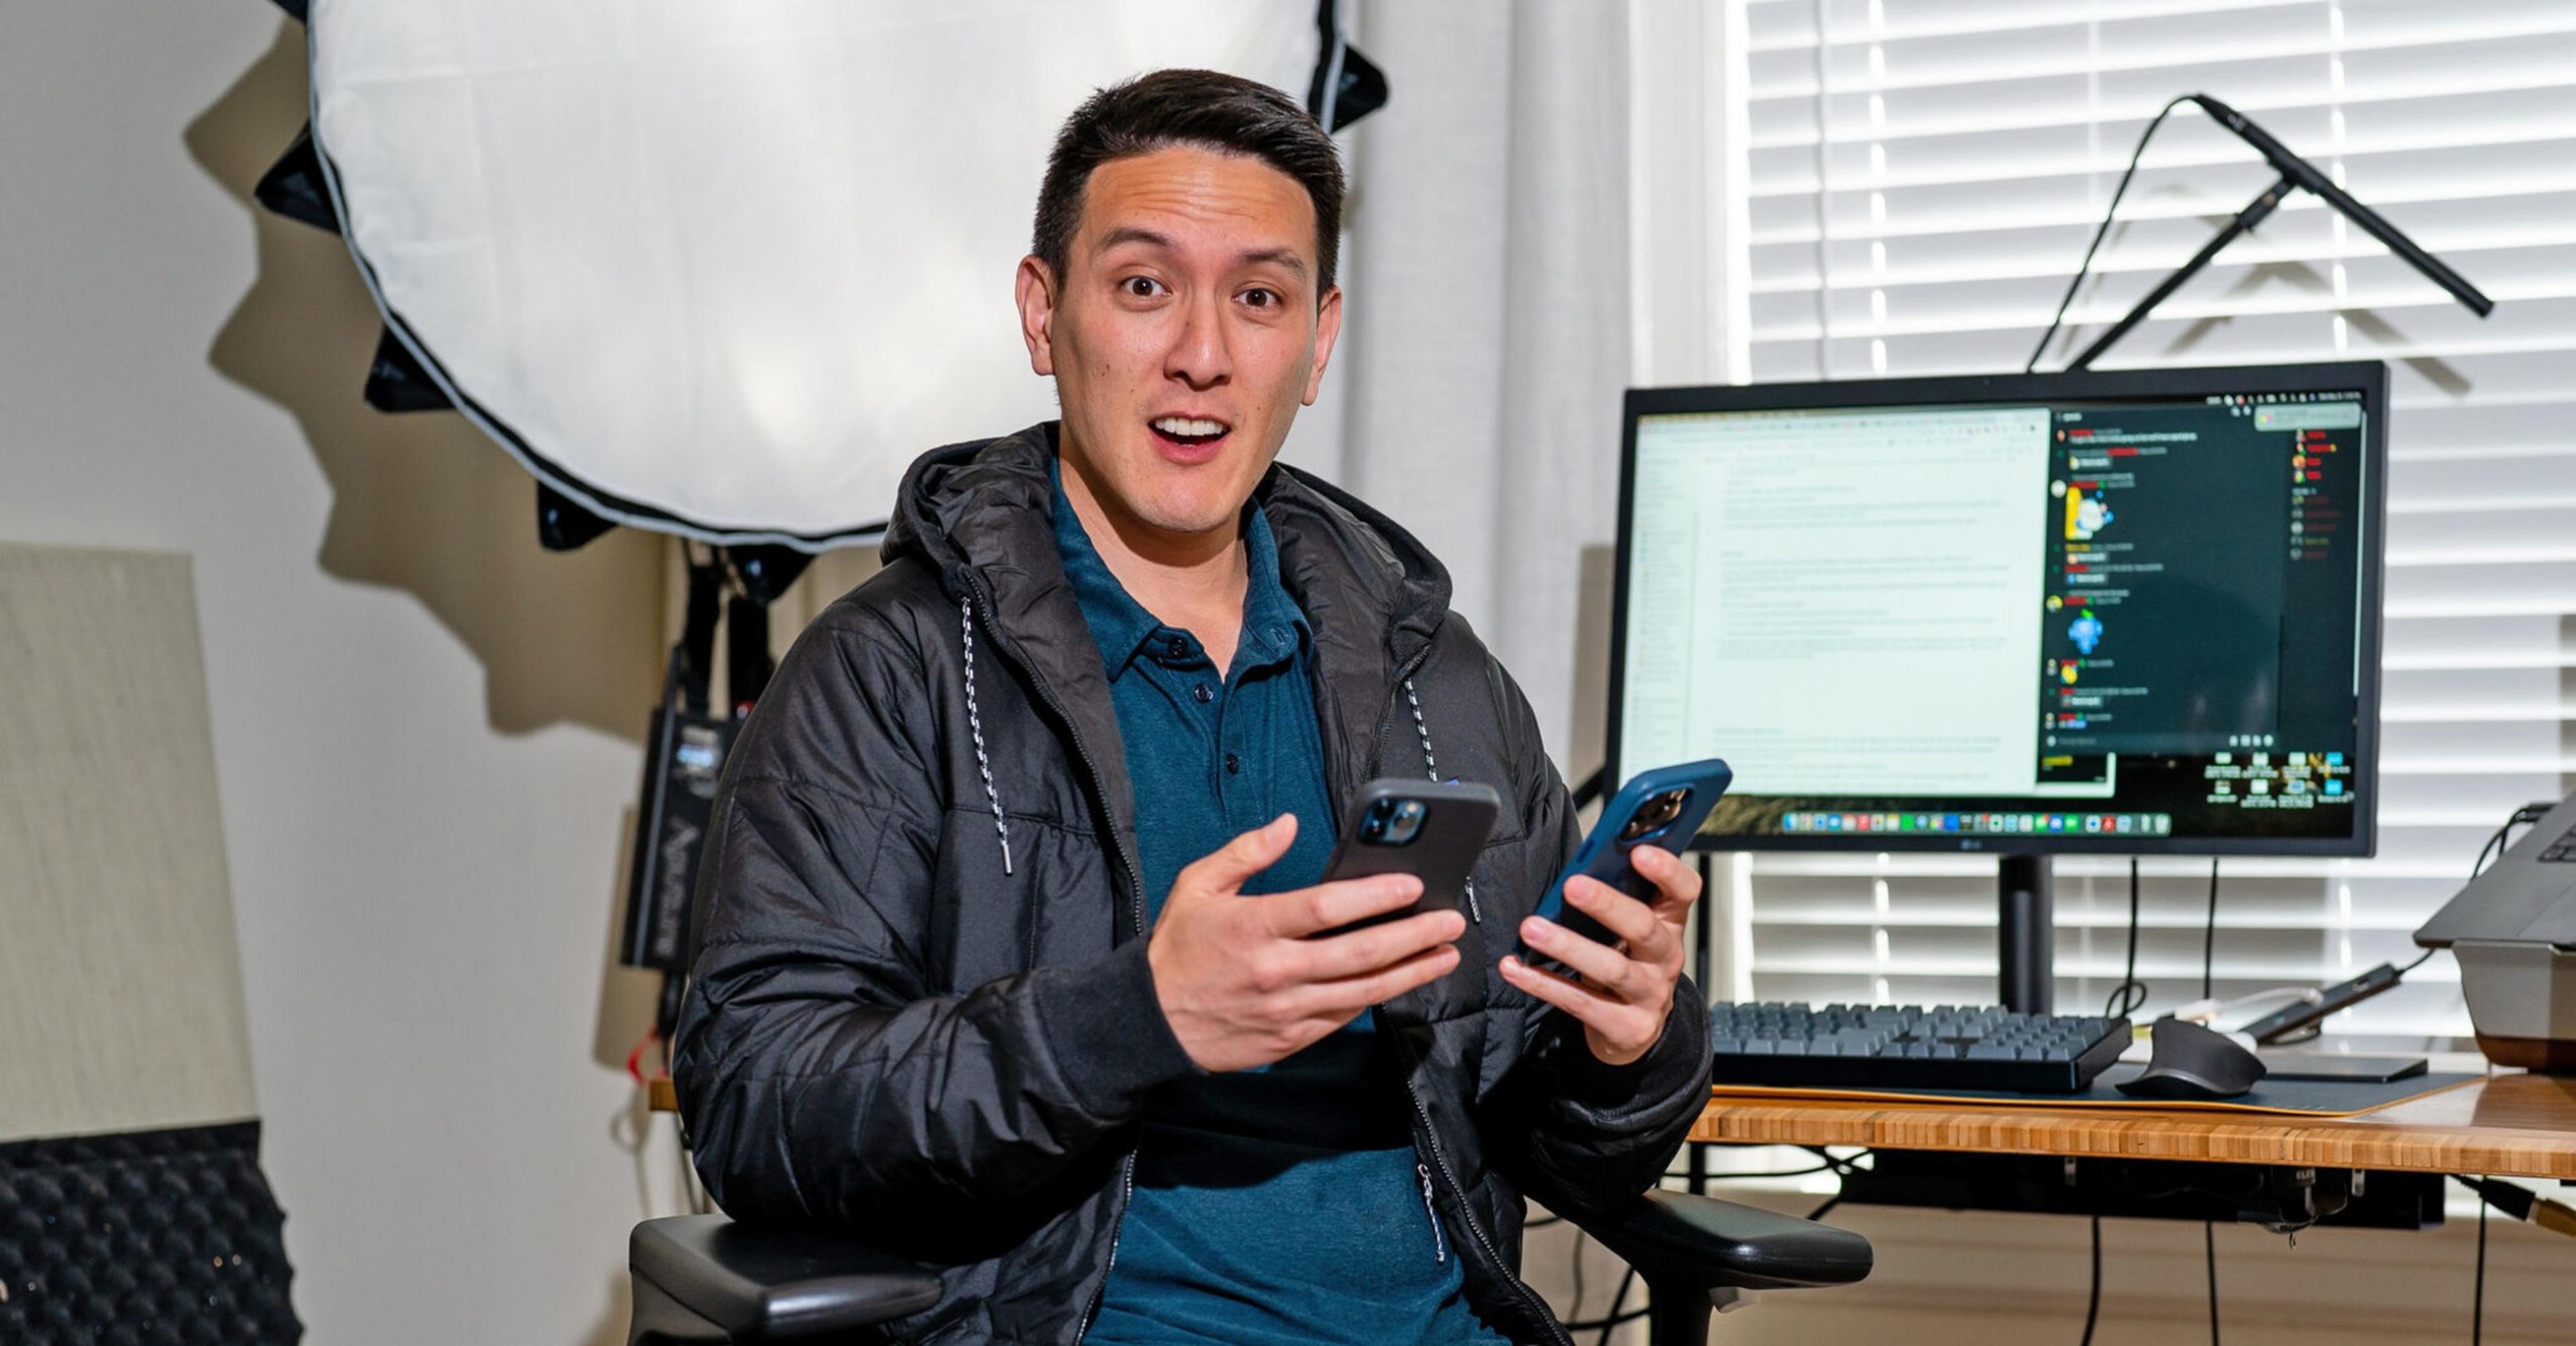
One of Yang’s widely watched videos gives short selling a family plot. A father lends his son an iPhone and asks for it back in a year. The son sells it, expects the price to drop when a newer model arrives, then plans to buy it back for less. If that works, he returns the phone and keeps the difference. If the price rises, the plan can hurt him. Yang plays both characters. The stock market has briefly become a conversation in a living room.
By 2023, Yang said the skit had received 15 million views on TikTok and 45 million on YouTube, plus more on Instagram. The scale is striking, yet its mechanism is modest: borrow, sell, repurchase, return. An iPhone is easier to picture than a borrowed share. The joke is gentle, and the lesson arrives before the viewer notices the terminology.
His clips have also unpacked tax brackets, lottery payouts and the economics of ordinary businesses. He often uses physical props. Rice can turn a number with too many zeros into a pile that has size and weight. This is not a complete financial education, and Yang has said so himself. He hopes a video gives people a framework and sends them looking further. A good analogy opens a door; it does not pretend there is no room beyond it.
What a free answer is worth
When Yang had a few hundred thousand TikTok followers, someone suggested he sell a basic budgeting course or ebook. He could have made it quickly and charged a modest price. He chose not to. In an essay about his business, he wrote that he did not want to charge for knowledge that a person could readily find for free. The decision is especially revealing because he was plainly capable of selling things: he had already run a print business.
His position is more precise than a blanket objection to creators earning money. A product, he argued, should deliver value beyond its price. He has used sponsorships and other creator revenue, while describing a careful screening process for brands. He also said he declined an offer from FTX before the exchange failed. In personal finance, the trust needed to make an explanation useful can be damaged by the wrong promotion.
There is a practical reason to build beyond a single feed, too. Yang has said a million TikTok views might bring in very little directly, while YouTube ads provide a clearer path to revenue. Longer videos also let him follow a question past its catchy opening. His Hump Days newsletter gives readers another way to hear from him. The platform mix is a business choice, but it is also an editorial one: a short video can spark interest, and a longer format can linger where the answer gets complicated.
Two million subscribers, then a new room
In late March 2026, Yang’s main YouTube channel passed two million subscribers. He marked it in his newsletter with thanks to viewers and a small celebration: cupcakes, including ones labeled “HUMP” and “CONG.” The detail feels appropriately modest for a career built on getting people to look closely at a number before being impressed by it.
By September he was posting in-person episodes of The Humphrey Show on a separate YouTube channel. The idea was to sit with real people and put their financial stories, including the figures, in view. It is another change of form. A phone skit can explain a principle in seconds; a conversation can show what happens when principles meet a person’s actual choices. Yang has asked Bay Area viewers with stories to apply. The friend who once answered questions at a distance has made a room for the questions to arrive in person.
The lesson after the lesson
In 2025, talking about his own money history, Yang returned to the caution he learned at home. He described how being risk-averse had led him to sell investments that he later wished he had held. His advice to his younger self was to invest sooner and interfere less. In the same conversation, he spoke about finding room for experiences rather than letting saving become an end in itself. The person who explains money for a living still has to decide what money is for.
That is a more interesting career than the follower count alone suggests. Yang began as the friend who could answer a question, learned the formal language at an adviser’s desk, tried businesses and jobs with no obvious connection to media, and discovered that the smallest screen could hold a useful explanation. The trajectory contains failed uploads, a productive month of repetition and a long revision of what he himself believed about risk.
His clearest videos make a viewer say, “Oh, that’s what it means.” The sentence sounds small. For someone who has been kept out of a conversation by jargon, it is a beginning. Yang has spent years arranging that beginning, sometimes with an iPhone, sometimes with rice, and often with nothing more exotic than a clear question asked in ordinary language.