Digital money, in 1999, could arrive on a prepaid card. A shopper bought value in the physical world, then used a number and a PIN to spend it online. InternetCash was working on that problem when Hans Thomas joined its founding team. Years before a token could become the centrepiece of a public company’s treasury, the immediate challenge was getting a payment through a browser.
That early chapter gives Thomas’s later career a useful starting point. Today he runs 10X Capital in New York, where the work includes investment vehicles, digital assets and the financing of technology companies. Between the prepaid card and the treasury strategy came mortgages, financial data and blank-check companies. It is a résumé with enough changes of costume to require a decent wardrobe department.
Look more closely, though, and the sequence becomes less eccentric. Thomas has repeatedly worked where a new technology meets an existing financial system. The idea attracts attention. The surrounding machinery determines who can use it, who can fund it and what, exactly, an investor gets to own.
Digital money, before the token
InternetCash belonged to an earlier generation of online finance. Its prepaid payment system used cryptography, but it was a different arrangement from today’s blockchain assets. The company built its own payment network, with a payment window where shoppers entered their card details. The transaction then passed through the company’s servers.
The distinction matters in Thomas’s story. A founding-team role in a digital-payments business in 1999 gives him a long association with the subject. It does not turn the business into an early version of every later cryptocurrency venture. What connects the periods is a practical question: how does a digital financial product reach the people and institutions expected to use it?
Thomas attended New York University. In August 2001, he began a period as executive director at One Zero Capital that continued until December 2019. He founded 10X Capital in January 2004. These overlapping roles place the investment firm inside a longer working life in financial technology, rather than at the beginning of it.
Digital payments
Capital and mortgages
Financial data
Public markets
Digital assets
The mortgage changed his point of view
Also in 2004, Thomas founded RefinanceOne, an online jumbo mortgage business. Its public biography records an exit in 2007. In his own account of the business, he credits search optimisation and advertising technology with helping turn a lead-generation operation into a mortgage originator operating across 47 states.
That account is revealing for its choice of tools. The work of finding a borrower sat alongside the work of financing a loan. A web business had to become a financial operation. Thomas’s retrospective emphasis falls on the connection between distribution and scale, with the search engine doing some of the introductions that a branch office might once have handled.
His next mortgage-related venture changed the viewing angle. At TheNumber, which he co-founded in 2015, the customer was looking into financial assets. The company assembled data for investors analysing consumer loans and mortgage-backed securities. Thomas’s experience had moved from helping make a mortgage to helping someone understand what lay inside mortgage investments.
A bond can look tidier than the lives beneath it. Borrowers refinance, move, list houses for sale or fall behind on payments. Those choices can affect the cash reaching investors. TheNumber used data fusion and machine learning to bring additional detail to analysis, including property information and loan-level characteristics.
By 2017, the company was combining information from marketing businesses, public loan records, courts and other sources. The same detail that interested traders raised privacy questions. The data business therefore put Thomas at another boundary: a better-informed market on one side, the consequences of assembling information about borrowers on the other.
His collaborators were part of the bridge. Guhan Kandasamy and Sigurgeir Orn “Ziggy” Jonsson co-founded TheNumber with him. Jonsson’s background included structured-credit trading; Kandasamy’s included credit data and product development. Those relationships later appeared in 10X’s public-market work, where the names recur alongside Thomas’s. The career advances through people as well as companies.
“You can think of us as Wall Street meets Silicon Valley.”
Hans Thomas, on 10X Capital
A financing business with several doors
Thomas uses that meeting of Wall Street and Silicon Valley to describe 10X. The phrase is familiar enough to pass unnoticed. His career supplies a more concrete reading: technology companies on one side, institutions with money on the other, and a range of arrangements connecting them.
The firm now describes itself as a merchant bank, with public and private structures, funds, a treasury business and an affiliated investment bank. In that model, choosing a company is only one part of the work. The form of the financing becomes part of the product. An equity investment, a debt arrangement and a public-market transaction give investors different claims and companies different obligations.
A conceptual guide to the financing mechanisms in Thomas’s career. These routes carry different terms and risks.
There is a personal feedback loop in his description of venture investing. Thomas says he takes pride in former portfolio-company CEOs becoming limited partners after their exits. The relationship changes direction: a founder who once received investment can later supply capital to the investor’s fund. His stated pride rests in that return visit.
10X’s venture history also includes David Weisburd, who founded Growth Technology Partners in 2015. 10X acquired that firm in December 2019. Thomas became its chairman, and Weisburd took a leading role in the venture business. That combination helped connect Thomas’s New York financial background with a venture portfolio originating in San Francisco.
The public-market chapter made the financing work more visible. Thomas became chairman and CEO of 10X Capital Venture Acquisition Corp., a special purpose acquisition company. A SPAC raises money before completing a combination with an operating business. Its initial product is, in effect, a transaction still to be chosen.
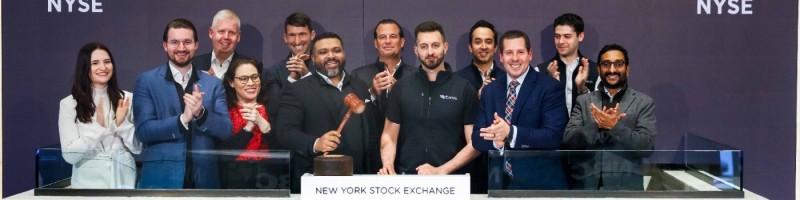
Thomas rang Nasdaq’s closing bell for the 10X acquisition company as well. The ritual makes an abstract process photogenic: people, applause and a clock. The less visible work involves lawyers, investors, operating teams and the structure of the transaction. The ceremony supplies a moment; the agreements supply the consequences.
An electric vehicle enters the picture
In July 2021, the 10X acquisition company completed its merger with REE Automotive, an Israeli electric-vehicle technology business led by co-founder Daniel Barel. The combination closed on July 22. REE’s shares and warrants began trading on Nasdaq the following day.
REE’s proposition centred on modular vehicle technology, including its REEcorner system and flat platforms. For Thomas, the deal extended a financing career into mobility. His contribution came through the acquisition vehicle and capital-market arrangement around the operating company. Barel continued to lead REE after the combination.
The transaction involved strategic investors including Koch Strategic Platforms and Magna International. Morgan Stanley led placement of the private investment supporting the combination. That collection of participants shows how much coordination sits behind a sentence announcing a merger. Completion marked entry into public markets; the operating business still had to execute its plans afterward.
In August 2025, Thomas appeared on a Wyoming Blockchain Symposium panel about digital-asset treasury strategies. He joined Jeff Park, Marco Santori and Brittany Kaiser, with Dax Hansen moderating. The title, “Bitcoin and Beyond”, captured the widening range of assets being considered for these public-company structures.
When the contract became the story
By 2025, digital assets had brought Thomas back to a subject resembling his earliest work, though the financial architecture had changed. 10X participated in a $500 million private financing for CEA Industries to establish a BNB treasury strategy. Thomas joined CEA’s board on August 5, alongside 10X partner Alexander Monje.
The arrangement placed digital assets inside a listed-company structure. CEA appointed a 10X entity to manage the treasury strategy, primarily focused on BNB and BNB equivalents. The asset-management agreement had a twenty-year term. For shareholders, the contract surrounding the holdings would become a subject of considerable attention.
In February 2026, CEA sought changes to management fees, duration and termination provisions. It said 10X had indicated a willingness to renegotiate. CEA and shareholder YZi Labs also issued conflicting statements about a separate agreement between YZi and 10X, including whether its termination was effective and whether it impeded amendments.
Thomas resigned from CEA’s board effective March 20, 2026. CEA said his resignation did not result from a disagreement with the company, management or the board concerning operations, policies or practices. On May 22, CEA announced a complaint against 10X seeking to invalidate the asset-management agreement and recover fees. These were the company’s claims, rather than judicial findings.
In June, CEA and YZi Labs reached a cooperation agreement ending YZi’s consent solicitation and adding three directors. That governance agreement involved CEA and YZi; it should be read separately from CEA’s complaint against 10X. The sequence gives the digital-asset chapter a more complicated shape than the financing announcement alone.
The machinery behind the idea
Thomas’s professional ambition remains connecting institutional capital with technology. What makes his history distinctive is the number of positions from which he has approached that task. He has been inside a payments startup, built a mortgage business, helped assemble financial data and led investment and acquisition vehicles.
Those experiences make the plumbing visible. An idea needs a payment network, a distribution channel, a usable dataset or an ownership structure. Each can open a market. Each also brings terms, incentives and responsibilities of its own. In Thomas’s career, the machinery has repeatedly become a business. Sometimes, as the treasury chapter shows, it also becomes the argument.
Follow the connections
- Watch the 2025 Wyoming digital-asset treasury panel (YouTube) ↗
- Thomas’s personal website ↗
- 10X Capital ↗
- Thomas on LinkedIn ↗
- Thomas’s Wellfound profile ↗
- TheNumber ↗
- Watch the Nasdaq closing-bell video ↗
- REE’s July 2021 transaction announcement ↗
- CEA’s March 2026 board announcement ↗
- CEA’s May 2026 complaint announcement ↗
- June 2026 cooperation agreement ↗
- CEA’s February 2026 statement ↗
- YZi’s February 2026 response ↗