When Gregg Lemkau and his wife, Kate, gave $2 million to endow Dartmouth’s men’s soccer coaching position in 2015, they had a perfectly respectable option: put their own name on it. Universities have considerable practice in that department. Instead, the position became the Bobby Clark Head Coach of Men’s Soccer. A banker who had spent his working life helping people decide what things were worth had made a small, public judgment about who deserved the credit.
Clark had coached Lemkau at Dartmouth, where he played goalkeeper. The gift was a thank-you that would outlive a thank-you note. It also gave future players a reason to ask about a coach who had already moved on. The donor’s name receded; the teacher’s stayed in circulation. There are more elaborate ways to explain your values. This one came with a job title.
Lemkau’s career supplies plenty of larger numbers. His Goldman Sachs tenure lasted 28 years, and his work involved hundreds of transactions. But the coaching endowment offers a more human place to begin. It links the undergraduate athlete to the executive, without requiring us to pretend that every business decision is a sporting contest. Sometimes the lesson is simply about remembering who helped you learn.
The teacher outside the classroom
Lemkau studied government and economics and graduated in 1991. On the soccer field, his education had a different rhythm: decisions made in real time, consequences shared with teammates, instruction that had to survive the moment when the instructor could no longer intervene. Clark’s approach left an impression strong enough to be recalled decades later.
“He wanted you to be internally motivated.”
Gregg Lemkau on Bobby Clark, 2015
That recollection gives the coaching gift its substance. The important thing was a player’s ability to act for himself within a collective effort. In Lemkau’s account, the lessons reached beyond the match into the bus rides and the off-season. Education could happen away from the classroom, and could remain useful long after the original examination was over.
Clark, for his part, was surprised by the name chosen for the endowment. He had expected a donor to use his own. The response was gratitude rather than a grand theory of leadership. It is worth keeping the story at that scale: a former player remembers a coach, a family funds a position, and the coach learns that his influence has lasted.
There is an appealing lack of ceremony in the underlying idea. A named position can preserve the memory of a person, but it also pays for work still to be done. The next coach must recruit, teach and make choices. Lemkau and Kate’s gesture honored an earlier relationship while providing something useful to people who had never been part of it.
The 2015 endowment established Dartmouth’s Bobby Clark Head Coach of Men’s Soccer position.
Four cities, and the discomfort of starting again
After college, Lemkau briefly worked as a paralegal at Skadden before entering banking. He joined Goldman Sachs in 1992 as a mergers and acquisitions analyst. The subsequent career moved through New York, Los Angeles, San Francisco and London. Technology banking became a recurring part of his work, but his responsibilities also took him into other sectors and into the management of the bank itself.
He became a managing director in 2001 and a partner in 2002. By 2011, he was leading mergers and acquisitions for Europe, the Middle East, Africa and Asia Pacific. He became co-head of global M&A in 2013. In 2017, he was named co-head of the Investment Banking Division. The titles suggest steady accumulation. The geography suggests repeated adjustment.
A move to another office changes more than the address on a business card. Different colleagues have to learn your judgment. Different clients have to decide whether you understand their problems. Experience gives you something to bring to the meeting; it does not remove the need to listen once you arrive. That distinction helps explain why a long career at one institution can still contain several beginnings.
The range of his jobs matters, too. Leading an industry group, overseeing transactions and operating a division ask different things of a person. An industry specialist needs depth. A manager has to make room for other people’s depth. A senior adviser has to bring the two together without assuming that yesterday’s answer belongs in today’s conversation.
- 1992M&A analyst at Goldman Sachs
- 2002Goldman Sachs partner
- 2017Co-head of Investment Banking
- 2021CEO of MSD Partners
- 2023Co-CEO of BDT & MSD Partners
The deal you leave on the table
In a 2016 career interview, Lemkau identified delegation as a persistent difficulty. Banking depends on experience, but it also depends on passing that experience along. Doing a task yourself may produce the answer quickly. Teaching somebody else takes time and requires tolerating the distance between your own fluency and theirs. A senior person can become so useful that everyone else has fewer chances to become useful.
His account of advice contains a related tension. He singled out recommendations about “when not to do a deal” as especially valuable. A transaction can produce a fee; deciding against it can help preserve a client relationship. The reward arrives on a different timetable. It is an inconvenient principle for anyone hoping that a spreadsheet will settle every question about good conduct.
For a founder, a proposed sale can involve much more than a price. The business may hold a family’s working history, a founder’s identity or responsibilities to employees. An adviser needs to understand what the owner is trying to achieve before deciding which transaction would serve that purpose. A technically sound proposal can still answer the wrong question.
Lemkau’s own advice to his younger self also allowed for pleasure. He urged himself to work, enjoy the experience and avoid taking himself too seriously. He even included the encouragement to approach the woman at a bar who might become the mother of his four children. The career interview briefly became a courtship story. Banking had to share the paragraph.
Michael Dell, and a change of seat
At the end of 2020, Lemkau left Goldman. In January 2021, he became CEO of MSD Partners and chairman of DFO Management, Michael Dell’s family investment office. After years of advising businesses at important moments, he was taking responsibility inside an investment organization. The seat changed, along with the kind of work that followed a decision.
The distinction between the Dell family office and MSD Partners matters. MSD Capital began in 1998 to invest family capital; MSD Partners was established in 2009 to accept outside investors as well. When Lemkau discussed the business in 2022, he described private capital, credit, real estate and growth equity as its four investment areas. Those capabilities allowed different forms of participation in a company’s development.
He used the financing of Endeavor’s acquisition of UFC as an example of investing at a strategic turning point. The argument concerned access and structure: an investor able to supply the needed capital at a particular moment could participate in the change that followed. It was an explanation of the firm’s approach, rather than a promise that every turning point would produce an attractive outcome.
For the adviser, closing a transaction is a milestone. For the investor, it begins another period of responsibility. Capital has to remain exposed to what happens next. Moving between those roles creates a useful question for Lemkau’s second act: how do you carry the understanding gained from advising owners into decisions where your own organization is investing alongside them?
Two firms, one longer conversation
In October 2022, BDT and MSD announced plans to combine. The new firm took shape in January 2023, with Byron Trott and Lemkau as co-chief executives. Trott’s BDT had been built around closely held businesses; MSD brought its investment capabilities and relationships. Michael Dell became chairman of the advisory board. The initials were compact. The work they represented was considerably less so.
The combination made practical sense for owners whose questions do not arrive neatly sorted. A family business might need help with succession, capital or an acquisition. A founder might want a partner without wanting to sell outright. Advice, equity, credit and real estate investing offer several ways to stay involved as those needs develop. Choosing the appropriate role remains the important part.
A firm that both advises and invests also has to be clear about the capacity in which it is acting. Owners need to understand the proposal and the interests involved. Long relationships can provide context; they still require careful decisions. The promise of patient capital becomes meaningful through those decisions, rather than through the phrase alone.
In his more recent public comments, Lemkau has described bringing the firm’s partnership approach with multigenerational families to technology founders as a strategic priority. That connects two parts of his career: familiarity with technology businesses and a firm organized around owners. A young company and an older family enterprise may have different histories, while facing equally personal questions about control and the future.
Back to Dartmouth, with a different job
Lemkau joined Dartmouth’s trustees in 2020 and became chair in January 2026. The former goalkeeper returned with responsibility for the institution itself. On January 27, BlackRock elected him an independent director. These appointments added another layer to a career already involving investment decisions, advisory relationships and company boards.
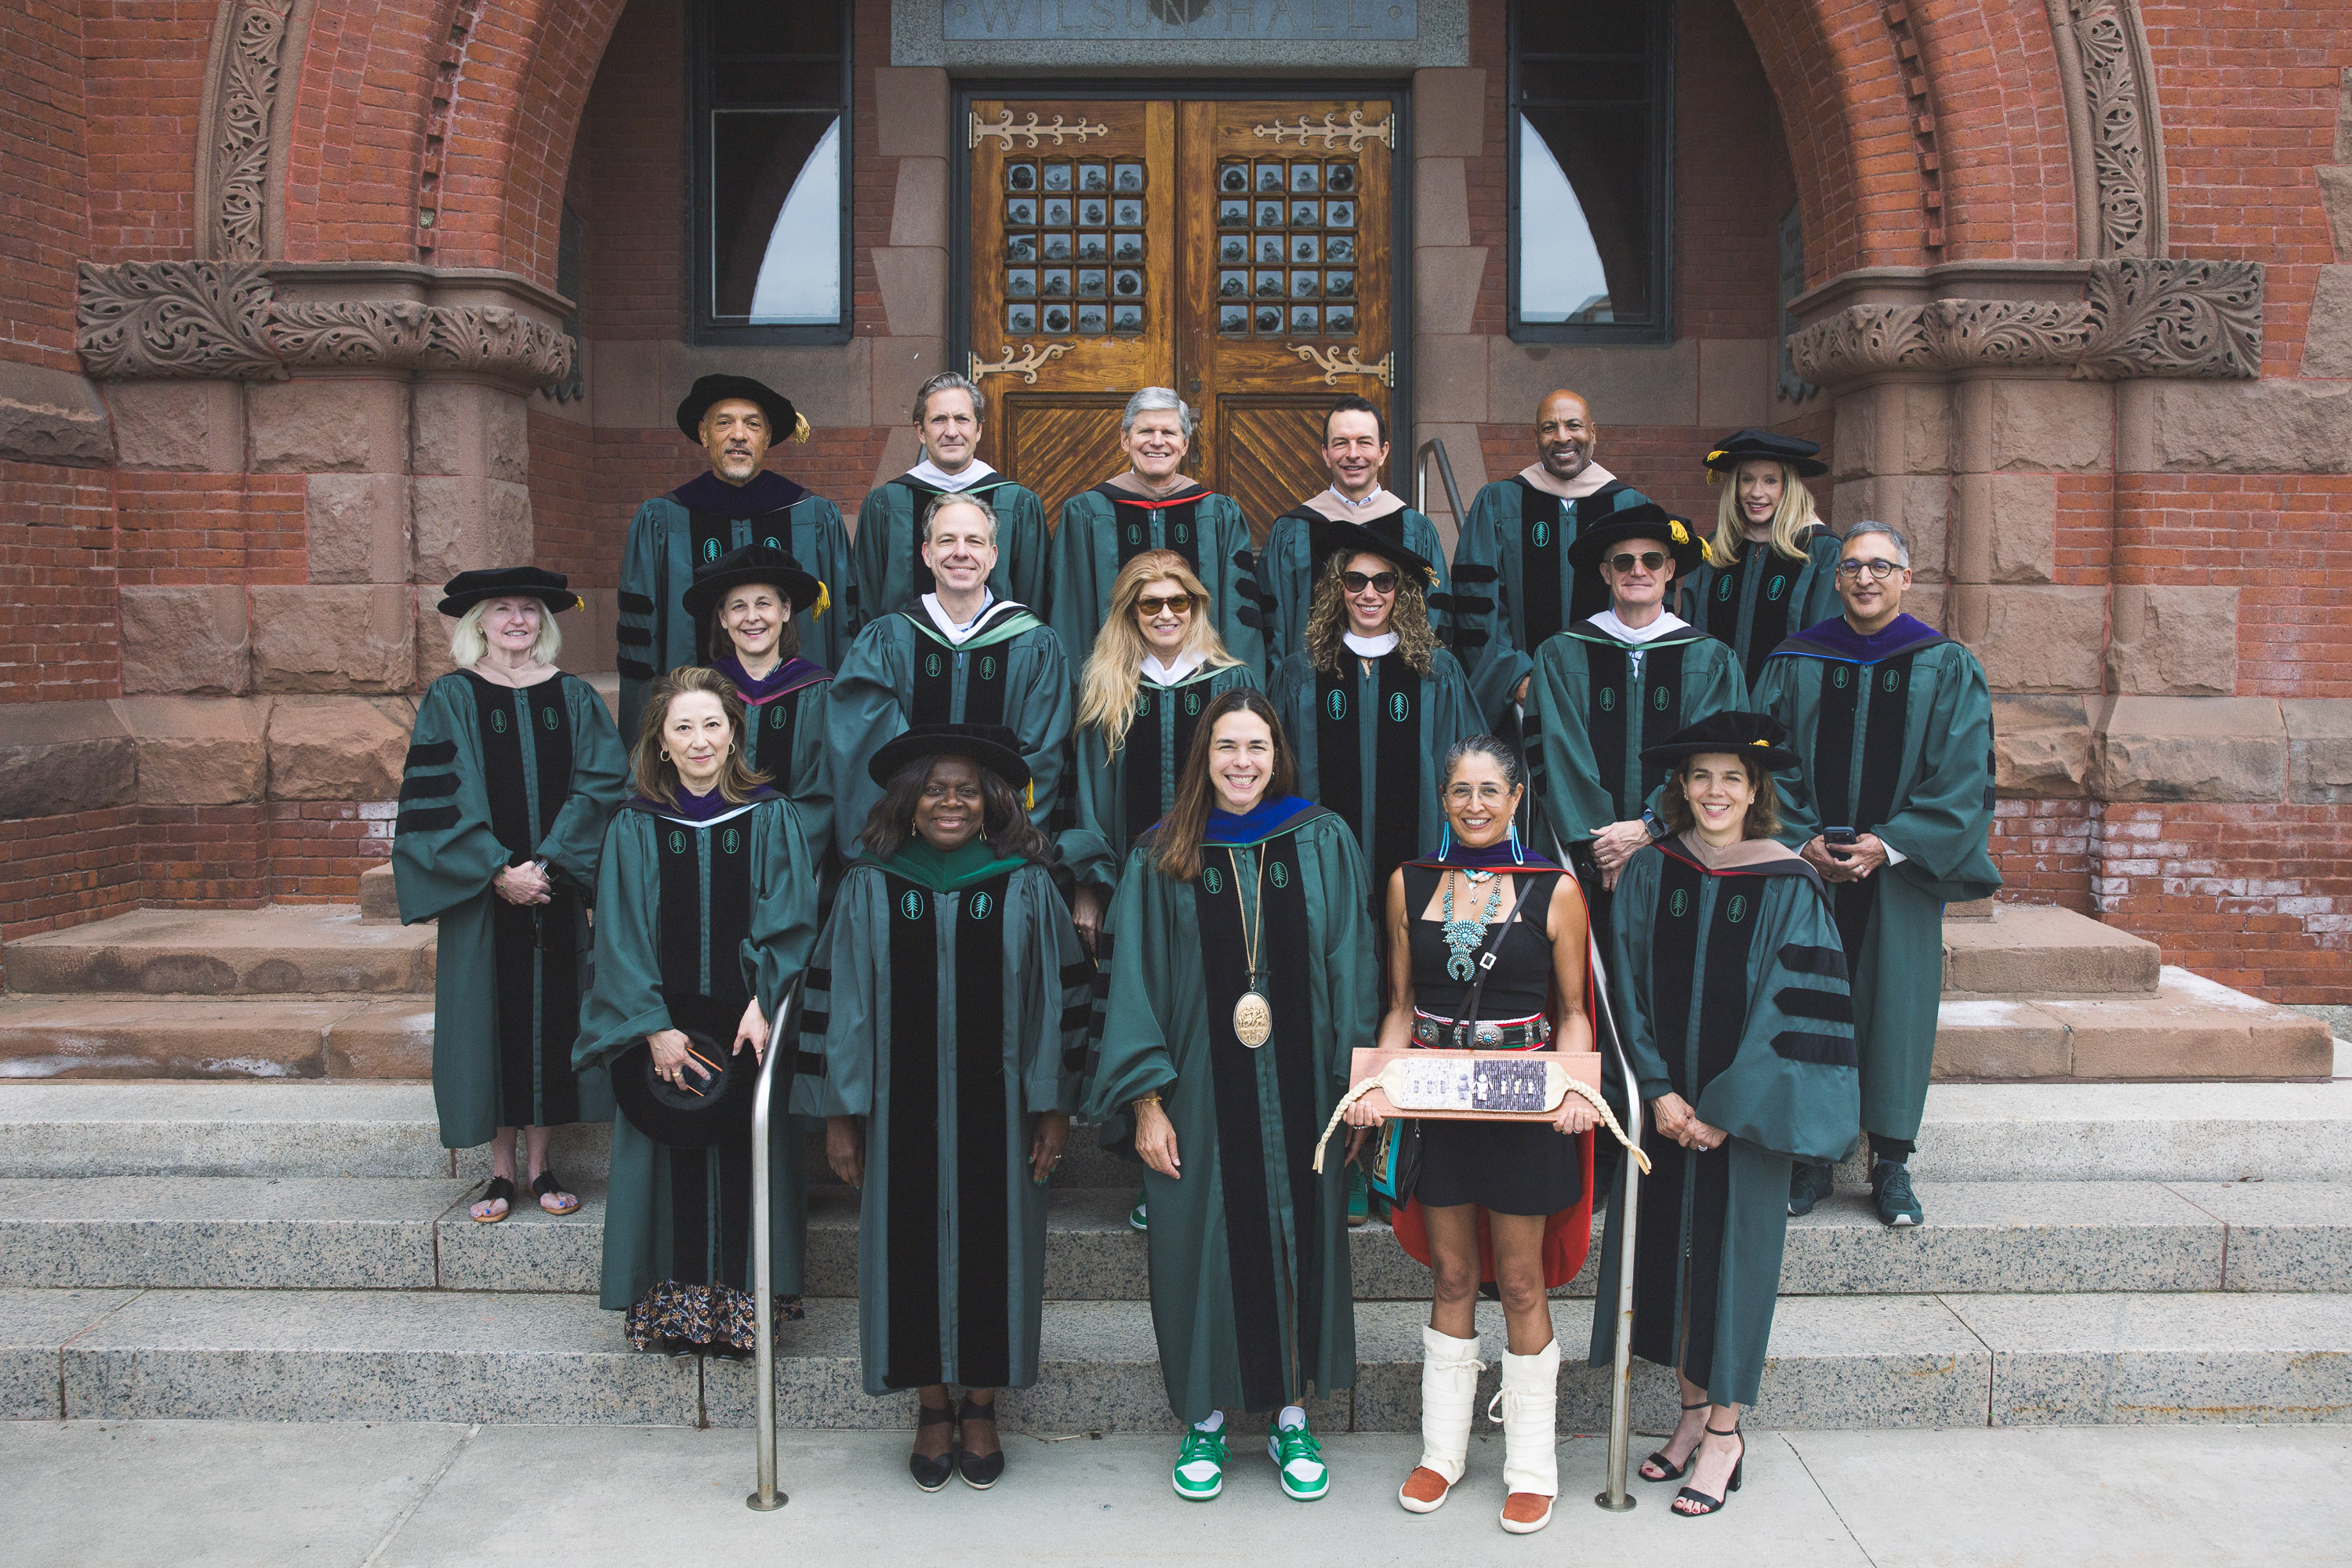
At commencement that June, he joined fellow trustees in Hanover, welcoming graduates and marking the reunion of Dartmouth’s Class of 1976. The college he remembered through study and sport now required a wider view. Governance brings obligations that extend to people you have never met, including students whose arrival is still years away.
The coaching gift makes a fitting companion to that return. It had already translated an undergraduate relationship into support for future players. Chairing the trustees extends the circle of responsibility. Neither role requires a sentimental claim that college explains everything about a life. It is enough to observe how often Lemkau has chosen to remain connected to the place.
The name on the coaching position remains Bobby Clark’s. Lemkau has collected other titles since he helped put it there. That earlier choice still tells a clear story: somebody taught him something he continued to value, and he found a way to keep the teaching going.