A car loan can move through the internet and still get stuck on a signature. In a 2021 interview, Gravity Lending co-founder Brian Jones described the awkward interruption: lenders could accept electronic signatures, while title paperwork could still require ink. The customer had found a new loan. Finishing the transaction was another matter. It is a revealing detail about an industry usually discussed in percentages. A better rate is useful. Getting someone from an offer to a completed refinance requires a rather different kind of expertise.
- The job: shop an existing auto loan across a lending network.
- The service: a loan officer helps carry the application through closing.
- The catch to understand: a lower payment can reflect a longer loan.
A loan goes shopping
Gravity Lending occupies the space between a driver and a financial institution. The driver wants a more manageable bill. The institution wants a loan that fits its rules. Gravity collects information, finds potential matches and helps arrange the transaction. The underlying business began as Wildhorse Financial Services in 2015; the Gravity Lending name arrived in 2019.
NerdWallet’s August 2026 review described a network of approximately 90 lenders, including credit unions. That gives the borrower access to several institutions without starting a separate conversation with each. A dedicated representative supplies the human continuity. The person seeking help might have improved their credit, inherited an expensive dealer-arranged loan, or simply need to change their repayment schedule.
The company also arranges lease buyouts for drivers who want to keep their leased cars, and cash-out refinancing for eligible owners with vehicle equity. The common thread is an existing vehicle and a financial arrangement worth reconsidering.
This is also where the marketplace has limits. A large network increases the number of possible matches; it cannot make every applicant eligible. Gravity’s terms say an offer is not guaranteed. The institution making the loan still decides whether the borrower qualifies. Comparing lenders saves legwork, but the final agreement deserves the same attention as a loan obtained directly from a local branch.
The unglamorous work that gets a loan funded
Gravity’s offering to lenders explains the business particularly well. It promises filtered applications, support with the transaction and a perfected new lien on funded loans. Institutions retain control of their rates and guidelines. Gravity says in a public customer response that lenders compensate it for completing loan transfers. The intermediary earns its place by doing work.
Its lender-services page now makes that work explicit: call centers, underwriting, document processing, accounting, and lien and title assistance. A credit union can buy operational capacity alongside access to borrowers. In that sense, Gravity is selling something less visible than comparison shopping: help getting a loan onto the books.
An early Lightico implementation used mobile document collection and electronic signatures. Auto Remarketing reported a 16% improvement in time to funding, a company-and-vendor account rather than an independent audit. The practical lesson is narrow enough to copy: find where a customer stops, then make that step easier to finish.
“We were broke for our first year, year and a half”
Brian Jones, speaking to Lightico in 2021
That recollection puts a useful limit on the polished fintech story. Jones described choosing technology according to operational pain, expected return and the resources needed to implement it. The appealing feature was the one that solved a problem the business could already see.
The payment is only half the story
Gravity charges no borrower service fee. Its FAQ still allows for title-transfer charges, state fees and optional protection products in the new loan. “Free” describes the matching service; the borrower is still taking on an interest-bearing obligation. The distinction belongs beside the offer, where it can influence a decision.
The homepage advertises average monthly payment savings of $128. Its current disclosure ties that figure to funded loans from June through August 2026. A monthly reduction is a cash-flow measure. It does not, by itself, say how much interest a borrower avoids.
Consider an illustrative $25,000 balance. At 10% over 48 months, the payment is about $634. At 6% over the same period, it falls to about $587. Stretch the 6% loan to 72 months and the payment drops to about $414. That third option offers more room each month, but costs more interest than the shorter 6% loan.
A household may reasonably choose immediate breathing room. What matters is making that choice consciously. The useful comparison includes APR, amount financed, payment count, charges and total repayment. Ask for the figures with optional products removed, too.
Three kinds of trouble, three kinds of cover
Gravity’s protection products address separate risks. GAP can waive an eligible shortfall between an insurance settlement and the remaining loan after theft or a total loss. A vehicle service contract addresses covered repairs beyond the manufacturer’s warranty. Its vehicle protection plan bundles services involving such things as tires, wheels, keys and dents.
Those are separate purchasing decisions, even when presented during one refinance. A cheaper loan does not establish that every additional product is good value. Coverage, exclusions, existing protection and the effect on the financed balance all belong in the calculation.
The same discipline applies to the old loan. A borrower comparing replacement financing needs its remaining balance and payment schedule, rather than the original purchase price. Otherwise, the comparison quietly changes the starting line. Gravity’s refinancing guide tells customers to review their existing loan first. It is a modest instruction, and a useful one: shopping starts with knowing what you already have.
Meet the Gravinators
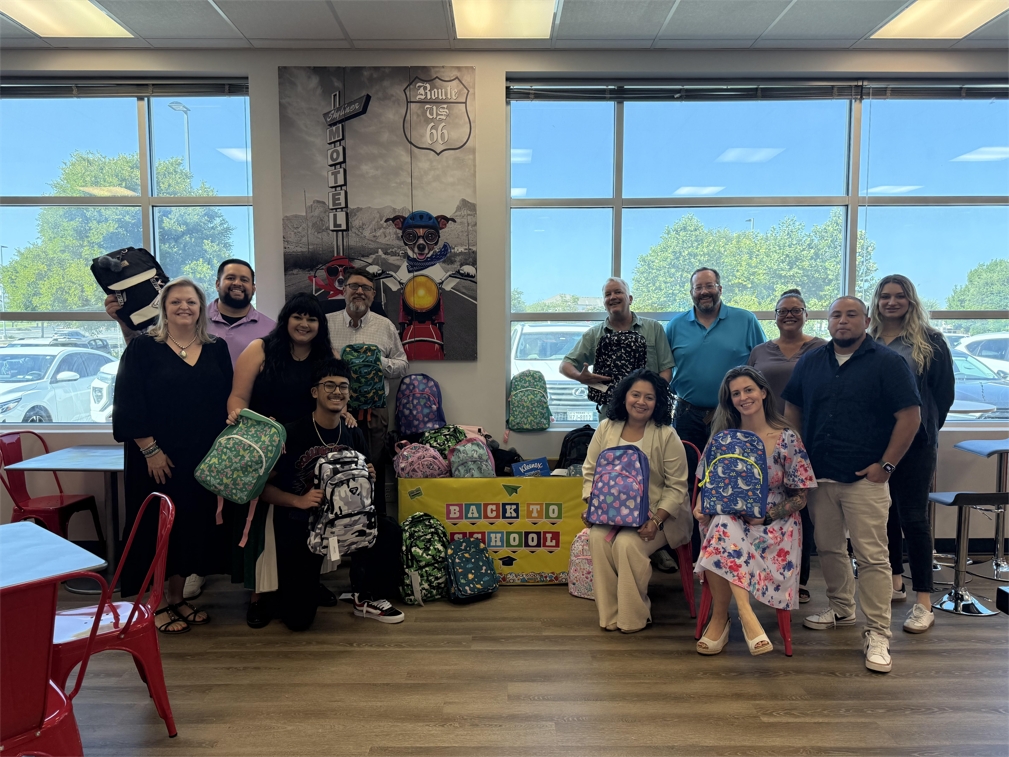
The employees have a name: Gravinators. The careers page lists health coverage, a 401(k), paid time off and life insurance. Its workplace profile emphasizes collaboration; its contact page describes support for child-focused charities. The photograph below offers a less abstract introduction: people, backpacks, and a back-to-school sign.
Keep the car. Read the whole deal.
Alternatives include RateGenius, Caribou and a direct application to a bank or credit union. Gravity’s case rests on combining lender access with help completing the transaction. The fit depends on an actual offer: lender rules, vehicle details and the borrower’s credit still govern approval. Its FAQ explicitly describes a hard credit pull, a detail to understand before submitting an application.
The car in the driveway provides a useful anchor. Nothing about its usefulness changes when a new lender takes over. The opportunity lies in revisiting a contract that may no longer fit. Gravity supplies the shopping and the follow-through. The reader’s job is to count the payments.