A credit union is an unusual place for an investment banker to go looking for scale. The institutions belong to their members. Their appeal rests on proximity and trust. They rarely have the marketing budgets of the banks whose names fill railway stations. Tobias Gruber looked at that arrangement and saw room for a business. Having spent much of his working life around large financial institutions, he turned towards organisations that needed help competing with them.
His proposition had a practical charm: give smaller lenders the technology, capital and operating support to reach people beyond their usual circle. A customer looking for a loan would encounter a straightforward digital application. Behind it sat a much less straightforward collection of institutions, systems and funding arrangements. The shop window could be simple because somebody else had agreed to organise the stockroom.
That effort became part of the story of Amplifi Capital, where Gruber was co-founder and chief executive. It grew into a business connecting borrowers and savers with credit unions and, later, making loans through its own Reevo Money brand. It attracted institutional financing and public recognition. It also entered administration in June 2026, after Gruber’s reported departure as CEO that April.
Today he is listed as a strategic adviser at Arcanum Consulting. The work stretches from financial technology into environmental technology. There is continuity in the questions: how an institution funds itself, how its systems work, and how an investor decides that an attractive proposition can survive contact with an uncooperative world.
A career spent learning the plumbing
Gruber’s earlier career gave him a working vocabulary for that problem. He studied management at the University of Bielefeld and earned an MBA. His banking experience included JPMorgan, Morgan Stanley and AIG Financial Products. At Credit Suisse, his responsibilities included insurance and pension solutions across asset classes. These were jobs concerned with the construction of financial arrangements, where the details determine who carries which risks.
He also co-founded Venn Partners, an advisory and mortgage and loan platform. Entrepreneurship therefore preceded the credit-union venture. The move into consumer finance brought him closer to a different end customer, but funding, distribution and the allocation of risk remained familiar territory.
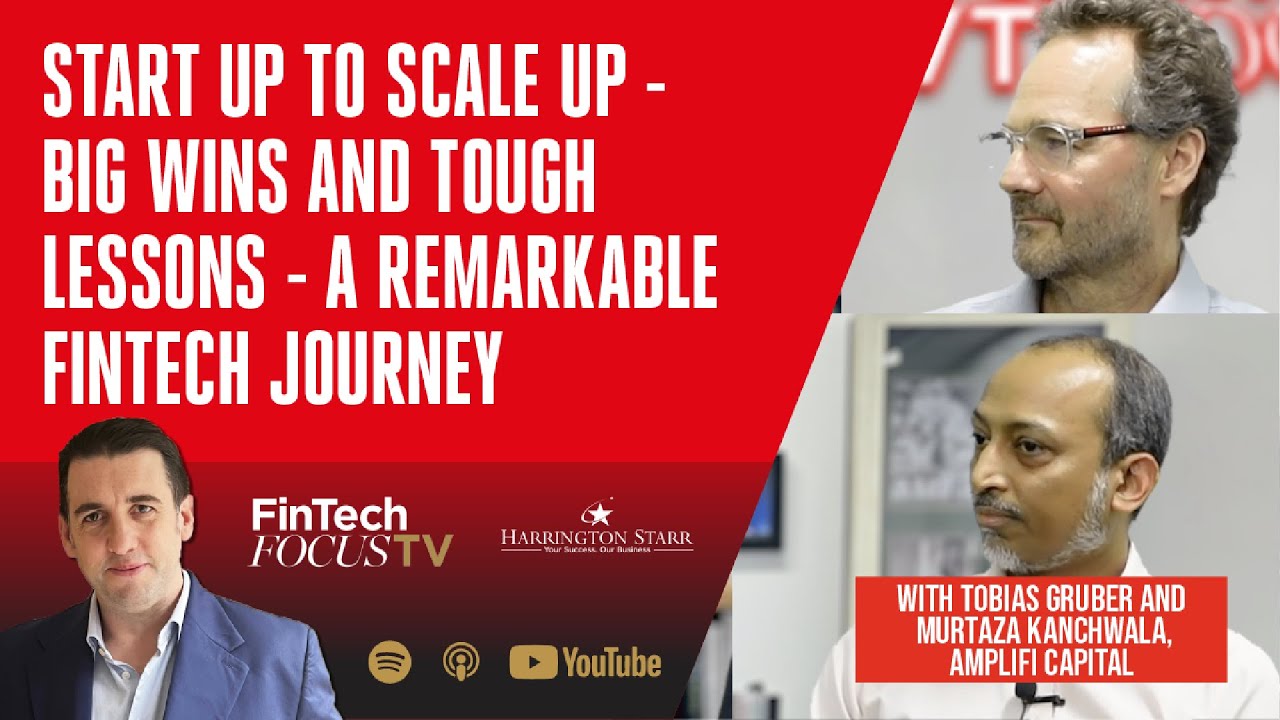
In an April 2025 conversation with Toby Babb on FinTech Focus TV, Gruber traced his interest in credit unions to a sector he thought Britain had left underdeveloped compared with countries such as the United States and Ireland. He had worked in Zurich and London for nearly 30 years. The attraction was an existing institutional form with room to do more.
The investment pitch contained a complication that would try the patience of any slide deck: mutual ownership. Gruber described a structure in which Amplifi could supply almost all the capital yet have only one vote among the members. He also recalled an eventual investor watching the business for 18 months before committing. Persuasion had a longer timetable than the application form.
Borrow the software. Build the connections.
By January 2020, Gruber was appearing as CEO of Gojoko Marketing in a joint announcement with Persistent Systems. Their Community Lenders Gô Digital platform combined a customer-facing service with banking components running on Amazon Web Services. Persistent handled systems integration, including getting loans into Mambu’s banking platform. The ambition was to let credit unions introduce and operate products without building every piece themselves.
“The opportunity for credit unions in the UK is tremendous,” Gruber said at the launch. It was a statement about unused capacity as much as unmet demand. Smaller lenders needed the means to find customers, check applications and maintain accounts. Putting those functions together could make a modest institution accessible to a much larger audience.
The approach depended on partnerships. Gojoko’s account of its services included underwriting, customer management, risk management and credit control. Its technology choices favoured adapting established software. There is something refreshingly unfashionable about that decision. Reinventing the wheel makes for an excellent presentation; buying wheels gives you more time to worry about the brakes.
The same preference for practical capability appears in Gruber’s public comments about competition. In a Persistent customer case study, he argued that smaller organisations had to respond more quickly than wealthy, established rivals. Speed meant being able to change operations and products as conditions changed. It required useful relationships between systems and people, alongside a pleasant screen.
Two routes to the same borrower
My Community Finance, launched in 2018, provided the customer-facing route into loans and savings from My Community Bank and Castle Community Bank. Amplifi acted as an introducer and supplied supporting services. Reevo Money, launched in 2022, added a different route: Amplifi’s own consumer lending platform. The distinction mattered because introducing a borrower to another lender and financing a loan directly create different demands on a business.
The intended customer was often described as near-prime: someone outside the terms offered to the strongest credit applicants. Gruber’s stated ambition was to extend access to people traditional lenders had turned away. That aim involved the awkward work of deciding when a second look was justified. A lender still had to assess an applicant and arrange the money behind an offer.
In September 2023, Amplifi announced a NatWest financing facility of up to £100 million for Reevo. Gruber marked it publicly as another milestone. In February 2024, M&G supplied £22.5 million of mezzanine funding to complement that facility. These were lending finance arrangements. They gave the business capacity to expand its loan offering, with the obligations that accompany borrowed capital.
The financing would let Amplifi “continue offering customers access to credit when traditional lenders have turned them away,” Gruber said in the 2024 announcement. The line explains what he wanted the financing to accomplish. The customer’s rejected application sat at one end of the chain; institutional funders sat at the other. Amplifi’s work was to make the connection viable.
A second look needs better evidence
The effort to look beyond a conventional credit decision continued into September 2025. Amplifi partnered with D•One, the open-banking business within ClearScore, to use categorised transaction information. Income and expenditure data could add detail to the picture supplied by credit-reference agencies. Gruber presented the partnership as a way of making lending decisions fairer and more inclusive.
There was a recognisable consistency here. At Gojoko, the missing ingredient had been operating infrastructure for smaller institutions. With open banking, it was information about the applicant. Both approaches tried to give a decision-maker something useful that the existing arrangement failed to provide. The ambition depended on doing the unglamorous work accurately, account by account.
Public milestones followed the growth. Gruber celebrated Amplifi’s inclusion in the Sunday Times 100 list in 2024. A year later, his filmed conversation with chief technology officer Murtaza Kanchwala dealt with scaling a fintech business, recruitment and the role of data. The business had acquired enough complexity that the conversation extended well beyond getting the first customers through the door.
Then the chronology changed. Robert Spence and Gareth Slater of Interpath were appointed joint administrators of Amplifi Capital (UK) and Gojoko Marketing on 9 June 2026. Attempts to restructure the business had failed. New lending stopped. Servicing continued, and the credit unions held their own customers’ savings. The institutional boundaries that were easy to overlook during expansion became essential to understanding what happened next.
Gruber’s CEO tenure had reportedly ended in April. That timing belongs alongside the administration date. His years of leadership are part of the company’s history; so is the subsequent formal process. The record supports both the venture’s earlier ambition and its eventual interruption. A profile that stopped at the financing announcements would leave the reader halfway through the story.
The next spreadsheet has carbon in it
Arcanum Consulting places Gruber in another setting. Based in Zug, the consultancy describes work on fintech businesses and environmental technology ventures. Its published projects include Safer Earth, a carbon-credit venture in Chile, and the technical and regulatory foundations of a European residential lending platform. These are descriptions of advisory work and projects in development. Their language returns repeatedly to funding structures, operating plans and regulation.
His writing there is particularly revealing about the professional questions that interest him. In an essay on mineralisation-based carbon removal, he considers how scientific assumptions become financial ones. The rate at which a material reacts affects expected output. Output affects revenue. Uncertainty has to appear somewhere in the model. A spreadsheet can be tedious company, but it does insist on introductions between numbers that would prefer never to meet.
In a separate essay on bankable carbon projects, Gruber discusses long-term models, the order in which investors receive cash, and legal arrangements across borders. He uses Safer Earth as an example. The emphasis is on the machinery behind an environmental claim: assumptions that can be checked, rights that can be traced and arrangements a prospective funder can examine.
Another article, about climate-tech investors in 2026, stresses credible timelines, operating economics, governance and independent verification. It warns against plans that need exceptionally favourable assumptions to make the numbers work. Those are his published arguments. They also make an interesting companion to the earlier venture, whose appeal rested on connecting useful institutions with the resources to grow.
The second look has to be more demanding than the first.
The question running through a career
There is no need to turn that sequence into a tidy conversion story. Gruber’s public work already supplies a more interesting thread. He has moved between large banks, lending platforms, credit unions and advisory projects, repeatedly working on the arrangements that make money available. The objects change: a household loan, a mortgage platform, a carbon project. The obligation to persuade someone to fund them remains.
The small door that first drew him towards credit unions opened onto a complicated business. His current writing keeps returning to the complications: evidence, governance, cash flows, implementation. For a career built around giving propositions a second look, that is a fitting place to continue. The second look has to be more demanding than the first.
Follow the work
- Arcanum Consulting: current work
- Tobias Gruber on LinkedIn
- FinTech Focus TV: the 2025 interview
- Gojoko: career biography
- Persistent: the 2020 platform launch
- NatWest financing: September 2023
- M&G financing: February 2024
- Open-banking partnership: September 2025
- Amplifi CEO departure: reporting
- Interpath: administration announcement
- Climate-tech investors: Gruber’s essay
- Carbon removal and financial models
- Structuring a bankable carbon project