An envelope is a modest thing on which to build a corporate career. It exists to carry something else. Gerald F. Mahoney looked at the businesses making them and saw room for a much larger arrangement: local factories, familiar customers, experienced managers, all connected by a company with the money to keep buying. The interesting part was what he thought should happen after the purchase. A new owner, in his view, could easily become the most expensive nuisance in the building.
At a 1997 discussion about international business, Mahoney advised buyers against arriving as conquering heroes. Learn the people. Slow down the cultural changes. A successful regional manager might understand customers better than a distant headquarters ever would. His blunt prescription was to “leave him the hell alone”. For an executive whose company was expanding through acquisitions, it was a revealing choice of emphasis: ownership did not automatically confer superior local judgment.
The small company before the big numbers
Mahoney became chairman, president and chief executive of Pavey Envelope and Tag Corporation in 1991. The New Jersey manufacturer preceded Mail-Well, the business later known as Cenveo. That distinction matters. The story began with a small operating company; the public corporation, its financing and its growing collection of businesses came afterward. Looking backward through the later company name can make the starting point seem rather grander than it was.
The early structure of Mail-Well explains the ambition. In February 1994, Pavey was combined with Georgia-Pacific’s envelope business under the ownership arrangement assembled by Sterling. The Georgia-Pacific operation cost $155.1 million; Pavey cost $4.4 million. Mail-Well began with 16 manufacturing plants. Its chairman and CEO had moved from running an individual envelope business to directing a collection of factories with a much wider footprint.
That opening balance sheet also supplied a warning label. Mail-Well started with $142 million in debt against $17 million in equity. The promise of scale arrived with obligations attached. An acquisition could add customers, production capacity and purchasing power, while also increasing the amount the business had to earn simply to support its financing. Envelopes were ordinary. The financial construction around them was considerably less so.
The commercial idea was straightforward. Regional suppliers knew their markets, while customers operating across several regions could benefit from a supplier with plants in several places. A collection of local businesses could offer that reach without asking every customer to start again with an unfamiliar factory. Mahoney’s problem was to assemble the network while preserving enough of the relationships that had made its individual pieces worth buying.
Buy the factory. Keep the judgment.
By December 1998, Mail-Well was announcing agreements for Imperial Litho & Dryography in Phoenix and Trafton Printing in Amarillo. Imperial brought $26 million in annual sales; Trafton brought $8.5 million. The sizes differed, but Mahoney highlighted the same feature in both transactions: their senior management teams would stay in their existing positions. Continuity was part of what the buyer wanted to acquire.
The sellers described benefits that were practical rather than ceremonial. Imperial’s president, Malcolm Marr, pointed to help keeping up with printing technology and a wider range of work. Rick Trafton, the founder’s grandson and the company’s president, emphasized access to additional services, including web printing. A local printer could join a larger group and offer customers capabilities beyond its own equipment. There was a sales argument here as well as a financing argument.
“It’s tough to break old habits.”Gerald F. Mahoney, 1997
In the same round of deals, Mail-Well acquired Perfection Forms and Apico, two business communications printers in Kansas. Those operations were to be merged into an Apico-Perfection division under Jerry Leeds, then Apico’s president. The arrangement shows that decentralization did not mean a promise to leave every organizational chart untouched. Decisions about what to combine still had to be made, with people chosen to run the resulting business.
Mahoney’s comments about a Canadian manager make the distinction particularly clear. He admired the manager’s ability to earn profits and work with people, even while acknowledging differences from the way he might have operated in the United States. The implication was almost comically unfashionable for a corporate owner: sometimes the useful contribution from headquarters was restraint. A manager who understood a regional business could be an asset precisely because he did things his own way.
The figures acquire some weight
Mail-Well went public in September 1995. By the second quarter of 1999, it was reporting $439 million in quarterly sales, up 25 percent from the comparable period a year earlier. Net income was $15 million, a 33 percent increase. It was the company’s thirteenth consecutive quarter of record sales. These figures describe a business whose acquisitions were appearing in the income statement, quarter after quarter.
Mahoney emphasized improving margins across the businesses. The company also completed four acquisitions during that quarter and added $50 million in borrowing capacity through a new accounts-receivable financing facility. The operating and financial machinery were running together: purchases expanded the group, while access to capital helped support the next stage. Rising sales alone could never describe the whole undertaking.
By October 2000, the tone was more qualified. Third-quarter earnings from operations had fallen short of the company’s original expectations. Earnings per share were 25 cents before restructuring and other charges, and 14 cents after them. The adjustments included asset write-downs and severance-related restructuring costs. Mahoney pointed to improvements in the envelope segment, but the announcement put the less photogenic side of consolidation directly beside the growth figures.
His retirement became effective on January 31, 2001. Paul Reilly, the president and chief operating officer, succeeded him as chief executive; Tom Stephens became chairman. The division of those responsibilities marked a clear handover. Mail-Well had grown far beyond Pavey, and the next phase belonged to another leadership team. Mahoney’s place in Cenveo’s history rests on that earlier building period, before the later name appeared.
Retirement, with operating responsibilities
The word retirement proved to have generous margins. In August 2002, Mail-Well sold its filing products division to International Filing Company. Mahoney, management and other investors had formed IFC Filing to carry out the purchase. His former company was simplifying its portfolio and reducing debt; he was participating on the buying side. The same set of assets could look dispensable to one owner and useful to another.
That October, Workflow Management nominated him to its board alongside Peter Redding, the former chief executive of Standard Register. By January 2003, Mahoney was Workflow’s interim CEO, responsible for day-to-day operations while a permanent replacement was sought. The appointment accompanied a new credit agreement intended to stabilize the company’s relationship with its lenders. This assignment required attention to an existing business and its balance sheet, rather than the construction of another acquisition network.
Gary Ampulski was appointed chief executive in March 2003, with Mahoney remaining on the board. A year later, Mahoney, by then chairman, returned as interim CEO. Workflow was working toward a sale to WF Holdings, controlled by Perseus and The Renaissance Group. His stated priorities included maintaining continuity for employees, customers and vendors, and satisfying the company’s credit obligations. Here, the measure of progress was getting a transaction completed while the business continued to function.
The merger closed on April 26, 2004, with shareholders entitled to $5.56 in cash per share and Workflow becoming a subsidiary of WF Holdings. It was a different kind of conclusion from an IPO. Instead of bringing a company onto the public market, the transaction took it into new ownership. Mahoney’s post-Mail-Well work had taken him through both the operating chair and the boardroom chair, sometimes with little distance between them.
A return to Garden City
There was another institution to which Mahoney returned. He earned his mathematics degree at Adelphi in 1965, followed by a master’s in accounting at Northeastern. In June 2007 he joined Adelphi’s board of trustees. The university honored him that September at its nineteenth annual Golf Classic, held at Cherry Valley Club in Garden City. The occasion put an alumnus back among people raising money for students.
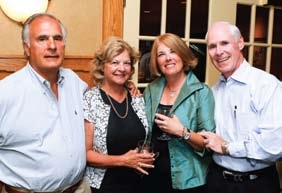
More than 60 foursomes participated, and the event raised over $112,000 for athletic scholarships. Mahoney received the President’s Award for Outstanding Achievement and Friendship. The photograph from the occasion places him beside his wife, JoAnne, and Frank and Marie Braccia, smiling with a drink in hand. It is a useful change of scale after the factories, financing facilities and quarterly comparisons: four people, a university gathering, a reason to celebrate.
His route into college had itself involved a personal connection. A Brooklyn native and the first in his family to attend college, he came to Adelphi with encouragement from family friend and biology professor Louise Heim. He initially favored its engineering partnership with MIT, then chose mathematics and stayed. He also led his fraternity and the Inter-Fraternity Council. The career that followed would give him plenty of practice with numbers and groups of independently minded people.
The envelope business remained part of his life after the public-company handovers. In 2009, he joined management, Palm Beach Capital and fellow industry veterans Richard Schlanger and Bob Fishbein in the buyout of United Envelope. By 2012, his activities included private-company investing and board work. For all the changes in title, the recurring interest was recognizable: established businesses, people who knew their trade, and the question of what a different ownership arrangement might make possible.