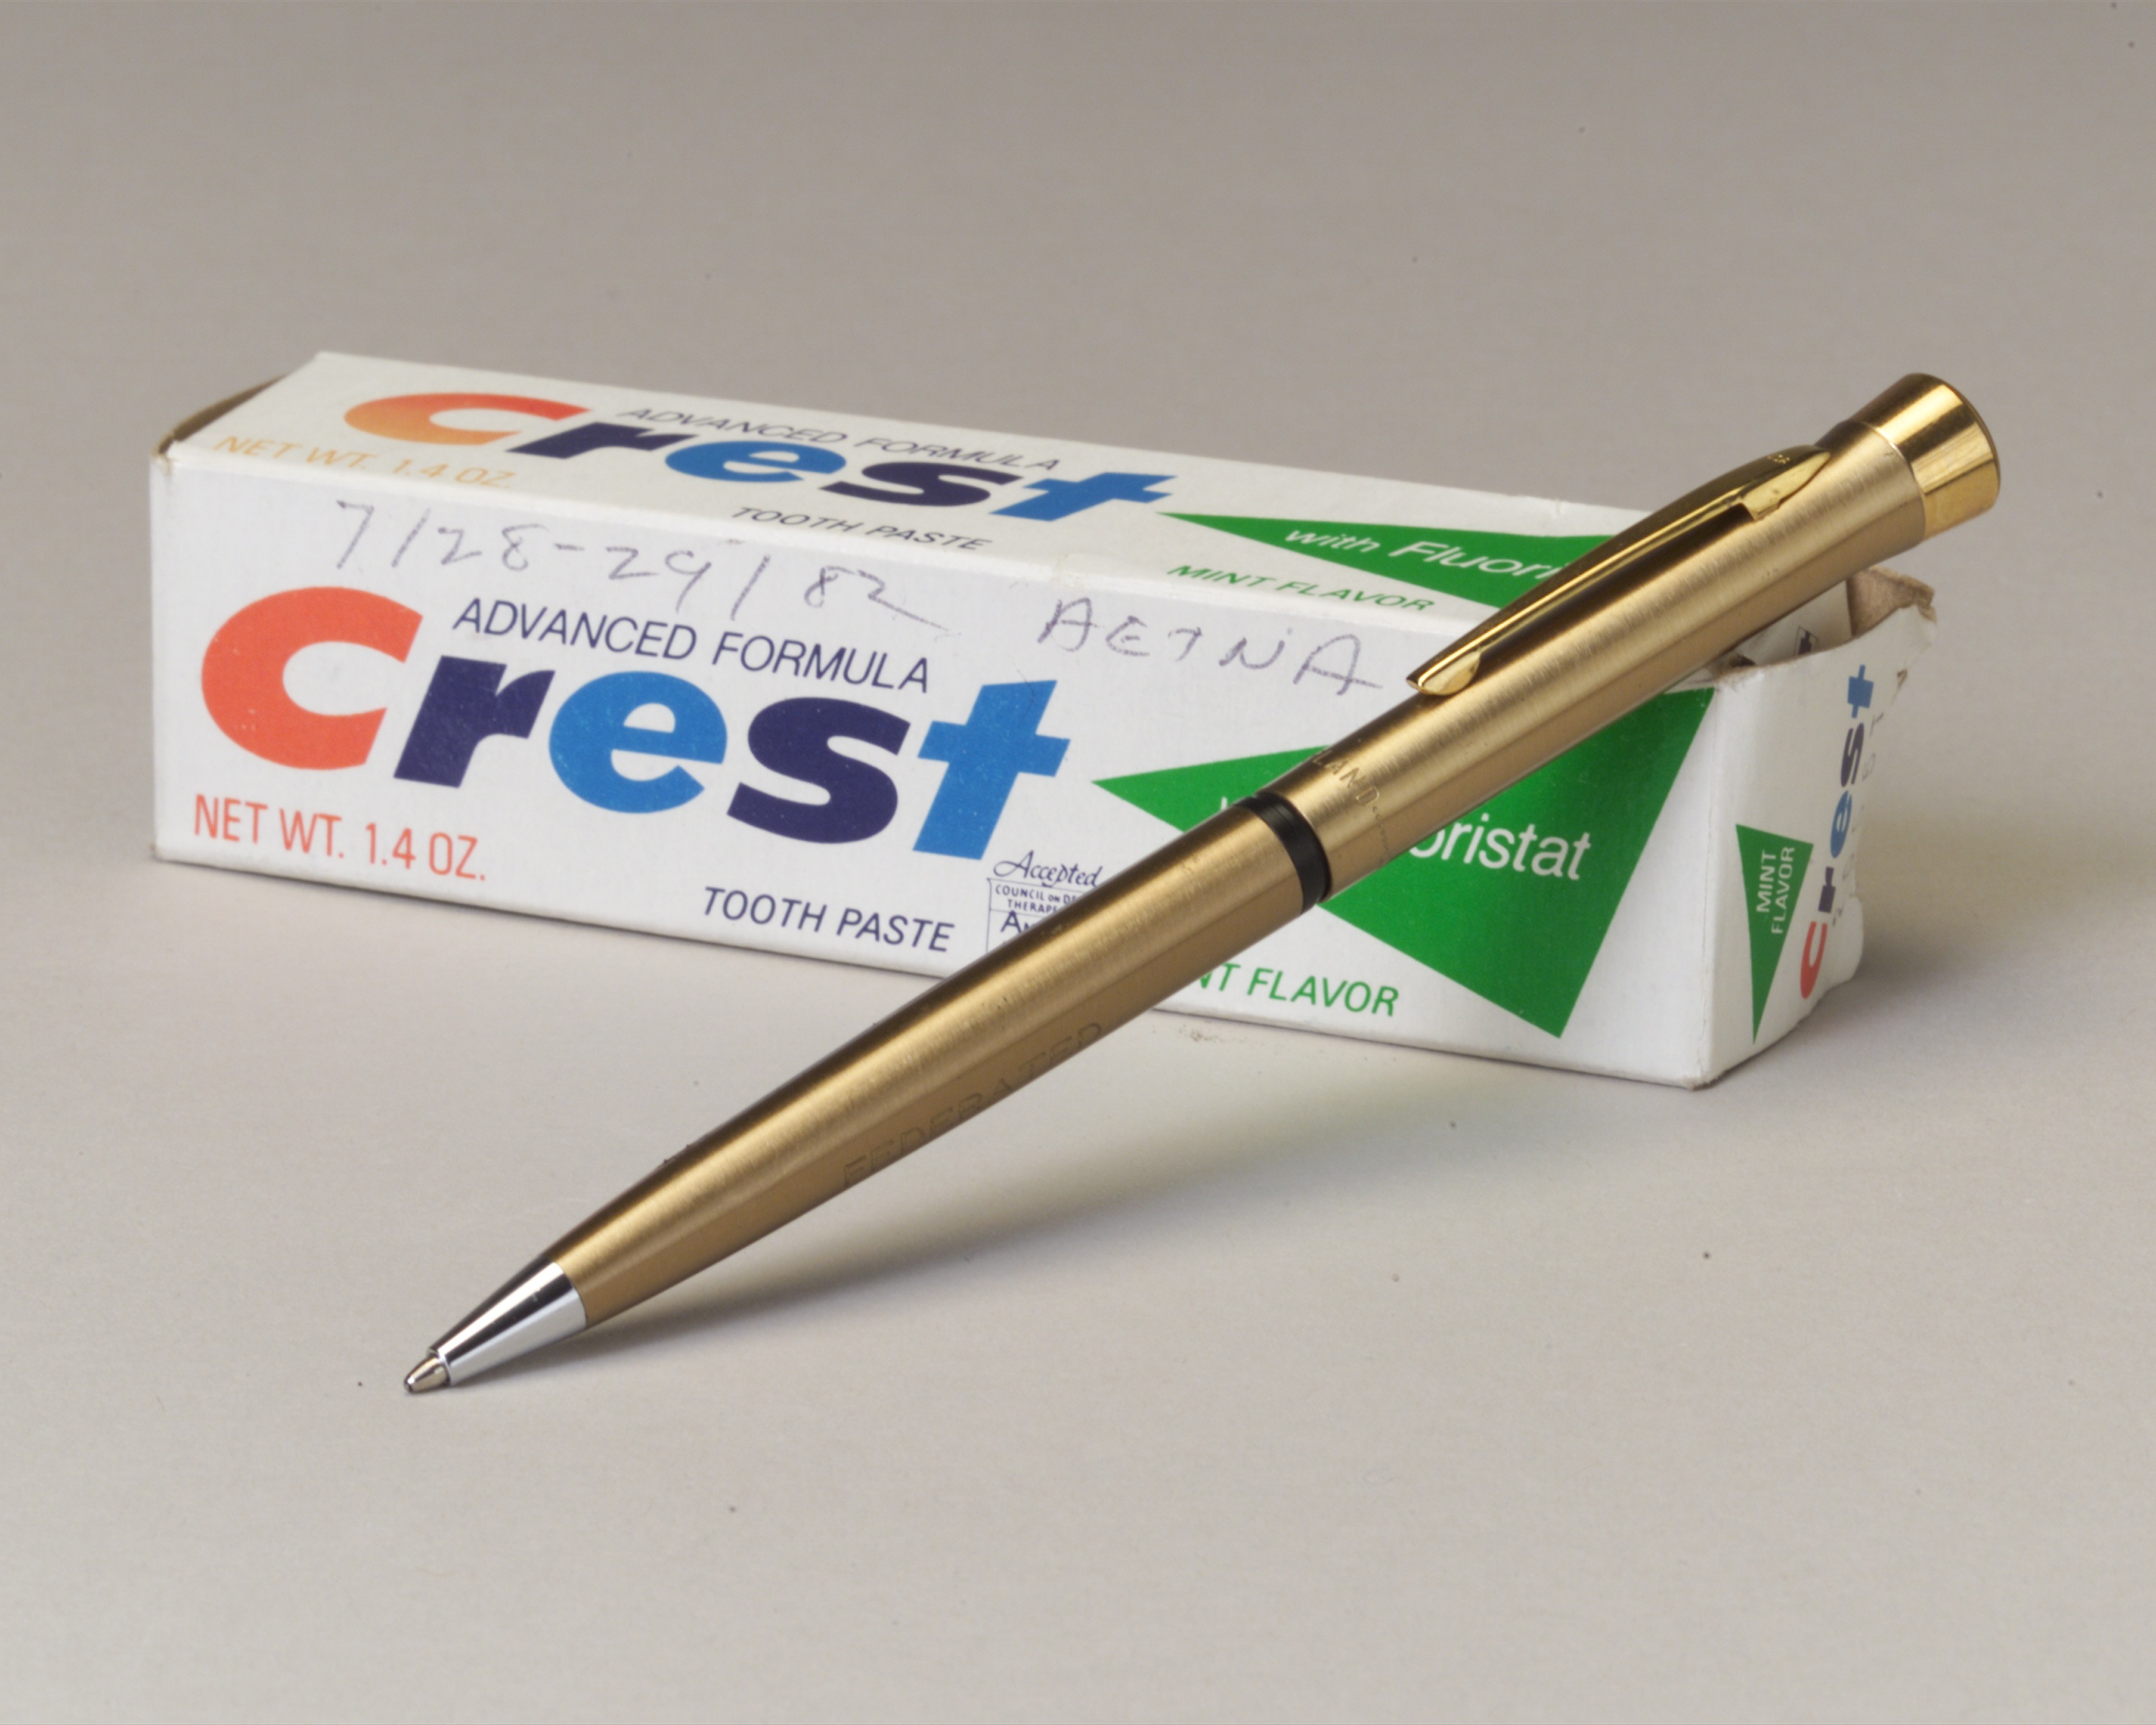
The toothpaste box is an unlikely corporate trophy. On its side, a handwritten date records an all-night negotiation in 1982, when Federated was sold to Aetna. Founder Jack Donahue used the toothpaste before meeting the press. Most companies preserve the signed agreement. Federated preserved the evidence that someone needed to brush his teeth.
- Cash is the engine. Money markets held about 74% of managed assets in June 2026.
- Relationships are the route. Banks, brokers and institutions bring the firm to investors.
- Expansion has a price. Acquisitions added expertise, alongside costs and write-downs.
Seven years later, Federated bought itself back. Decades later, the Pittsburgh company would buy a majority stake in London’s Hermes, take a combined name and stretch from overnight cash to property and infrastructure. The toothpaste box remains a useful introduction: this is a financial institution built through very human negotiations over who gets to manage other people’s money.
The business between decisions
John F. Donahue and Richard B. Fisher, former high school classmates, founded Federated in 1955 with legal counsel Thomas J. Donnelly. Money spends much of its life waiting. A corporation receives cash before paying suppliers. A pension fund holds liquidity before investing. A broker needs somewhere to place customer balances. The task sounds modest until the balance has nine zeroes and the owner wants liquidity, a competitive yield and careful risk management simultaneously.
Federated made that interval a specialty. In 1974, it launched the first mutual fund to put “money market” in its name, according to its corporate history. An institutional-only money market fund followed in 1976. By June 2026, its money market assets were approximately $677 billion, within total managed assets of $911.6 billion.
These products pool investors’ money into short-term instruments. The exact holdings depend on the fund: government, prime and municipal strategies serve different needs. The customer is buying a process for managing liquidity and credit exposure, with a fund structure and operating machinery attached. Cash management becomes a daily service, even when the investor barely notices it.
For a potential client, the useful question is which job needs doing. A treasury team managing upcoming payments has different requirements from an endowment seeking returns over years. An adviser may want an ETF; an institution may need a separate account. The practical comparison is therefore among specific strategies, their fees, holdings, risks and access terms. The company name alone cannot answer those questions. Its range makes several conversations possible, but each portfolio still has to fit the investor’s timetable and tolerance for loss.
The firm serves more than 11,000 institutions and intermediaries worldwide. Corporations, insurers, government entities, foundations, banks and broker-dealers appear in that audience. Individuals can encounter its funds through financial advisers and platforms. Federated often works through a relationship the investor already has, an arrangement that makes distribution part of the business’s substance.
A dollar of assets is not a dollar of business
Here is the accounting wrinkle. In the second quarter of 2026, money market assets generated 50% of revenue. Long-term assets generated 48%; other sources supplied 2%. Roughly three-quarters of the asset base was producing half the revenue. A money manager’s headline size conceals the different economics of what it manages.
Cash occupies more space than it earns.
Federated earns advisory, administrative and other service fees. Some strategies also generate performance fees or carried interest. Its 2025 revenue was approximately $1.80 billion. The hundreds of billions entrusted to its portfolios belong to clients; they are neither the company’s sales nor a pile of cash it can spend.
The cash franchise has an awkward condition: very low interest rates can squeeze the economics. When gross yields cannot cover expenses, managers may waive fees. In 2021, Federated’s voluntary yield-related waivers totaled $420.3 million. Reduced distribution expenses absorbed much of that amount, leaving a $143.2 million negative pretax impact.
That episode identifies a practical limit. A recurring customer need can sustain demand while the price of serving it becomes uncomfortable. The lesson for another business is to examine what happens to the margin when the operating environment turns against the product.
Buying a longer clock
Federated’s answer to a broader set of investor needs includes active stock selection, bond portfolios, quantitative strategies through MDT Advisers and private-market investments. Mutual funds, ETFs and separate accounts provide different ways to access the work. Fidelity, BlackRock and J.P. Morgan compete for overlapping mandates; Vanguard offers an alternative for investors prioritizing low-cost public-market exposure. Federated’s particular combination is a large liquidity franchise alongside specialist active teams and stewardship services.
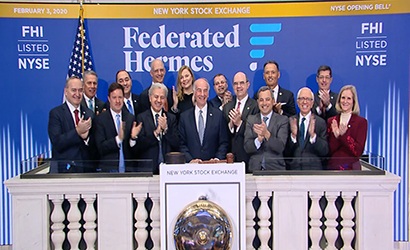
The 2018 Hermes acquisition widened that combination. Federated bought an initial 60% interest from BT Pension Scheme. The total purchase price, including excess regulatory capital, was £259.9 million, or $341.5 million at the disclosed exchange rate. It added international investment capabilities and a business associated with responsible ownership.
Through EOS, stewardship itself becomes a service: engaging companies, making voting recommendations and advising institutional owners. Assets covered by that advice are a separate measure from assets managed in portfolios. Adding those numbers together would flatter the headline and confuse the reader.
“I will act ethically, responsibly and with integrity.”From the Federated Hermes employee pledge
The pledge makes the client-first culture explicit. Acquisition accounting supplies a less comfortable test. In 2024, lower gross sales and higher redemptions led management to reassess an acquired right to manage Hermes public funds. The result was a $66.3 million noncash impairment. The documented change was in the asset valuation: actual business had fallen behind expectations.
Expansion continued. In April 2026, Federated completed its purchase of 80% of FCP Fund Manager, a US multifamily real estate specialist with $3.5 billion in client assets at the previous year-end. Property investing runs on a different clock from cash management. The combination broadens the menu; it does not make those investment horizons interchangeable.
The wrapper changes. The relationship stays.
In October 2026, Federated announced a planned tokenized-fund partnership with Prometheum. The first product is expected in the first quarter of 2027. Federated supplies investment expertise; Prometheum’s broker-dealer infrastructure supports distribution, custody, clearing and settlement. The announcement describes an intended route to market, rather than a completed launch.
The appealing detail is the familiar intermediary inside the new technology. The plan reaches toward brokerage accounts and adviser relationships. My reading of the pattern: Federated keeps adapting the vehicle while preserving the route to the customer. That is a useful idea to borrow. Start with a problem that returns tomorrow morning. Make the solution convenient for the people already trusted to deliver it.