Chris Harrison has an unusual proposition for anyone who equates a chief executive’s success with the length of the company’s inventory: sometimes the arithmetic improves when the inventory gets shorter. At Quorum Health, the company he leads from Brentwood, Tennessee, a reduced portfolio has accompanied a reconsideration of how the whole enterprise should be financed. The ambition is continued operation. The instrument is corporate structure. It makes for a business story in which the interesting action happens several floors below the victory speech.
Harrison arrived at Quorum in July 2020 to lead financial planning and analysis. He became chief financial officer in April 2022 and chief executive in June 2023. In May 2026, the company announced an agreement intended to move its operations from a private equity backed, for-profit model into a nonprofit organization operating as Healthside Partners. The executive who once supervised the financial forecast was now helping change the framework in which the forecast would be made.
That sequence is the useful way into Harrison’s story. His public career runs through accounting, financial operations, reporting, and executive responsibility. There is no need to give the spreadsheet a personality of its own. The person reading it has decisions to make, and those decisions eventually reach employees, business partners, and communities a long way from the corporate office.
An accountant gets the larger desk
Harrison holds a Bachelor of Science from Tennessee Wesleyan University and a master’s in accountancy from Belmont University. He is an active certified public accountant. Before Quorum, his employers included HCA Healthcare, LifePoint Health, Beaumont Health, and Surgery Partners. His immediately preceding position was a vice president role at Surgery Partners. These are the building blocks of a career spent inside sizable organizations, learning how financial information connects to the work of operating them.
Financial planning and analysis offers a particular vantage point. A budget is a collection of decisions expressed in numbers; a forecast tests whether those decisions still make sense. Someone working at that junction has to understand both the figures and the assumptions behind them. Harrison’s progression at Quorum placed that discipline increasingly close to the authority to act. Less than three years separated his arrival from the announcement that he would lead the company.
The June 2023 appointment paired Harrison’s promotion with another internal move: Hank Kunath became executive vice president and CFO. Kunath had joined the previous year as vice president of accounting and corporate controller. The succession put two executives with direct experience of Quorum’s finances into its senior leadership. Harrison’s own public response welcomed the opportunity and singled out Kunath’s ability to step into the finance role. Even a promotion to the top job involves handing someone else the calculator.
- 2020July
Joins as SVP, financial planning & analysis - 2022April
Becomes chief financial officer - 2023June
Appointed chief executive officer
Eleven operations, nine states, one awkward map
Quorum’s current website describes a portfolio of 11 hospitals in nine states. As a piece of corporate geography, that is a revealing ratio. A national presence can sound reassuringly large until one asks where the locations actually sit in relation to one another. Being spread across a country and being concentrated within a market are different business conditions. A map can make a company look substantial while also showing why coordination is expensive.
Harrison has made the geographical problem explicit when explaining the proposed ownership change. The portfolio’s dispersion limits the advantages the company can obtain from concentration in individual markets. In the same discussion, he described the previous portfolio reductions as a way to improve financial performance and focus. The argument asks readers to consider what the company can sustain rather than treating the number of properties as a scoreboard.
That is a fairly bracing message from a chief executive. Corporate language tends to favor expansion, with enough arrows pointing upward to make an escalator envious. Harrison’s account allows subtraction a legitimate place in the strategy. A smaller set of operations can still present a demanding management task; the reduction itself proves little. What matters is what financial room and managerial attention it creates, and whether those resources are put to productive use.
The work behind the work
A second part of Harrison’s strategy concerns the machinery that allows organizations to function: information technology, billing administration, data systems, and the people who know how to keep them running. In November 2025, he discussed Quorum’s plans for a management services organization, or MSO. The proposed offering would help other operators handle administrative and technical work that can be costly to maintain independently.
The opportunity emerged from difficulties around transition service agreements connected to former Steward operations. These agreements cover support during a change of ownership. Quorum acquired a supporting operation and its employees, giving the company a base from which to develop a broader services business. An immediate operational problem thus supplied the raw material for another line of work. The attraction lay in applying experience the company already needed for itself.
Shared services have an unglamorous vocabulary. Vendor management rarely sells a keynote ticket on its own. Yet there is a practical entrepreneurial idea here: expertise accumulated inside one organization may have value to another. In Harrison’s case, the proposition extends beyond owning locations. It includes supplying some of the capabilities that other owners need. The distinction matters because a company can broaden the usefulness of its knowledge without simply adding more properties to the list.
An open mind has operational uses
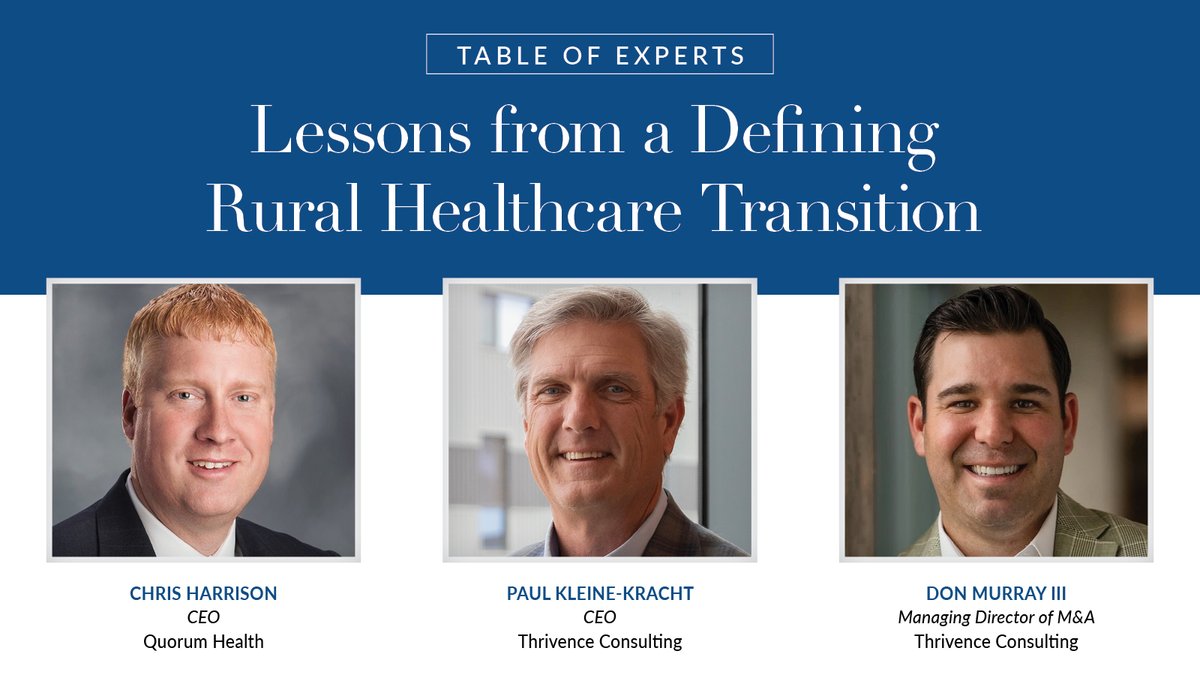
Harrison’s collaborators include Paul Kleine-Kracht and Don Murray III of Thrivence Consulting. In an August 2026 business roundtable, he described bringing that team into a transition involving technology, vendors, and support agreements. A previous working relationship helped establish the connection. His explanation of leadership emphasized listening to partners and keeping employees and other participants informed while the work was under way.
Harrison’s advice was to stay open to partners’ ideas. That is a plain prescription, and useful for being plain. It puts an obligation on the executive to receive information as well as issue instructions. A transaction brings together people who understand different parts of the operation. Their knowledge does not become available merely because a new reporting chart has been circulated.
There is a modest consistency between that account and the language Harrison uses on his public professional profile, where he describes an entrepreneurial approach to financial operations. The combination is interesting: someone trained to examine the numbers also makes a public case for rethinking the arrangement around them. It would be too easy to turn that into a character sketch with every uncertainty removed. The observable point is narrower. His proposals have included changing the portfolio, developing a services platform, and pursuing a different ownership model.
“You need to be open-minded and listen to new ideas or ways of doing things.”Chris Harrison · August 2026
Changing the container
The May 21, 2026 agreement names QKA Health Corporation, doing business as Healthside Partners, as the nonprofit counterparty. Quorum said the change would make philanthropic support, tax-exempt funding, and expanded partnerships available to the organization. It also said Harrison and the senior executive team would remain. In that plan, continuity of leadership sits alongside a substantial alteration in the financial and governance structure.
The business logic deserves to be stated with its verbs intact. The proposed structure would open funding possibilities; an agreement does not itself deliver the resulting benefits. A lower financing burden can create room for investment, but management still has to decide what to fund, execute the work, and account for the result. Changing the container does not relieve anyone of responsibility for what goes into it.
By October, the transaction had reached a concrete regulatory milestone. Oregon’s reviewing authority completed its preliminary review on October 7 and approved the proposal with conditions. An amended proposed order followed on October 8. The conditions reported for the Oregon operation include retaining a local board for at least five years, investing profits in the communities served, and publicly reporting progress annually. Approval in one jurisdiction is a step in the process; it should not be mistaken for the closing announcement.
Those details bring the story back to accountability. A promise about the future becomes easier to assess when it has a time period, a governance requirement, or a report attached. For Harrison, whose route to leadership passed through financial analysis, the next chapter carries a familiar demand: show the working. An ownership proposal can be explained elegantly. Its consequences will take longer to measure.
May 21: nonprofit transaction announced.
October 7: approval with conditions. Amended proposed order October 8.
Closing remains a separate milestone.
The next column is still open
There is another pending transaction on the horizon. In June 2026, Banner Health announced an agreement to sell its Susanville, California operation to a Quorum affiliate, with a December closing anticipated and regulatory approvals required. The announcement expected the purchasing affiliate to be nonprofit by completion and said Harrison would remain in place with Healthside Partners. It is a useful reminder that a smaller portfolio need not mean permanent retreat from every opportunity.
Harrison is therefore navigating several kinds of change at once: the practical demands of the existing business, a services proposition for other operators, an ownership transition, and a prospective acquisition. Each has its own timetable. None becomes complete because it fits neatly into a strategic presentation. Running a company through those overlapping processes requires attention to the ordinary work that continues while the extraordinary paperwork is signed.
His career offers a specific picture of executive ambition. The progression from planning and analysis to CFO to CEO is clear. What follows is more provisional: a series of choices about which operations to own, which capabilities to share, and which structure can support them. Harrison’s story is still being written in decisions with due dates. For an accountant in the chief executive’s chair, that seems an appropriately demanding form of authorship.