The modern chargeback begins with absurdly little ceremony. A customer opens a banking app, taps a transaction and says the parcel never arrived, the subscription was forgotten or the purchase was not theirs. The merchant gets the inverse experience: a deadline, a fee and a scavenger hunt through payment records, shipping logs, policies and support messages. The shopper spends seconds. The business can lose hours. Chargeflow exists inside that mismatch.
Its founders, brothers Ariel and Avia Chen, did not discover the problem in a market map. They found it in the ledger of Babe Cosmetics, the cruelty-free beauty and subscription business they had built before Chargeflow. As sales grew, so did disputes. The brothers looked for a service that could assemble evidence, show what was happening and protect margins without turning a growing company into a miniature legal office. They say they could not find one they trusted. So they sold the brand and, in 2021, started building the missing machine.
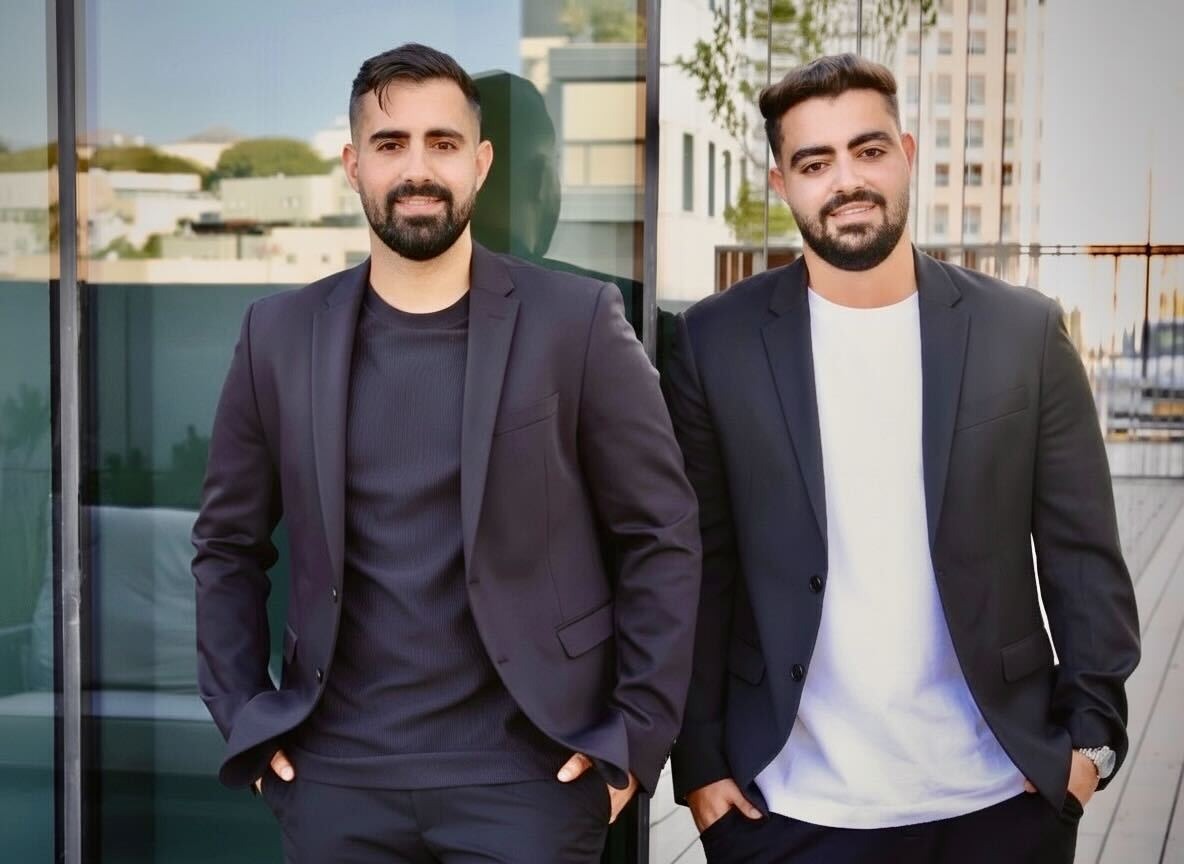
The originThe first thing to fail was time
That founding story matters because chargeback work is less mysterious than it is fragmented. A convincing response might need the original checkout data from Stripe, delivery confirmation from a carrier, cancellation language from a merchant's terms, a customer's message in Zendesk and an account history from an internal database. Someone has to find it, decide what matters, turn it into a bank-readable narrative and submit it before the clock expires.
The same failure appears in Chargeflow's customer accounts. Matt Lewis, head of user operations at AI writing company Wordtune, said he spent a full month managing disputes and concluded that adding headcount would not scale. At Fanatics Live, global trust-and-safety chief Tracy Reeves was reportedly spending more than 25 hours a week handling every chargeback herself. The first broken component was not a model or a database. It was the calendar.
“I spent a full month managing disputes myself, which was slow and unproductive.”Matt Lewis, Head of User Operations, Wordtune
What it doesA five-stop assembly line for one ugly transaction
Chargeflow began as a Shopify app that automated the post-chargeback response. It has since moved left along the transaction timeline. The current suite is easiest to understand as five stations, each catching the same potential loss at a different moment.
Prevent
Scores a paid order before fulfillment; proceed, hold or cancel.
Alerts
Uses card-network signals to refund or resolve before filing.
Automation
Builds, checks and submits a tailored evidence response.
Insights
Combines processor data and watches rates, trends and outcomes.
Connect
Lets payment platforms offer the stack under their own brand.
Prevent is the most revealing addition. Traditional fraud systems concentrate on stolen cards before authorization. Chargeflow's product looks after payment but before the merchant ships, asking a different question: how likely is this identity to create a dispute? It combines behavioral and transaction signals with patterns from a network the company says now covers more than 20,000 merchants. A risky order can be held or cancelled; a clean one proceeds without adding friction at checkout.
Alerts occupies the next window. Signals from Visa's Verifi services and Mastercard's Ethoca network can surface a complaint before it becomes a formal chargeback. A fast refund may sacrifice the sale, but it can avoid the chargeback fee and protect the merchant's dispute ratio. Automation handles what still gets through: collect the records, generate the response and submit the case. Insights watches all of it across connected processors. Connect packages the machinery for payment service providers, fraud platforms and merchants of record as co-branded, white-label or API infrastructure.
What it costsThe bill arrives only when something moves
The business model is more interesting than the AI label. Automation takes 25 percent of money recovered from winning chargebacks and charges nothing on a loss. Chargeflow advertises a four-times return guarantee on that product. Alerts currently costs $29 for a successfully deflected chargeback. Prevent is usage-based at a promotional $0.20 per scanned transaction, down from a $0.40 list price, with the first 1,000 scans free. Insights is free; Connect is quoted for each platform.
Automation
25% of winsNo recovery, no recovery fee.
Alerts
$29Per successfully deflected case.
Prevent
$0.20Current price per scan after 1,000 free.
Insights
FreeThe dashboard is the front door.
This structure removes the argument about buying software before knowing whether it works. A small merchant can connect an account without a contract or minimum and share the upside. It also creates a natural limit: at high dispute volume, 25 percent can become a large number. A sophisticated team should compare it with fixed-price software, an internal operation or another managed service. Alignment makes the first yes easy; it does not end the procurement math.
The proofTwo clicks, fewer disputes, much better weeks
The strongest independent customer evidence comes from Stripe's published Wordtune case study. Wordtune found Chargeflow in the Stripe App Marketplace and connected it in what Lewis described as two clicks. Over the following months, the company reported a 5.4-times increase in its chargeback recovery rate, a 29.7 percent reduction in its dispute rate and a 33.5 percent reduction in fraudulent disputes. Those are Wordtune's results, not a universal forecast, but they show why native distribution matters: the app begins with access to useful payment data.
Chargeflow's own case studies add texture. Fanatics says it recovered more than $800,000 in the first year, doubled its win rate and returned more than 25 hours a week to the trust-and-safety team. Cookware company HexClad reports a 59 percent improvement in recovery rate and 199 hours saved. The products work across very different businesses because the underlying job is repetitive: retrieve facts, apply network rules, make a case, meet the deadline.
The marketRecovery is becoming prevention, then infrastructure
Chargeflow competes with specialist services such as Chargebacks911, Justt, Chargeblast, Disputifier and Midigator, plus processor tools and internal dispute teams. Its distinction is breadth. It is trying to own the full clock rather than a single response step, then let platforms distribute the same system to their merchants. That puts it at the junction of fraud software, payment operations and vertical SaaS.
The company has raised accordingly. An $11 million OpenView-led seed in 2023 followed an undisclosed $3 million pre-seed. In November 2025, Viola Growth led $25 million in Series A equity, accompanied by a $10 million debt facility and participation from OpenView, Journey Ventures and payments executive David Avgi. Chargeflow called the combined financing a $35 million round and total capital $49 million. It also said annual revenue had tripled and its customer base doubled in the preceding year.
By August 2026, Chargeflow had opened a Developer Hub with APIs and webhooks for the end-to-end chargeback lifecycle. This is the strategic tell. A merchant app earns fees one account at a time. An embedded system can arrive inside a processor, billing platform or marketplace and serve many accounts at once. Chargeflow is betting that its accumulated integrations, resolved disputes and cross-merchant signals become more valuable when other software can build on them.
The boundaryWhere the tidy pitch gets untidy
Automation cannot turn weak facts into a valid win. Banks still decide disputes, network coverage varies and a refund triggered by an alert still means surrendering the sale. Prevent's cross-merchant intelligence is useful only when its patterns fit the merchant's customers and risk tolerance. An aggressive rule can stop an abusive buyer; it can also hold a legitimate order. The merchant remains responsible for deciding how much friction is acceptable.
The product is least compelling when dispute volume is tiny, when a processor lacks a native connection, or when a regulated or high-touch team insists on reviewing every piece of evidence by hand. It may also be expensive for a large merchant that already has excellent win rates and efficient staff. Success pricing works best when the alternative is unclaimed revenue and exhausted people, not an optimized in-house desk.
What another operator can copy
- Start with a workflow you have personally paid to endure. The Chen brothers knew the missing data because they had hunted for it themselves.
- Map the loss as a timeline. Fighting after a chargeback worked; Alerts and Prevent moved the product toward cheaper moments.
- Price against an auditable result. A recovered dollar is easier to value than a promise of “efficiency.”
- Use integrations as distribution. Shopify and Stripe were not merely data pipes; they were where merchants already worked and shopped for tools.
- Know the bad-fit customer. Low volume and mature internal operations can make an outcome fee less attractive.
Chargeflow's useful insight is almost comically practical: nobody opens a shop because they hope to become talented at payment disputes. The company turns that unwanted expertise into software, puts a meter on the recovered outcome and keeps expanding toward the moment before the loss. Its long-term question is whether that machinery becomes infrastructure or remains a well-integrated service. Either way, the original problem remains brutally clear - the customer has a button, and the merchant needs a system.