In June 2016, a man who had spent years overseeing the manufacture of American money opened an account to hold money nobody manufactures. Edmund Moy, the former director of the U.S. Mint, became BitcoinIRA’s first customer. He also served as its chief strategist. For a young business asking people to put Bitcoin beside their retirement savings, that was an unusually well-chosen introduction.
- BitcoinIRA connects crypto trading with self-directed retirement accounts.
- Its selling points include custody infrastructure, rollover help, and portfolio tools.
- The crucial trade-off: convenience comes with trading and monthly fees.
The man who used to make the money
BitcoinIRA’s founders, Camilo Concha, Johannes Haze, and Chris Kline, came from self-directed retirement investing. Their earlier business covered assets such as property and precious metals. Bitcoin presented a fresh version of a familiar administrative puzzle: how do you hold an unconventional asset inside a conventional retirement structure?
The opening was partly bureaucratic. In 2014, the IRS classified virtual currency as property for federal tax purposes. That clarification did not endorse Bitcoin or approve an investment product. It gave entrepreneurs a tax framework to work within. The founders still needed retirement custody, secure wallets, and a usable way to connect everything.
The company launched in 2016. Its expertise lay in assembling those pieces. Seen that way, the odd couple in its name makes sense. Bitcoin supplies the novelty; the IRA supplies rules customers already recognize.
Three jobs behind one screen
Today, BitcoinIRA offers access to more than 100 cryptocurrencies and says its community exceeds 200,000 Americans. That community figure should not be read as a count of active, funded accounts. The customer is someone who wants digital assets within retirement savings and would welcome help with the transfer.
The process starts with an account, followed by a contribution, IRA transfer, or eligible employer-plan rollover. Funding takes longer than registration. Once money arrives, customers can trade around the clock through the dashboard or mobile app. The company introduced its iOS and Android app in 2021.
The distinctions matter. BitcoinIRA connects the services. Digital Trust provides retirement custodial services. BitGo supplies digital asset infrastructure associated with multi-signature wallets and cold storage. BitcoinIRA advertises up to $250 million in custody insurance, with coverage varying by asset and custody arrangement. That figure does not promise reimbursement when a coin’s price falls.
The attraction is tax treatment, rather than a different kind of Bitcoin. Traditional IRA earnings generally grow tax-deferred; qualified Roth distributions are tax-free. Eligibility and withdrawal rules still apply. A customer can change the account surrounding an asset without changing the asset’s economic behavior. That separation explains both the product’s usefulness and the temptation to expect too much from it.
The convenience has a meter
BitcoinIRA earns fees when customers transact and hold assets. Its published Crypto IRA rates are 2% per purchase or sale, plus 0.08% monthly custody, with a $20 monthly minimum across linked accounts. Opening an account and depositing cash cost nothing. Distribution, transfer, and account-closure charges can still apply.
The minimum changes the economics. At a constant $10,000 balance, $20 a month amounts to $240 a year, or 2.4%, before trading. At $100,000, the percentage charge works out to $960 annually, assuming the reference value stays unchanged. Small accounts feel the floor most sharply.
What does a year cost?
Constant reference asset value before fees. One purchase of that amount; no sales, price changes, spreads, staking, or other charges. Illustration, not a quote.
Competitors make this a real choice. iTrustCapital publishes a 1% crypto transaction fee. An investor seeking price exposure can also consider a crypto ETF within a brokerage IRA. BitcoinIRA must justify its account structure, asset menu, and service against those alternatives. Being early does not settle the comparison.
The product they stopped selling
One revealing decision involved a feature the company withdrew. BitcoinIRA had offered an interest-earning program through Genesis. In November 2022, Kline told Blockworks that the company had ended support during the second quarter, citing its market assessment and risk management. Genesis subsequently halted withdrawals in November.
“As a precautionary measure and based on our own market assessment and risk management.”Chris Kline, on ending Genesis program support / November 2022
This was a lending relationship, distinct from simply holding coins in custody. Its removal is the useful lesson: adding a yield feature adds another party whose ability to pay matters. A platform’s product decisions include deciding which promises to stop facilitating.
From buying coins to managing them
In November 2023, BitcoinIRA acquired Shrimpy, a crypto portfolio technology business. The announcement described customer demand for more sophisticated tools over the preceding 18 months. The acquisition price was not disclosed. The rationale was clear: customers wanted help managing allocations after buying their first coins.
Crypto Bundles now group assets by themes such as established networks, tokenization, and decentralized finance. Customers can set weekly, monthly, quarterly, or manual rebalancing. Rebalancing sells overweight assets and buys underweight ones. The help center acknowledges that individual trades can fail while the remaining rebalance continues. Automation still lives inside market constraints.
Staking adds another option for eligible assets, with potential protocol rewards. It comes with its own eligibility and operational conditions. Neither staking nor a bundle makes a collection of cryptocurrencies equivalent to a diversified retirement portfolio spanning unrelated asset classes.
There is a useful restraint hidden in the phrase self-directed. Customers make investment decisions; a custodian’s involvement does not turn those choices into recommendations. The company’s human support can help with an account or a transfer, while the allocation decision remains the investor’s. More instruments and more automation expand the menu. They also leave the customer with more choices to understand, especially when several holdings depend on the same crypto market.
Retirement gets a next-door neighbor
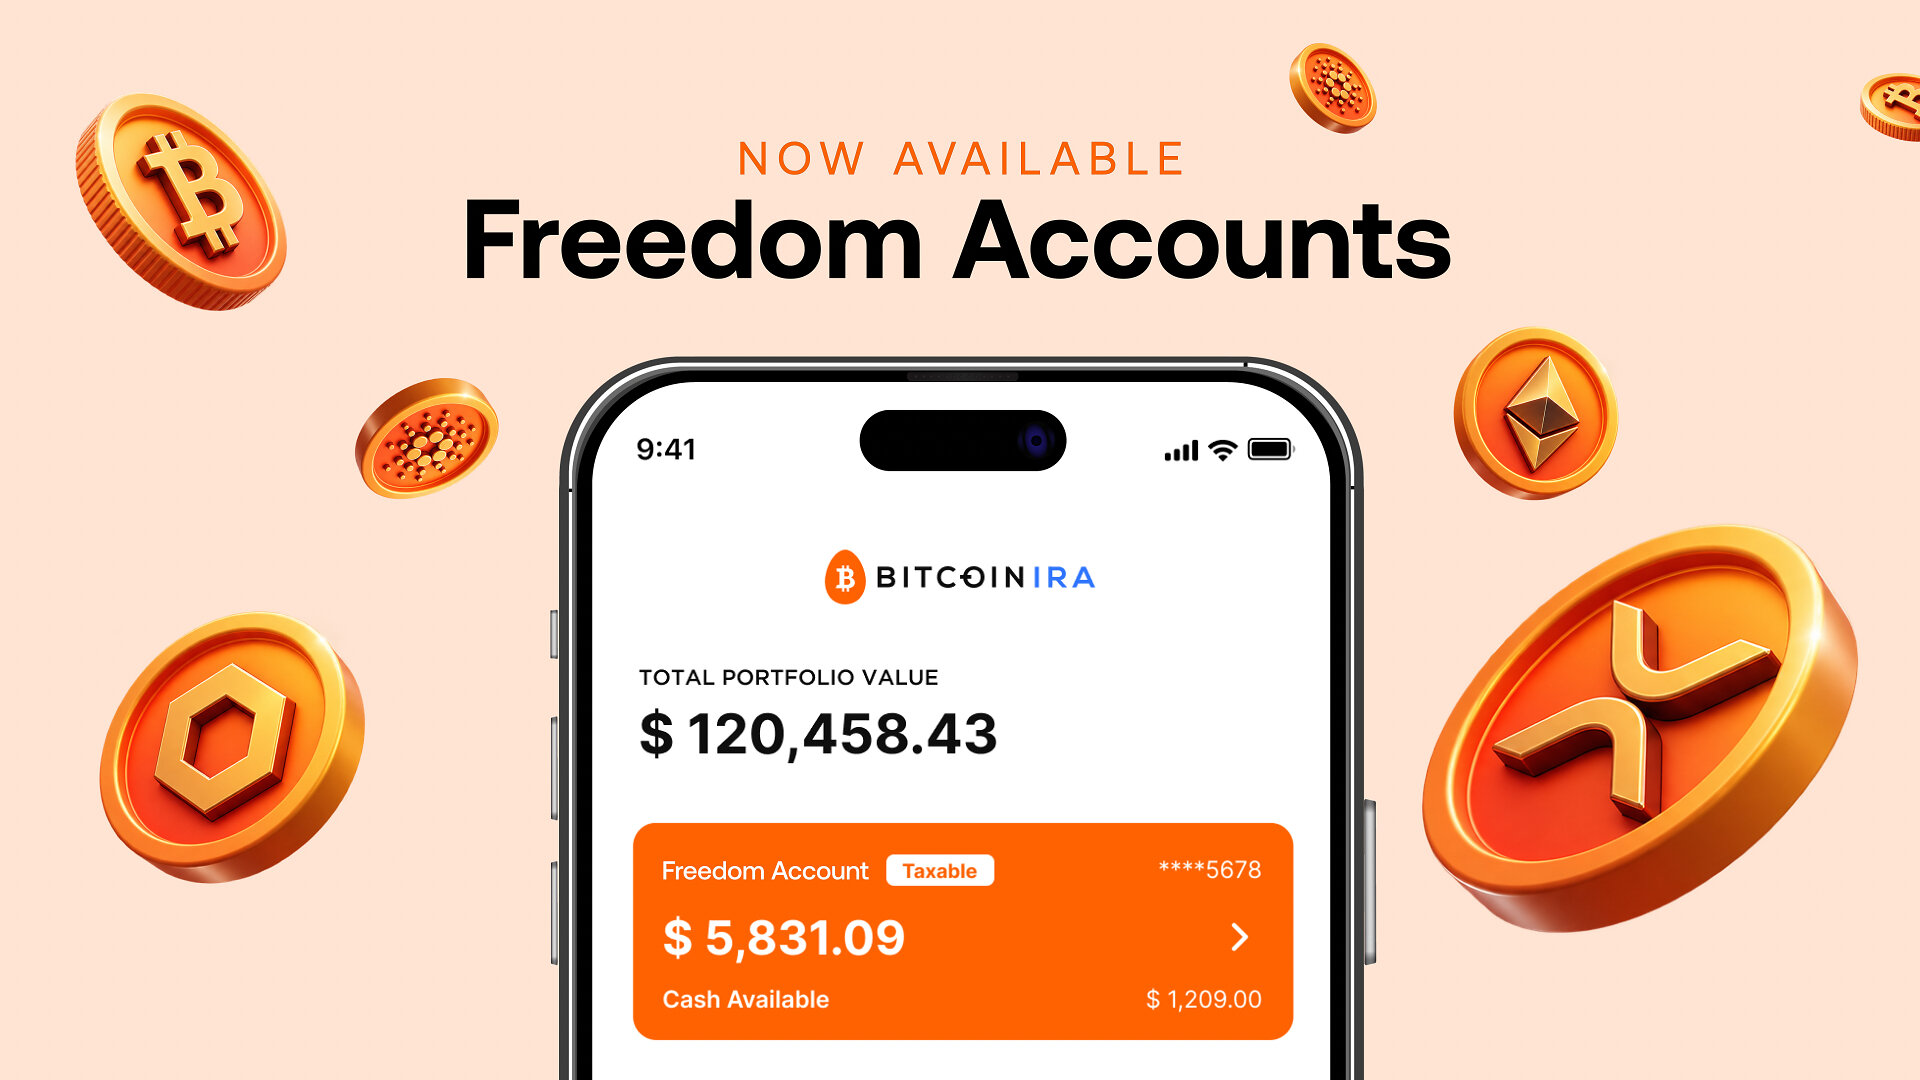
In September 2026, BitcoinIRA announced Freedom Accounts: taxable crypto accounts alongside the retirement account. Eligible in-kind deposits, staking, and bundles extend the relationship beyond IRA contribution limits. Published pricing differs too: 1% per buy or sell, with no monthly custody fee.
For other businesses, the copyable idea is the connection. Find people who want an existing asset but struggle with the account, paperwork, or custody around it. Make those steps easier. BitcoinIRA’s proposition works best when that assistance is worth paying for. Someone demanding private-key control, cheap frequent trading, or ready access to retirement money has a different problem.