A car can be chosen in an afternoon. Paying for it can occupy several years. Between those two timescales sits the work of Amit Kakkar, CEO of Spinny Capital, whose career has passed through banking, Toyota, equipment finance and the pre-owned car business. The vehicles change. The problem remains agreeably stubborn: a buyer has found something useful, desirable or both, and the money must arrive on terms that work.
The automobile business likes a photograph of the handover. A ribbon, perhaps. Keys held up for the camera. Lending has a less photogenic vocabulary: onboarding, disbursement, repayment, collections. Yet these words describe much of what happens before and after that photograph. Kakkar’s professional story belongs to this longer interval. It is concerned with getting a transaction across the line, then living with the obligations that follow.
He offers a concise description of the work on his LinkedIn profile: “I turn white spaces into profitable lending businesses.” It is a business-builder’s formulation, with a particular emphasis on the second half. Starting something is one test. Making the numbers hold together is another. His documented career supplies several settings in which that distinction matters, from an established car brand to an Indian financing business being built within an international equipment group.
A banking job with vehicles already in view
Before the Spinny chapter, there was retail banking. Toyota Financial Services India’s annual report records Kakkar’s previous position at ICICI Bank as assistant general manager and regional head for retail banking and assets, including auto and home loans. Vehicles were already part of his remit. The move to a carmaker’s financing business therefore carried an existing thread forward, rather than introducing a wholly separate subject.
He joined Toyota Financial Services India on 13 July 2011. His role was senior vice president and head of sales and marketing. The same annual report lists a postgraduate diploma in marketing among his qualifications. His education also connects him with Pune: he studied at the Symbiosis Centre for Management & HRD, with his LinkedIn entry recording the years 1999 to 2001.
The job title gives this early chapter its shape. Sales and marketing place a financial product close to the customer’s decision. A vehicle has to be sold; the means of paying for it has to be understood. The loan sits beside the object, although it comes with a rather different set of specifications. Horsepower can fit on a brochure. The cost of borrowing deserves its own careful reading.
From selling the proposition to running the operation
Kakkar subsequently became chief operating officer at Toyota Financial Services India. He then moved to Clix Capital Services, where he served as business leader for vehicles. These are the roles CNH would identify when announcing his next appointment. The sequence places him in both commercial and operational leadership, and then at the head of a defined lending business.
There is a useful difference between those responsibilities. A sales role is concerned with bringing customers in. An operating role has to consider what happens to the work once it arrives. A business leadership role brings those questions into the same room. Read that way, the titles form a progression through the machinery of lending, rather than simply a succession of increasingly impressive nameplates.
For a profile of Kakkar, this is the interesting continuity. His career has remained near vehicles while moving among different kinds of financial institution. It follows the purchase from several angles: the bank providing funds, the financing company attached to an automotive brand, and a broader lender with a vehicles business. Each setting gives the money a different organisational home.
When the vehicle was a tractor
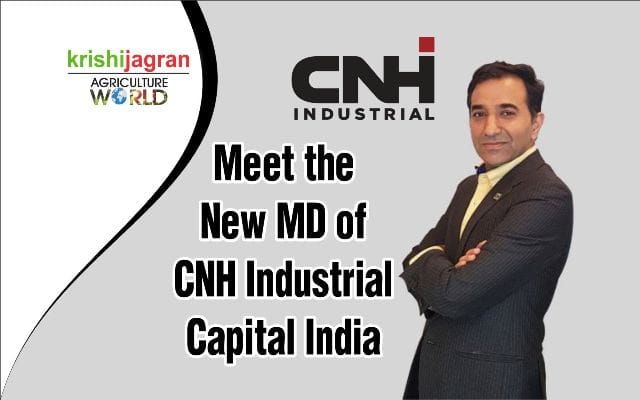
On 11 March 2019, CNH announced Kakkar as managing director of CNH Industrial Capital India. He would lead its newly established Indian business unit. The company described him as having more than 17 years of financial-services experience. Its customers and dealers were connected with New Holland Agriculture, Case IH and CASE Construction Equipment.
This chapter broadened the kind of vehicle involved. Agricultural and construction equipment put financing alongside machines bought to perform work. The purchase may concern a tractor or construction equipment, with the lending operation serving both end customers and dealers. The relationship between a useful machine and the funds required to obtain it becomes especially visible in that setting.
The appointment photograph has the customary corporate composure: dark suit, folded arms, a company name large enough to leave no doubt about the occasion. Its significance lies in the brief attached to it. Kakkar was taking charge of an Indian financing business at an early stage. The assignment put institution-building beside the day-to-day task of lending.
- ICICI BankRetail banking and assets
- Toyota Financial ServicesSales and marketing; then COO
- Clix CapitalVehicles business leader
- CNH Industrial Capital IndiaMD appointment announced, 2019
- Spinny CapitalCurrent CEO
India refused to be one spreadsheet
In May 2019, Kakkar discussed the regional differences in equipment financing. Some customers sought funding for a much larger share of the purchase than others. His account distinguished markets with more cash available from those requiring a greater loan component. The point was specific: financing requirements varied across India, and a single national description could conceal those differences.
The company’s finance professionals, called Capital Mitras, were deployed at more than 530 brand dealer outlets at the time. CNH also outlined plans for investment in technology to improve the process from customer onboarding to loan disbursement. These were features of the business during his tenure, rather than personal trophies to be hung on his biography.
Together, the details give that chapter a practical texture. The financing conversation had a physical location, inside a dealer network. It also had a process that technology could help organise. There is little glamour in the phrase “customer onboarding,” but a queue of unfinished applications would make its importance plain enough. The useful innovation is often the part that makes a purchase less laborious.
A used car brings its own financial questions
The Spinny chapter returned Kakkar to passenger cars through a pre-owned vehicle retailer. Registry-derived records place his appointment as a Spinny Capital director on 30 November 2021, followed by his appointment as whole-time director on 22 December. Current public listings identify him as CEO of Spinny Capital. The financial-services role connects his earlier experience with a different retail setting.
In comments published by Spinny, Kakkar described expanding relationships with banks and non-banking financial companies to address customers’ financing needs. He named Mahindra Finance, Poonawalla Finance, Bajaj Finance and Piramal Finance among the partners. His explanation emphasised their differing appetite for risk and their willingness to consider customers for loans.
The distinction matters to the story because the vehicle purchase and the lending decision involve different judgments. A customer may want a particular car; a financing institution still has to assess an application. Bringing several institutions into the conversation offers different possible routes through that decision. Kakkar’s remarks were about arranging those relationships, a concrete example of the work behind the retail transaction.
A marketplace can make a car easy to discover. The finance conversation deals with whether the purchase can proceed. That is where his career intersects the buyer’s experience: at the point when browsing turns into a financial commitment, and the appealing object on the screen acquires a repayment schedule.
The resulting story is about a lending executive inside a retail business. Cars give the work a visible destination. The financing operation brings its own responsibilities, its own partners and its own sequence of decisions. Understanding Kakkar’s role means keeping both parts of the purchase in view.
The arithmetic deserves the last word
By September 2026, Kakkar was discussing the other side of access: the obligations that come with borrowing. He urged borrowers to consider their available funds and the affordability of the resulting monthly payment when deciding on a down payment. He also stressed keeping money available for unexpected expenses, rather than directing every available rupee towards the purchase.
“Borrowers should retain a cushion for emergencies when deciding the EMI.”Amit Kakkar, September 2026
His comments extended to comparing the full borrowing cost, including fees and charges, and reading the annualised percentage rate in the Key Fact Statement. He singled out prepayment and foreclosure terms for attention when someone expected to close a loan early. The emphasis was on understanding the commitment in detail.
This gives the profile a fitting final scene, even without a ceremonial key handover. An executive whose work concerns financing vehicles is asking buyers to examine the terms that travel home with them. The questions are ordinary and consequential. How much leaves the account each month? Which charges apply? What happens if the loan is paid off ahead of schedule?
Amit Kakkar’s career can be read as a series of answers to the problem of financing a purchase. Banking, cars, equipment and pre-owned vehicles have supplied different versions of it. The object attracts attention first. His work concerns the arrangements that allow ownership to begin, and the arithmetic that continues after the camera has been put away.