Yaacov Martin’s route into banking involved a wedding registry and a barcode scanner. His future wife had taken him to Bed Bath & Beyond after their engagement. The store handed him a sturdy scanner with buttons and no screen. She preferred to sit out the shopping. He went around choosing things that other people might eventually pay for. As introductions to commerce go, it had certain advantages.
Martin, born in the United States and raised in Israel after his parents moved when he was about one, found the registry custom unfamiliar. The experience stayed with him. Years later, when childhood friend Shaul Weisband described a related business idea, Martin produced an old business plan. A domestic errand had acquired a business partner.
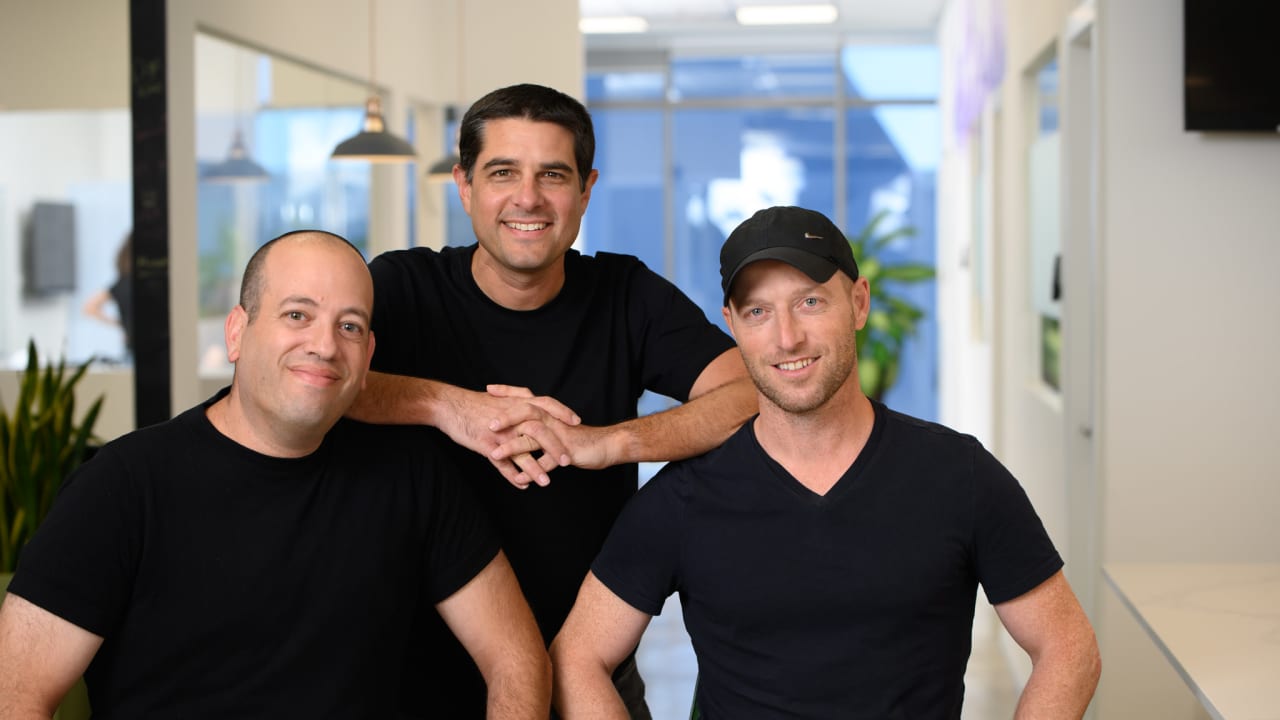
In 2011, Martin, Weisband and Meir Dudai founded Jifiti. The founding roles would become CEO, chief marketing officer and chief technology officer. Their first proposition concerned gifts. The question that eventually changed their business was how to get an unfamiliar shopping experience through a retailer’s very familiar checkout.
That is a less glamorous question than what to name an app. It also gets considerably closer to whether the app can work. A merchant can admire a demonstration and still have a payment system that refuses to cooperate. Martin’s career at Jifiti would become an extended education in the distance between those two responses.
The awkward part was the useful part
Martin arrived with experience beyond software. Before Jifiti, he had founded a consumer-goods import and distribution business. He also holds a law degree from the Hebrew University of Jerusalem. Retail, contracts and technology were already in the picture; banking infrastructure entered through the practical demands of getting a transaction completed.
Jifiti’s early work required a way for digital gifts to function inside stores. The team learned to use existing card-payment infrastructure, including virtual cards, to carry transactions. Rather than rebuild each retailer’s checkout, they could make the new experience work with payment mechanisms the retailer already accepted.
A gift might look sentimental to the recipient. To the people delivering it, the interesting part could be the plumbing. Once Jifiti had learned how to connect a new customer experience to existing payment systems, the same skill had applications beyond birthdays and wedding lists. That possibility became the basis of the company’s move into financing.
Martin has a suitably mortifying memory of the gifting years. Demonstrating the product to Barnes & Noble executives, the team chose the week’s bestseller. The resulting gift to the retailer’s technology chief was Fifty Shades of Grey. A bestseller list is an efficient selection tool. Its sense of occasion can be unreliable.
IKEA moved from customer to investor
IKEA became central to Jifiti’s next chapter. Gift registries had demonstrated an ability to build a branded retail experience around existing systems. Financing presented another use for that capability, especially when a customer’s purchase was substantial enough to require more planning than an ordinary impulse buy.
The relationship eventually acquired a financial commitment of its own. On August 31, 2021, Ingka Investments, the investment arm of the Ingka Group, announced a $22.5 million investment in Jifiti for a minority stake. Ingka operates IKEA stores; the distinction matters when describing who actually wrote the cheque.
The announcement followed commercial work already under way. IKEA and local banking partners had offered financing through Jifiti in Spain, France, Portugal and Belgium since 2019. The investment supported further product development and international expansion. The partnership had been tested in shops before it was celebrated in a funding announcement.
For Martin, that sequence helps explain his emphasis on relationships. An established commercial partner had become an investor. The connection rested on work both sides already understood. There is something refreshingly practical about a courtship in which the parties have first had to make the checkout function.
Ingka Investments’ minority investment in Jifiti, following an existing commercial relationship.
A CEO who answers the uncomfortable call
Partnership has also provided a cushion when things went badly. Martin recalls a large prospective deal collapsing near the finish. He called the lead investor first, expecting the hardest conversation. The investor accepted the setback and encouraged him to move ahead. Martin describes the person as a lasting mentor and trusted partner.
“Surround yourself with people whose values align.” It is one of Martin’s stated leadership principles, and the stories he chooses tend to put it to work. A supportive response to a failed deal can influence what a founder is willing to disclose the next time something goes wrong.
There was an earlier lesson in how quickly a commercial relationship can become uncomfortable. In 2013, a Jifiti demonstration featuring Amazon products prompted coverage that suggested a partnership was in place. No agreement had been signed. Martin received an urgent letter from Amazon. The episode later became a public cautionary tale about demonstrating a product before its commercial arrangements are settled.
It is easy to see why trust features so often in his account of the business. Jifiti asks institutions to depend on systems that sit inside consequential transactions. The software must function, and the people responsible for it must be candid when a complication arrives. Both requirements become more visible after the sales presentation ends.
“Most of my time is spent working with people.”
Yaacov Martin · April 2026
The office was part of the argument
Martin’s choices about work have a geographical expression. Jifiti established itself in Modi’in-Maccabim-Re’ut, where the three founders lived. Later, as the business grew, the team reconsidered whether it should move towards Tel Aviv’s established technology community. Staying close to home had implications for recruiting as well as rent.
Martin described lower office costs and a potential workforce tired of long commutes. Jifiti invested in its premises and chose a location near train and bus connections. Being outside the usual hub also meant making a deliberate effort to meet investors and peers. Convenience for employees came with some additional work for the company.
In a LinkedIn reflection on moving offices, Martin remembered the founders working from a tiny apartment. What made the new space meaningful to him was the culture and the relationships accumulated along the way. He thanked the people who had put the office together and looked forward to gathering colleagues from the United States and Amsterdam.
The detail gives a physical shape to a word that can otherwise become rather vague: culture. Someone chooses the building. Someone works out how to get there. A company’s priorities become easier to read when they appear in the daily journey to work.
The bank keeps its name
Jifiti’s public-facing modesty is part of its commercial design. The platform is white-labeled: banks, lenders and merchants can offer financing under their own brands. Martin has consistently argued that those institutions already have customer relationships worth preserving. Jifiti supplies the technology used to deliver the service.
His 2021 explanation to FT Partners placed particular weight on banks’ lending experience and funding resources. The intended division of work gave financial institutions technological help distributing their loan programs. It also spared them the task of building every retail connection themselves.
By 2024, Martin was discussing more of what happens after an application enters a system. In his account, rigid loan-management software, limited reporting and disconnected data could restrict a lender’s ability to adapt. His preference was for flexible components that could supplement existing systems and accommodate different programs and markets.
That is a revealing continuation of the original retail problem. At both ends of the business, Martin is concerned with the awkward meeting between established systems and a new way of using them. The customer may see a short application. Delivering that brevity requires a considerable amount of coordination elsewhere.
A small business has a checkout, too
The same thinking has taken Jifiti into business financing. In February 2024, Martin discussed its partnership with Canadian provider Tabit. The arrangement used Jifiti’s e-commerce plugins to help online business merchants offer Tabit’s installment loans and payment terms at checkout.
He explained the basic arrangement plainly: the merchant receives payment for the sale, while the buyer repays the lender over time. Business lending brings its own application processes and specialist institutions. It also appears in settings that can be less tidy than a consumer shopping basket, including orders, invoices and assisted sales.
For a founder whose first idea concerned wedding gifts, that is quite a change of shopping list. Yet the practical question remains recognizable. A buyer wants something; a seller wants to complete a transaction; a financial institution can supply financing. The opportunity lies in connecting them without making each encounter an entirely new engineering project.
The next customer may arrive with an agent
Martin is now applying that argument to artificial intelligence. In a December 2025 interview, he described an orchestration layer connecting roughly 30 outside providers. Coordinating those services could reduce the burden on banks of separately onboarding vendors for each task. The less visible parts of the lending process were still receiving his attention.
He also warned that banks would need systems capable of responding to AI agents. A financial product could have attractive terms yet struggle to reach a customer if software could neither discover it nor act on it. Martin presented this as a coming distribution challenge, requiring preparation rather than faith in an established name.
In April 2026, he described Jifiti’s priorities as expansion into additional markets, product work around AI and a larger partner network. “Most of my time is spent working with people,” he said. It is an ordinary-sounding description of a job that repeatedly involves getting different organizations to move together.
His June 2026 writing returned to customer loyalty. He argued that banks need to make credit available when a purchasing decision happens, and should consider serving existing customers before the need becomes urgent. The argument places usefulness at a specific moment above the comfort of an account relationship that already exists.
A registry scanner offered Martin an early glimpse of that moment: choosing an item, arranging payment, connecting people who occupy different parts of a transaction. His company has changed what it connects and who pays for the service. He is still occupied with what has to happen between wanting something and being able to carry it home.
In his own words
Watch, listen and read more about Martin’s work.
- Watch: Paris Fintech Forum interview · June 2026
- Listen: Fintech One-on-One with Peter Renton · December 2024
- Read: Jifiti’s evolution and Martin’s plans · April 2026
- Read: Why Jifiti chose Modi’in · March 2024
- Read: Martin on the lending moment and loyalty · June 2026
- Follow: Yaacov Martin on LinkedIn
- Visit Jifiti ↗
- Explore Jifiti’s articles and interviews ↗