Consider the small indignity of ordering dinner on your phone. You have chosen the food, accepted the delivery charge, and reached the final button. Then the checkout wants your card again. Or the payment fails. Dinner has become an administrative task. For foodpanda, operating across Asian markets, those little interruptions were a business problem. The interesting work happened behind the button.
- Visa Acceptance Solutions connects payment services that businesses would otherwise assemble themselves.
- Its customers include banks, software companies, and merchants with very different checkout problems.
- The useful lesson: simplify the connections before adding another payment feature.
foodpanda adopted Cybersource’s Token Management Service, part of the Visa Acceptance Solutions family. Card numbers became digital tokens. Payment gateways became easier to coordinate. Visa’s published case study reports a 3.3% improvement in payment success. A credential-management decision had become a customer-experience decision. The person waiting for noodles did not need to know the difference.
The button has a supply chain
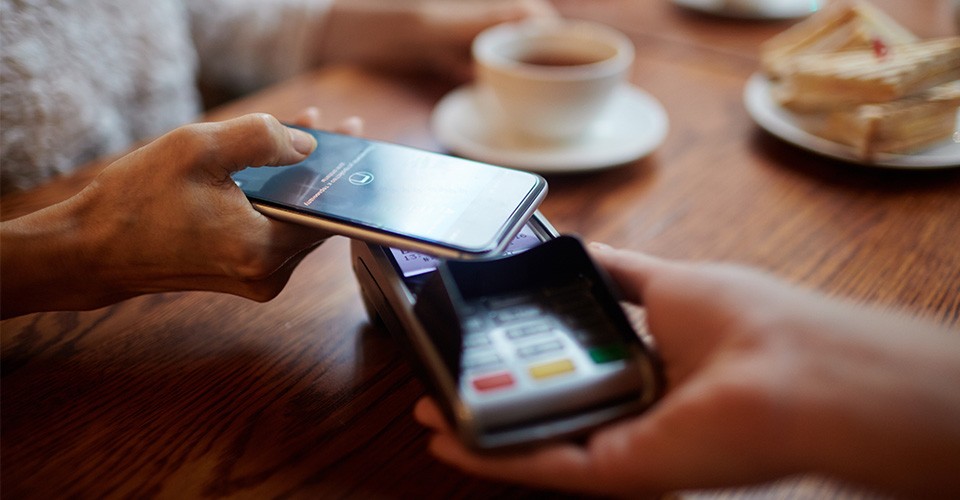
Visa Acceptance Solutions operates in the space between a customer’s intention to buy and the machinery required to finish the purchase. It provides online and in-person acceptance, fraud screening, authentication, token management, and dispute services. Banks, payment service providers, and independent software vendors can combine these capabilities into their own offerings. Merchants encounter them directly or through those partners.
The Visa Acceptance Platform is modular and acquirer-agnostic. An acquirer is the financial institution serving the merchant’s side of a card payment. Businesses can connect services while retaining choices about those relationships. The platform also supplies the less photogenic necessities: merchant onboarding, billing, transaction reporting, developer tools, and options to present the service under a partner’s brand.
- 01Collect payment
Online or in person - 02Protect credentials
Tokens and authentication - 03Evaluate risk
Fraud screening - 04Manage the aftermath
Reporting and disputes
Illustrative capabilities, not a transaction processing sequence.
“Open” here describes a commercial architecture: pre-integrated services and room for technology partners. There are APIs, sample code, SDKs, and testing facilities. The attraction is practical. A software company can add payments without treating every connection as a fresh engineering project. Its own expertise can remain closer to the business it serves.
A new name with an old engine
The business unit was unveiled in April 2023. Its history reaches much further back. Visa completed its acquisition of Cybersource in July 2010 for approximately $2 billion, expanding its online payment, fraud, and security capabilities. Visa acquired dispute specialist Verifi in 2019. Authorize.net brought an established route to smaller businesses. The 2023 move organized existing strengths around a partner-focused platform.
That distinction explains the apparent age puzzle. Visa Acceptance Solutions can be a recent organizational identity and still draw on decades of payments experience. Its expertise sits in the accumulated interfaces between merchants, processors, risk systems, and banks. In payments, knowing how those systems disagree can be as useful as inventing another way for them to talk.
The bank that chose its battles
Barclaycard Payments supplies the more revealing example. Visa’s customer account describes a bank facing pressure from faster-moving fintech rivals. Being inside a bank brought strengths, but it could also make rapid change difficult. Barclaycard acknowledged that it could not excel at everything, including building an entire solution in house. It chose a partnership and selected the capabilities it needed.
The constraint was the pace of product development. The response was to connect Visa’s acceptance capabilities to Barclaycard’s banking services, supporting its UK business and expansion into Europe. That is a useful account of what changed: the build decision. It illustrates a management choice with consequences for engineering, distribution, and the merchant experience.
“The dream is frictionless payments: To have the most seamless payments journey for your customers.”Arnaud Thulliez, Product Director, Accor
Payzli’s problem was closer to the shop floor. Stationary point-of-sale systems kept staff tied to a location. Its integration with Visa Acceptance Solutions supports mobile terminals, tokenization, and tools for service businesses. Visa’s case study describes onboarding in as little as 15 minutes, based on internal measurements in May 2024. The result concerns a specific workflow, rather than every merchant everywhere.
Good payments still need judgment
The product family handles different parts of the job. Decision Manager screens transactions for fraud. Payer Authentication checks cardholder identity. Token Management Service handles payment credentials. Verifi’s post-purchase tools address transaction confusion and disputes. Authorize.net serves smaller businesses. Together they create more choices, although the buyer still needs to decide which problem deserves attention first.
There are alternatives. Stripe offers integrated acceptance and developer tools. Adyen combines gateway, processing, acquiring, and risk on one platform. Visa Acceptance Solutions emphasizes modular services and choice across acquiring relationships. For a buyer with existing banking arrangements, that can matter. For a small seller needing a straightforward checkout, the breadth of an enterprise platform may add unnecessary work.
Improvement in foodpanda’s payment success rate after adopting Cybersource tokenization. A case-study result, not a forecast for other merchants.
Count the connections, then the cost
The economics depend on the product. Authorize.net advertises a US all-in-one plan at $25 monthly plus 2.9% and 30 cents per transaction, subject to eligibility. Its gateway-only plan costs $25 monthly plus 10 cents per transaction and a 10-cent daily batch fee; separate processing charges remain. Those prices describe Authorize.net plans. Enterprise buyers need terms covering their selected services and partners.
The ecosystem continues to add connections. In April 2026, Xetta announced a partnership linking acceptance with reconciliation and finance-system integration for Asia-Pacific institutions. In August, Bluefin announced an offering combining its card-present security infrastructure with Visa’s acceptance capabilities. Both address the same stubborn issue: a payment creates work before and after authorization.
The approach is worth copying at the decision level. Map where customers stop, identify which systems own the problem, and test a targeted change. Measure successful payments alongside fraud losses and operating costs. A modular platform helps when the connections match the business. It cannot repair an unsupported payment method, an unsuitable banking arrangement, or a team that never decides what success means.