Tyler Haahr had a private number in mind: one billion dollars. In January 2018, Meta Financial Group reached that market value. The bank his grandfather had started in northwest Iowa had become something its original customers would scarcely have recognized. Later that year, Haahr rang Nasdaq’s opening bell in Times Square. Then he handed over the chief executive’s job. A career can produce a rather inconvenient question just when the photographs suggest it has reached a satisfactory ending: what should all that experience be used for next?
For Haahr, part of the answer lay in Sioux Falls, at a former downtown YMCA building. By February 2020, he was helping lead a $3 million fundraising campaign for a Community Youth Center. The distance between a stock exchange ceremony and an appeal for after-school programming is considerable. The working method, though, was familiar: bring people together, explain why the arrangement makes sense, and persuade someone to commit.
A lawyer in the family bank
The family business began in 1954 as Storm Lake Savings and Loan. Haahr’s grandfather, Stanley, founded it; his father, James, later led it. Tyler belonged to the third generation, but his working life first took a different route. He studied accounting at the University of South Dakota and graduated with honors, then earned his law degree with honors at Georgetown. Before joining the bank’s staff in March 1997, he was a partner at Lewis and Roca in Phoenix.
That sequence matters. A family name can explain an introduction. It cannot, by itself, explain how someone learns to read a transaction. Accounting and law gave Haahr two ways into the same problem: what do the numbers permit, and what do the obligations require? A bank has to live with both answers long after the announcement has been made and the congratulatory telephone calls have stopped.
His early ambition was already pointed toward transactions. In eighth grade, he wrote a career paper about becoming a lawyer. At university, a professor encouraged him toward accounting as preparation for putting deals together. He graduated from law school in 1989 and became a law-firm partner in 1995. The eventual move into banking preserved much of what had attracted him to law: evaluating an opportunity, negotiating terms and deciding where a risk belonged.
In June 2005, Meta named him chief executive, promoting him from chief operating officer. His father remained chairman. The announcement described a business with seventeen locations and nearly $800 million in assets. Those details offer a useful starting photograph: a substantial regional institution, already expanding, with its next stage still being assembled. Haahr added the chairmanship in October 2011, following his father’s retirement from the board.
The business behind the plastic
Meta Payment Systems began in 2004. Brad Hanson, who founded the division, became an essential figure in the bank’s development. Prepaid cards opened a route beyond the geography of branches: the bank could work through partners and provide the infrastructure that made somebody else’s product function. A customer might know the name on a card while having little reason to think about the institution operating behind it.
In a 2018 interview, Haahr described a payments business that extended from gift, rebate and loyalty cards to reloadable and payroll cards. He also described sponsorship of ATMs at nonbank locations, including shops and hotels. These were different ways of reaching people through places and products they already used. The model made partnerships central to the bank’s daily work, alongside the familiar questions about deposits, credit and customer service.
Speaking to the Downtown Sioux Falls Rotary Club in June 2017, he put the ambition in a short phrase: “financial inclusion for everyone”. By then, the company had more than $4 billion in assets. The mission and the balance sheet belonged in the same conversation. Reaching customers through new channels meant building a business capable of supporting those channels, with enough operational discipline to make the promise usable.
The distinction between an attractive idea and a functioning banking product can be expensive. Software, partners, controls and supervision all have their say. For a leader trained to work on agreements, the challenge extended well beyond getting signatures. The institution had to perform the agreement repeatedly, at scale, for customers whose needs did not wait for the next strategy meeting.
Growth had a compliance bill
The expansion included setbacks. In October 2010, the Office of Thrift Supervision issued a directive affecting Meta’s payments business. The bank discontinued iAdvance and certain tax-related programs. In announcing that year’s results, Haahr acknowledged the directive and said the company had begun addressing the regulator’s concerns. Meta expected the discontinued products to reduce payments gross profit in the following fiscal year.
The consequences appeared in the accounts. For the six months ended March 31, 2011, Meta reported $3.5 million in net income, against $6.4 million a year earlier. Alongside the discontinued programs, it identified a $1.5 million goodwill write-off and $1.2 million in legal and consulting expenses connected with the regulatory matters. Growth in financial services has an administrative underside. Sometimes it is the part that determines what happens next.
By August 2014, the Office of the Comptroller of the Currency had released Meta from its consent order. Haahr credited employees, additional staff and enhanced systems. The company’s year-end announcement also reported three newly signed prepaid program managers after the release. The sequence gives the expansion a less effortless shape: restrictions, spending on the institution, then permission to move forward with more business.
Finding the other half of the balance sheet
In December 2014, Meta acquired the commercial loan portfolio and related assets of AFS/IBEX and hired its team. Insurance premium financing became a new division. Haahr explained the purpose in banking terms: deploy the national deposit franchise, diversify the business and replace lower-yielding securities with loans. The acquisition joined a source of funding to a team that knew a particular kind of borrower.
Refund Advantage followed in September 2015, adding tax refund-transfer software and services. EPS Financial and Specialty Consumer Services joined in 2016. The company was accumulating businesses around payments, tax processing and specialized credit. The names sound like entries in a corporate filing because they are. Together, they explain more about Meta’s change of direction than a fashionable technology label could.
A broader national lending platform, supported by the bank’s deposit base.
Crestmark brought that approach into clearer view. Announced in January 2018, the all-stock transaction paired Meta’s deposits with a commercial lender offering asset-based loans, equipment finance and government-guaranteed lending to small and midsize businesses. Meta also expected the added lending to soften seasonal swings in its payments and tax businesses. A balance sheet can be diversified by finding activities whose busy seasons do not all arrive together.
The preparation was painstaking. Management teams met in Sioux Falls in July 2017. Haahr and chief financial officer Glen Herrick briefed the boards, and due diligence followed. Later discussions covered personnel and reporting arrangements. These are the unphotogenic details that decide whether a combination will function: who is responsible, what is being acquired, and how the two organizations will work together after closing.
The acquisition closed on August 1, 2018. The closing announcement valued the stock consideration at $316.1 million using Meta’s July 31 share price. Crestmark remained based in Troy, Michigan, and Mick Goik was named to lead Meta’s commercial finance division. The national lending platform arrived with people who already knew how to run it. Haahr’s dealmaking involved bringing expertise into the institution as well as adding assets.
The bell, and the handover
Two days earlier, on July 30, Haahr had rung Nasdaq’s opening bell to mark Meta’s twenty-fifth listing anniversary. It was an anniversary celebration, rather than an initial public offering. The distinction makes the occasion more interesting: the public company had been there for a quarter-century, while the business inside it had changed substantially.
The summer also supplied a reminder that expansion and quarterly profit do not march in step. Meta’s fiscal third-quarter net income fell to $6.8 million from $9.8 million a year earlier. The quarter included student-loan loss provisions and acquisition expenses, even as revenue increased. A photograph can hold a celebration still. A set of accounts insists on keeping several things in view at once.
On October 30, 2018, Hanson succeeded Haahr as CEO. Haahr remained nonexecutive chairman during the transition, and the new chief executive did not report to him. His chairmanship ended in January 2019. The formal arrangement gave the successor authority while allowing time for assistance. After more than two decades on the staff, leaving was a process with dates and responsibilities of its own.
“My world is in Sioux Falls.”Tyler Haahr · February 2020
A smaller map, more room on the calendar
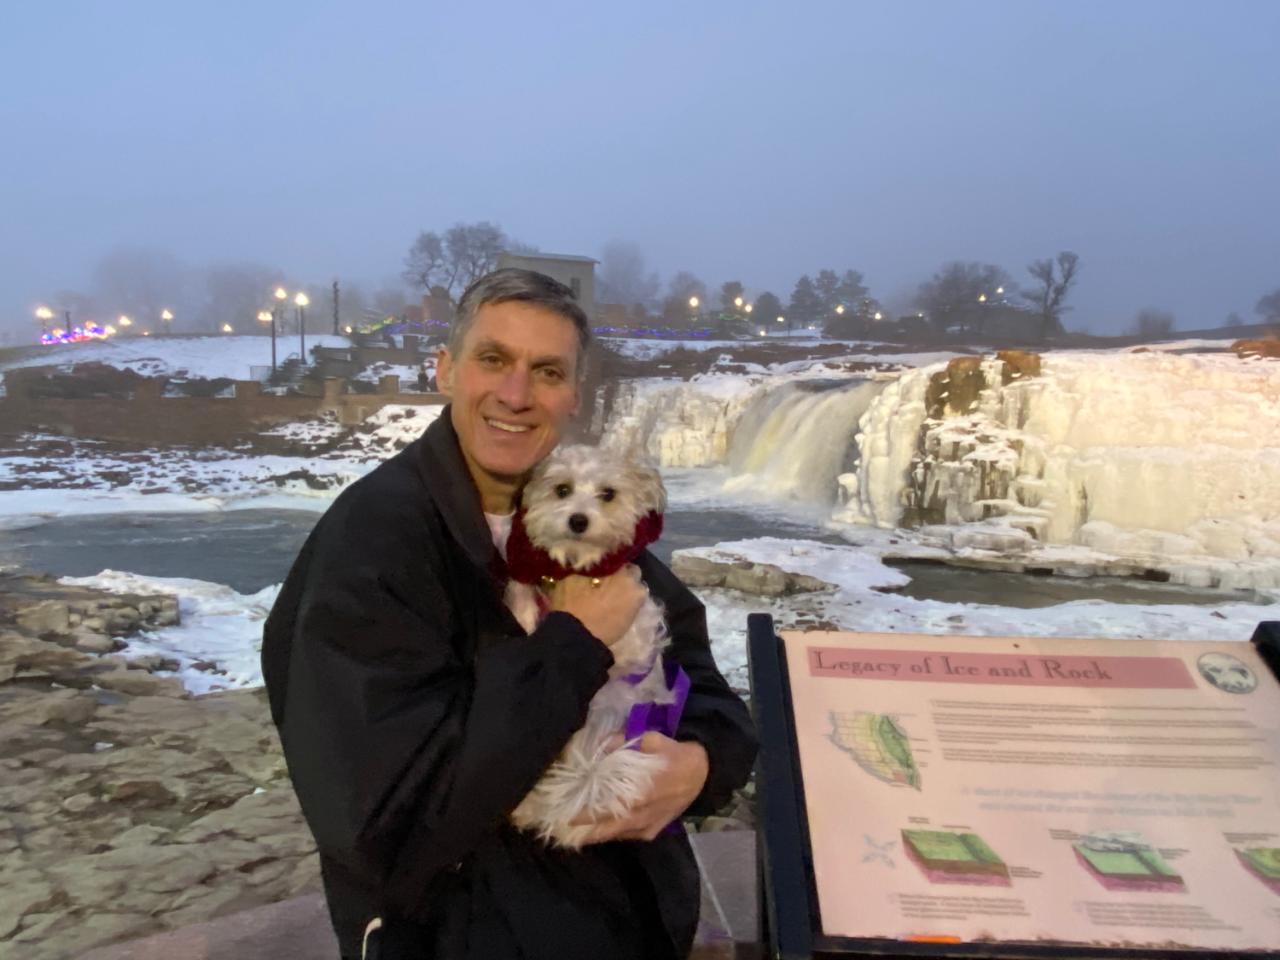
By early 2020, Haahr’s agenda included the youth-center campaign, family travel and a rescue dog named Stevie. He had also been pursuing visits to every NBA arena. Retirement had acquired both a fundraising target and a walking companion. Asked about the community work, he said, “my world is in Sioux Falls”. The phrase gives his later choices a location without requiring them to resemble his former job.
He joined Lloyd Companies’ board in January 2020. Lloyd’s current biography lists him on its Governance and Investment Committees, and also records his continuing service on the Sioux Falls YMCA board, which he previously chaired. The work draws on familiar experience while changing the setting: evaluating investments, participating in oversight and remaining involved in the city where he lives.
MetaBank took the Pathward name in 2022, after his departure. Haahr’s place in its history belongs to an earlier transition, from the family thrift to a bank built around national partnerships and specialized lending. His present chapter returns the attention to Sioux Falls. The arithmetic still matters. So does deciding which people, institutions and projects should receive the hours that the arithmetic has helped make available.
Continue reading
- Lloyd Companies · current board biography
- Tyler Haahr on LinkedIn
- MetaBank’s successor · Pathward
- 2018 profile · career and leadership
- 2020 interview · life after the CEO role
- The Wall Street Transcript · interviews
- Crestmark acquisition · closing announcement
- Meta’s CEO transition agreement
- 2010 results and regulatory context
- 2014 results and consent-order release