The bill was $120. That is the detail to keep in mind. When Ohad Samet began receiving calls about an overdue store-card balance in 2013, he could afford to pay it. What stayed with him was the experience of being asked. If this was unpleasant for someone with the money, what happened to someone without it?
Samet and his brother Nadav set out to change that experience. Their work became a family of businesses under TrueML Technologies. One, TrueAccord, collects debts for other companies. Another, TrueML Products, sells Retain: software that lets organizations run digital collection outreach under their own brands. The distinction matters. You can hire a collector, or buy the machinery and operate it yourself.
- Retain personalizes the timing, channel and approved message for each account.
- Its buyers include lenders, credit unions, collection agencies and law firms.
- The commercial promise: better repayment outcomes with less manual outreach.
The reminder has three moving parts
Picture a collection manager with thousands of past-due accounts. Sending everybody an email on Tuesday is straightforward. Deciding who should receive an email, who might respond to a text, and when to try again is a different job. Retain puts that second job into software.
Its Heartbeat decision engine evaluates engagement and historical interactions to choose a next step for an individual account. The variables are familiar: message, channel, time. The ambition is to stop treating a customer’s next interaction as a slot in a fixed campaign. Each response can inform the next decision. That is the product’s stated approach, rather than evidence that every portfolio will improve.
message
channel
time
There is a revealing boundary here. Retain’s FAQ says its collection software uses custom machine learning, choosing from content approved by the client, rather than having ChatGPT or Gemini compose messages. In a business where wording carries consequences, deciding among permitted options is a useful job for a machine.
The bank already had email
The most instructive Retain customer story begins with an organization that possessed the obvious tool. An unnamed top-10 bank could send email. But as early delinquencies grew across different products, its outreach lacked a strategy for choosing channels and timing. Hiring more call-center agents would add cost and logistical difficulty. The bottleneck was partly a decision problem.
In its November 2024 account of the deployment, Retain reported up to a 1,000-basis-point decrease in roll rate compared with the bank’s in-house approach across product lines. Roll rate measures movement into a later delinquency stage. A lower rate means fewer accounts slipping further behind.
Up to 10 percentage points lower roll rate.
Vendor-published, anonymized case study, November 2024. A portfolio-specific result, not a universal forecast.That translation is important: 1,000 basis points equals ten percentage points, not a ten-percent relative improvement. The published story offers a reason to test the product. It does not establish what another bank would achieve. Different balances, account ages and repayment options can change the result. A useful buyer would ask to see comparable accounts, not just an impressive number.
“We see better interactions with digital than just relying on phone calls”Kyle Sutter, Atlanticus
Testimonial published by Retain
What the subscription is really buying
Retain’s customers are organizations managing substantial account volumes: creditors, nonbank lenders, credit unions, debt buyers, agencies and collection law firms. Public testimonials name Atlanticus and Reach Financial. The attraction is operational control. The lender’s name stays on the communication while Retain supplies the delivery and decision-making machinery behind it.
The product extends beyond dispatching reminders. Its published suite includes a client portal for reporting and content management, mobile-oriented payments and electronic model validation notices. Contact validation, opt-out records, approval workflows and communication logs support the client’s compliance process. Those controls help explain why a collections buyer might choose specialized software over a general-purpose messaging tool.
The pricing page offers custom quotes. The financial question for a buyer is therefore broader than a subscription: what happens to the total cost of recovering a dollar? Staff time, integration work and delivery operations belong in that calculation. A cheaper message is useful only if the whole process produces a worthwhile outcome.
Retain occupies a market that includes other digital receivables platforms, such as collect.AI, alongside internal systems and outsourced agencies. Personalization alone cannot settle the comparison. The fit depends on the organization’s market, existing systems and appetite for running collections itself. Retain’s particular proposition combines account-level decisions, a client-branded experience and collection-specific controls.
The humans inside the machinery
TrueML’s company story has an apparent contradiction: a business promoting automation also depends on people with unusually specific expertise. Someone must understand email deliverability. Someone must approve content. Someone must make account data flow correctly. A decision engine cannot rescue a message that never reaches the customer.
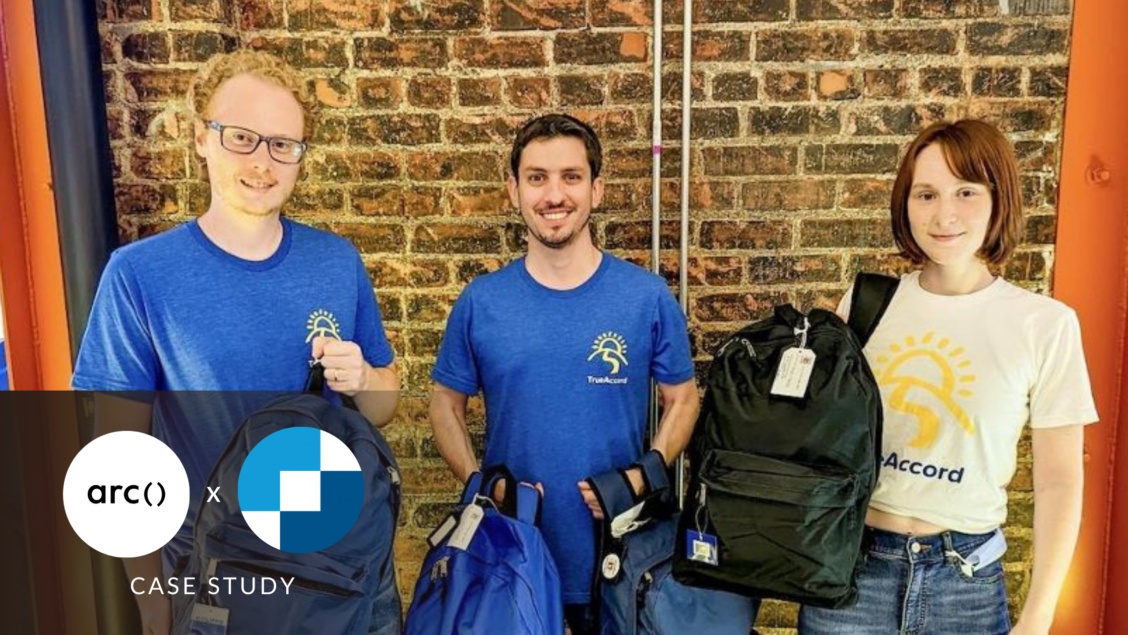
A 2024 Arc recruiting case study supplies a glimpse of that work. The partner reported helping TrueML hire 20 engineers and product managers in Argentina and Mexico, while reducing hiring time by 30%. Those are Arc’s figures. They also underline a prosaic truth: automated financial services require a substantial organization behind the screen.
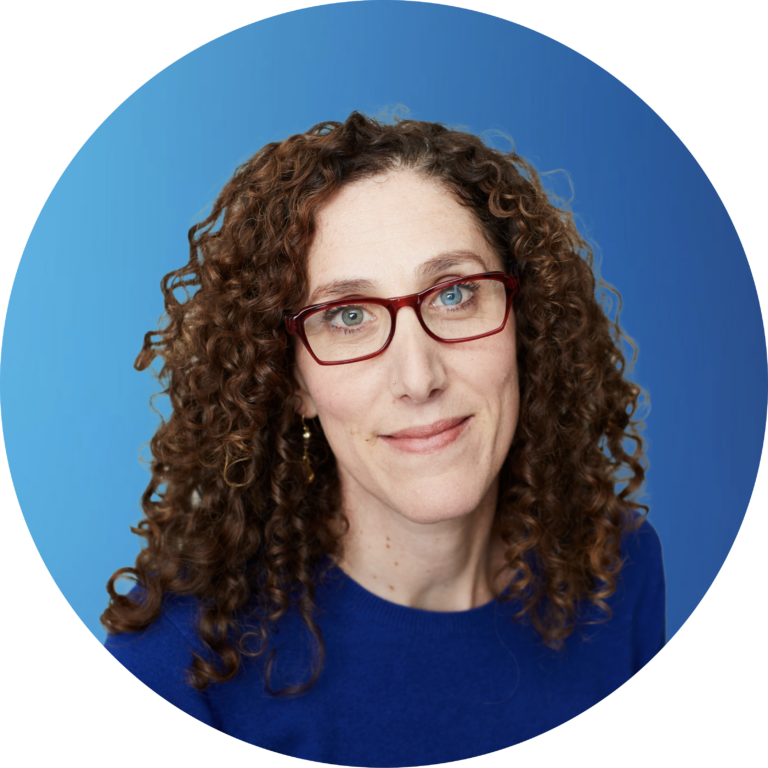
THE PRODUCT LEADERSHIPNaama BloomTrueML’s chief marketing officer and Retain general manager. The customer experience has an executive owner, too.
A test worth copying
The practical lesson is to make the theory measurable. As an evaluation approach, give comparable account groups the existing outreach and an adaptive alternative. Count repayments, movement into later delinquency, opt-outs, complaints and total operating cost. Opens and clicks can explain behavior; they cannot substitute for the outcome.
There are limits to what better communication can accomplish. A person who lacks money does not acquire it because a reminder arrives at a convenient hour. Inaccurate contact details and unsuitable payment options also constrain the process. The real opportunity is narrower, and useful: remove avoidable friction between a customer who can respond and a business that needs to hear from them.