Bruce Springsteen’s songs have many uses. They can fill a stadium, accompany a long drive or rescue a wedding reception from an unfortunate playlist. In Tony Minella’s account of Eldridge’s investments, they also invite a comparison with commercial property. A catalog can generate income, he explained in October 2025, without requiring the owner to maintain a building. Somewhere, a landlord with a leaking roof might have paused to reconsider his profession.
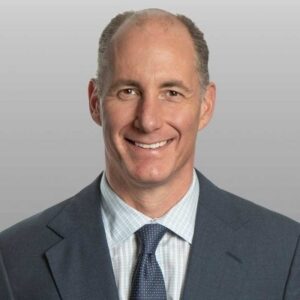
The comparison offers a way into Minella’s career. He is a co-founder of Eldridge, its President, and the chief executive of Eldridge Capital Management. His board appointments include A24, gamma, Flexjet and Cain. The names suggest several different worlds. His earlier jobs supply a common vocabulary: corporate credit, investment committees and the investment portfolio of an insurance business. Across those worlds, the question of what keeps earning remains useful.
That perspective now faces a new test. Eldridge has brought investment teams together and begun welcoming outside capital alongside its own. Minella’s second act involves making a business developed around affiliated money intelligible and useful to other investors. The transition gives his story a particular tension. Experience owning and financing businesses can help win a client’s attention. The client still needs to know what that experience will mean for the money entrusted to it.
The education before the recognizable names
Minella attended Avon Old Farms and earned an A.B. in Economics at Bowdoin College. Bowdoin’s alumni publications place him in the class of 1998. Those are modest details beside the institutions that follow, but they establish the beginning of a professional record that is often swallowed by the size and variety of Eldridge’s interests. Before the film studios and music catalogs comes an economics graduate entering the business of investment.
At Guggenheim Investments, Minella became co-head of the Corporate Credit Group and co-chaired its Investment Committee. He subsequently served as chief investment officer of Security Benefit. The sequence matters. Corporate-credit work concerns businesses’ capacity to meet obligations. Insurance investing adds the task of putting a pool of capital to work within an institution that has its own promises to keep. These are different responsibilities, connected by the need to think beyond the initial transaction.
Credit also changes the questions worth asking about a company. An equity owner may enjoy the prospect of an expanding market. A lender must consider how the business gets through the less enjoyable parts of the calendar. A loan has a maturity. Interest has a due date. A fine presentation is welcome, but it cannot make a payment. This helps explain why Minella’s later remarks return to earnings, liquidity and how management teams respond to change.
- 1998Bowdoin class of 1998
A.B. in Economics - Before 2015Guggenheim corporate credit
Security Benefit investing - 2015Co-founds
Eldridge Industries - 2025Leads integrated
capital management platform
A partnership gets an organizational chart
Eldridge Industries was founded in 2015 by Todd Boehly, Minella and Duncan Bagshaw. When the group announced its restructuring in December 2024, it described Minella and Boehly as having worked together for approximately twenty-five years. That is a substantial stretch of shared professional experience. A partnership of that duration has a history extending well before the public begins recognizing the companies associated with it.
The restructuring proposed an asset management and insurance holding company with approximately $74 billion in assets under management. There would be two divisions: Eldridge Capital Management and Eldridge Wealth Solutions. Minella would lead capital management as CEO, supported by co-presidents Todd Gilbert and Nicholas Sandler. Boehly would chair the new executive committee. The announcement gave separate names and responsibilities to activities that readers could otherwise easily fold into one enormous investment basket.
The capital management plan brought together businesses and teams associated with Maranon Capital, Security Benefit, Stonebriar, Cain and Panagram. Its stated strategies covered corporate credit, general partner solutions, real estate credit, and sports, media and entertainment. The operating challenge was evident in the list: people with different specialties would need to work within a shared organization. An investor in a property loan and an investor in entertainment rights might share a parent company while requiring quite different expertise.
Assets under management across the proposed asset management and insurance holding company.
A company-scale figure, separate from personal wealth.Sandler’s explanation of the transition gives it a practical foundation. The investment platforms had been developed to find assets for Security Benefit’s balance sheet. Their ability to originate investments eventually exceeded what affiliated capital could absorb. Bringing in other investors could put more of that capacity to work. Consolidation also allowed teams to coordinate opportunities that might once have been handled separately, or even pursued in competition with one another.
For Minella, that turns a collection of investment capabilities into a broader management assignment. Shared operations may help a business grow, but outsiders require a proposition they can evaluate. They need a strategy, a structure and people accountable for each. His move into the CEO role sits at that junction: the group’s history of building its own businesses meets the demands of institutions deciding whether to invest alongside it.
A catalog with no repair bill
Minella’s comparison between music rights and real estate was economical in both senses of the word. Eldridge had bought stakes in catalogs associated with Springsteen and the Killers. Discussing those investments at the 2025 Milken Asia Summit, he emphasized the cash flow and the absence of property maintenance. A familiar cultural object became a financial asset without losing its familiar name. The song stayed a song; the ownership rights carried another set of possibilities.
“You don’t need to do tenant improvements, you don’t need to maintain a building”Tony Minella, on music catalogs, October 2025
The analogy has limits. A building and a catalog face different risks, contracts and markets. Its value is that it reveals what catches his attention: the relationship between an asset and the income it can continue producing. Music offers a particularly vivid example because listeners experience the product directly while the economics of rights ownership remain mostly backstage. The investor follows a different part of the performance.
His board work places him closer to the people making those businesses run. A24 produces and distributes film and television. gamma operates in multimedia and music. The latter’s launch announcement in 2023 named Minella and A24 co-founder Daniel Katz to its board. It also identified Larry Jackson and Ike Youssef as gamma’s co-founders. Here the connection becomes more specific than a general interest in entertainment: a credit-trained investor joins the governance of a business led by music executives.
A board appointment, a loan and an equity investment each create a different relationship with an enterprise. Reading Minella’s career through all three helps explain its range without turning every company connection into a claim of personal authorship. Film production belongs to filmmakers and their collaborators. An investment executive’s contribution concerns the capital, oversight and organizational decisions that help a company pursue its work.
The pleasures of a difficult market
A brief exchange in Singapore supplies a less formal glimpse of his public manner. At the October 2025 investment-outlook panel, Minella discussed opportunities in a future private-credit default cycle and called the prospect fun. Todd Sisitsky, president of TPG, suggested he would have chosen a different word. Minella held his ground. The conversation captured the peculiar professional enthusiasm of people whose opportunities can increase when a market becomes more complicated.
It is an enthusiasm with financial conditions attached. Minella’s point included preserving liquidity for such a period. Having money available when others need it is different from merely anticipating trouble. His comments link preparation with the ability to act: understanding an investment, deciding when to exit and retaining capacity for what comes next. A credit downturn may be an interesting topic onstage. In a portfolio, it becomes a sequence of decisions with consequences.
Eldridge’s September 2025 issuance offered a concrete reminder of the platform’s credit roots. Eldridge CLO 2025-1 was a $500 million collateralized loan obligation, with J.P. Morgan as lead arranger. Tarek Barbar and Andrew Ward were named co-portfolio managers, and John Passaglia led capital markets. A CLO combines loans within a financing structure whose different securities carry different payment priorities. It makes the allocation of risk part of the product itself.
Then, in January 2026, Eldridge and Carlyle AlpInvest announced the closing of Eldridge Diversified Credit Fund I. The arrangement combined equity commitments from AlpInvest and co-investors with debt financing from BNP Paribas. Together they were expected to provide up to approximately $1.5 billion in investable capital. The initial portfolio included loans and leases purchased from Eldridge and its affiliates. The outside-capital chapter had acquired a specific vehicle and named financial partners.
Announced January 22, 2026. Investable capital includes debt financing.
The borrower’s future arrives early
Minella’s recent remarks about artificial intelligence fit the same concern with what businesses can keep earning. At the 2025 Middle East and Africa Summit, he discussed using technology to shorten research tasks and help investment staff reach answers sooner. His emphasis moved beyond producing more spreadsheets. Faster access to information should leave investors with more room to assess it, and with responsibility for the conclusions they draw.
The time horizon is especially relevant to credit. A company borrowing for several years may encounter a very different competitive environment before the loan matures. Minella has publicly questioned what happens when management fails to adapt to available technology during that interval. In that reading, adopting a tool inside an investment firm also helps its people understand the changes facing the companies they finance.
Eldridge’s August 2026 investment in Sudolabs gives that interest an organizational expression. The Slovakia-based business develops custom AI systems for enterprises. The announced partnership aimed to support deployment at scale, with day-to-day operations continuing under co-founder and CEO Jozef Petro. The transaction adds a technology business to the group’s relationships while pointing toward the practical work of connecting new systems with existing company operations.
The next audience
“The next phase is growing a consolidated asset management platform,” Minella said in May 2026. The statement has the plainness of an operating assignment. It follows a career spent moving between investment decisions and the organizations that carry them out. His responsibilities now include a platform whose outside investors have their own objectives, constraints and expectations.
The songs, films, loans and leases remain distinct businesses and instruments. Minella’s career brings them into the same conversation through an interest in their economics and the people managing them. The second act asks whether that experience can serve a wider audience. A catalog can keep collecting income after the singer leaves the stage. For the investment manager, another performance is always approaching: the decision about where the next dollar should go.