The awkward moment in a startup’s life often arrives after the demonstration. The software works. The prospective customer nods. Then someone asks who else uses it, who will approve it, and where it belongs in the working day. In legal services, The LegalTech Fund has made that distance between interest and adoption part of its investment strategy. A cheque gets a company started. An introduction may get it through the door.
- It invests in early legaltech companies, globally, through Series A.
- Its second fund closed at $110 million, nearly four times its first.
- Its offer includes industry access: advisors, introductions, a founder Lab, and an annual Summit.
The customer who changed the question
There is a revealing episode in co-founder Zach Posner’s account of how he reached legaltech. After his education business was acquired, he helped a friend start a vendor-risk company aimed at schools. Their law firm wanted the same service for itself. In a September 2025 interview with vLex, Posner described a change of direction on incorporation day. The customer had supplied a better answer than the original plan.
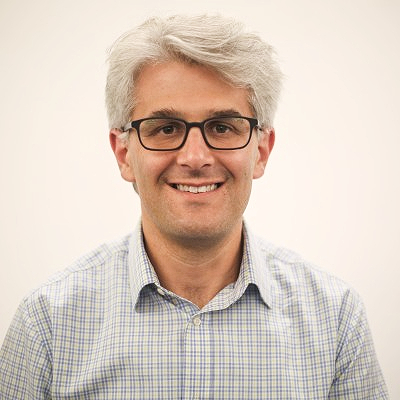
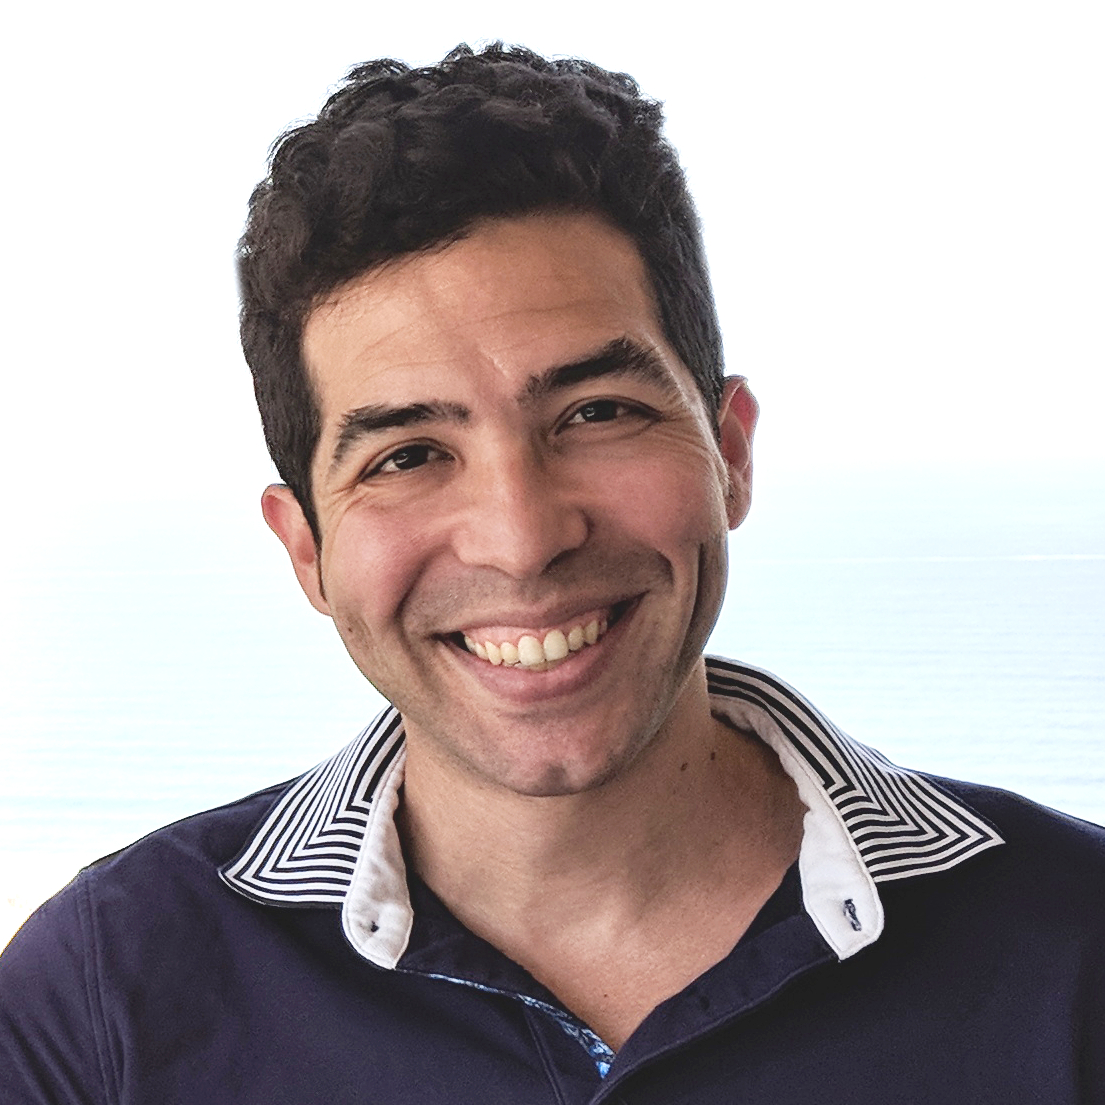
The lesson was about demand, and about entry. Law firms could be difficult to win and durable customers once convinced. Posner saw entrepreneurs facing an industry without enough connecting tissue. TLTF, which identifies 2021 as its founding year, would specialize in that terrain. Sam Elhag brought technical product and operating experience; Posner brought finance, strategy, and business development. Their wager was that knowing the profession could improve the odds of building for it.
A fund with buyers in the room
The financing tells the story. McDermott Will & Emery announced a $10 million anchor investment in 2021. By June 2022, TLTF’s first fund had closed at $28.5 million. In November 2025, Fund II closed at $110 million. McDermott, now McDermott Will & Schulte, committed another $10 million. Consilio joined as a lead investor. Clio, Docusign, Harbor, Orrick, and Thomson Reuters Ventures also participated.
These are institutions with reasons to care what legal startups build. A founder needs capital, but also feedback from people who understand purchasing, implementation, and the client’s actual problem. Strategic investors can bring those perspectives. That is the fund’s distinguishing proposition: specialist capital connected to the market it hopes to change.
Limited partners supply capital to the investment vehicles; TLTF deploys it into young companies. Founders receive investment and support. The law firms, corporate departments, and consumers using portfolio products sit further along the chain. Keeping those roles straight matters. A $110 million fund is neither a $110 million software business nor evidence that every investment has succeeded.
Legaltech includes the unglamorous bits
TLTF’s portfolio makes its definition of legaltech pleasantly untidy. Flo Recruit addresses legal hiring. HelloPrenup brings legal planning to couples. Entegrata works on legal data and analytics. Intelligent Legal Solutions builds workflows for private-funds lawyers. There is no single customer or universal application here. There are specific jobs, with different buyers, economics, and reasons to resist changing.
That breadth places TLTF between software investing and the wider business of legal services. A founder building a repeatable product can approach it for capital and operating connections. A legal buyer can explore the portfolio for relevant tools. Generalist venture firms and corporate investors offer alternatives, though the boundaries overlap: Thomson Reuters Ventures is both a direct investor and a TLTF backer. The useful distinction is the depth of sector attention.
The trouble after the subscription
An August 2026 investment in Telon makes the adoption problem unusually concrete. TLTF described legal teams purchasing AI platforms and then struggling to turn capability into working processes. Telon builds playbooks and agents, embeds legal operators, and delivers work inside the client’s existing systems. In this account, the software purchase happened first. Ownership of implementation was the missing step.
The investment suggests a practical test for founders: describe the work that changes after the sale. Who uses the tool? Who checks the result? Who takes responsibility when a process needs judgment? Those questions are less theatrical than a demonstration, and rather more revealing. An excellent model can still leave a buyer with another unfinished project.
“We think technology is going to enable the unbundling of a law firm.”Zach Posner / vLex interview, September 2025
A smaller door for an earlier company
The LegalTech Lab, launched in 2025, gives earlier founders another route in. Selected companies can receive up to $250,000, alongside mentorship and industry connections. Its published criteria include annual revenue below $500,000, a full-time CEO, a product demonstration, and headquarters in the United States, Canada, United Kingdom, or Australia. An MVP is preferred. The investment ceiling is an offer to selected companies, rather than an automatic entitlement.
A founder can prepare a demonstration around a narrow, consequential workflow and show why a buyer will adopt it. The broader lesson is to recruit distribution knowledge early. That approach depends on a willing buyer and a product that solves a problem within their constraints. Relationships cannot rescue weak demand. Nor does a broad global investment mandate erase the Lab’s narrower eligibility rules.
The conversation continues outside the demo
TLTF also builds places for those relationships to form. Its website reports more than 1,000 introductions annually and over 120 advisors. The invite-only Summit brings founders, legal executives, investors, and academics together; its fifth edition is scheduled for November 16-18, 2026, in Scottsdale. This is an organized attempt to shorten the distance between people who usually attend different meetings.
In March 2026, TLTF and Harvey announced plans to invest together. With Law.com, they also advanced Pathways, a scenario project looking toward 2040. The future remains an argument, rather than a settled destination. For a reader building something today, the fund offers a useful starting question: whose working day improves enough that they will invite you back?