A blurry payslip is an unlikely place to look for the next venture-backed business. Yet it captures what Kaya Founders is increasingly interested in: the stubborn, expensive work left over after everyone has downloaded the app. A customer can apply for credit online while, somewhere behind the screen, a human being still squints at documents and copies figures into a spreadsheet.
The Philippine investment firm has money for entrepreneurs who want to fix such problems. In November 2025, it announced the final close of its $25 million second fund, organized around two vehicles with unusually useful names: Zero to One and One to Ten. One helps a business begin. The other backs the effort to turn early promise into repeatable growth.
That structure expresses Kaya’s proposition to founders. Different stages demand different kinds of help. An idea needs testing, a team and someone willing to take an early risk. A business with customers needs stronger operations and evidence that expansion will pay. Kaya puts both within its remit, alongside a network of people who have run companies themselves.
The operators have changed seats
Founded in 2021, Kaya brought together Paulo Campos, the former chief executive of Zalora Philippines; Lisa Gokongwei-Cheng, the media entrepreneur behind Summit Media; and Constantin Robertz, co-founder of logistics company Locad. Ray Alimurung, formerly CEO of Lazada Philippines, became a general partner. E-commerce, media and fulfillment gave the group experience with the practical complications that sit behind an attractive growth chart.
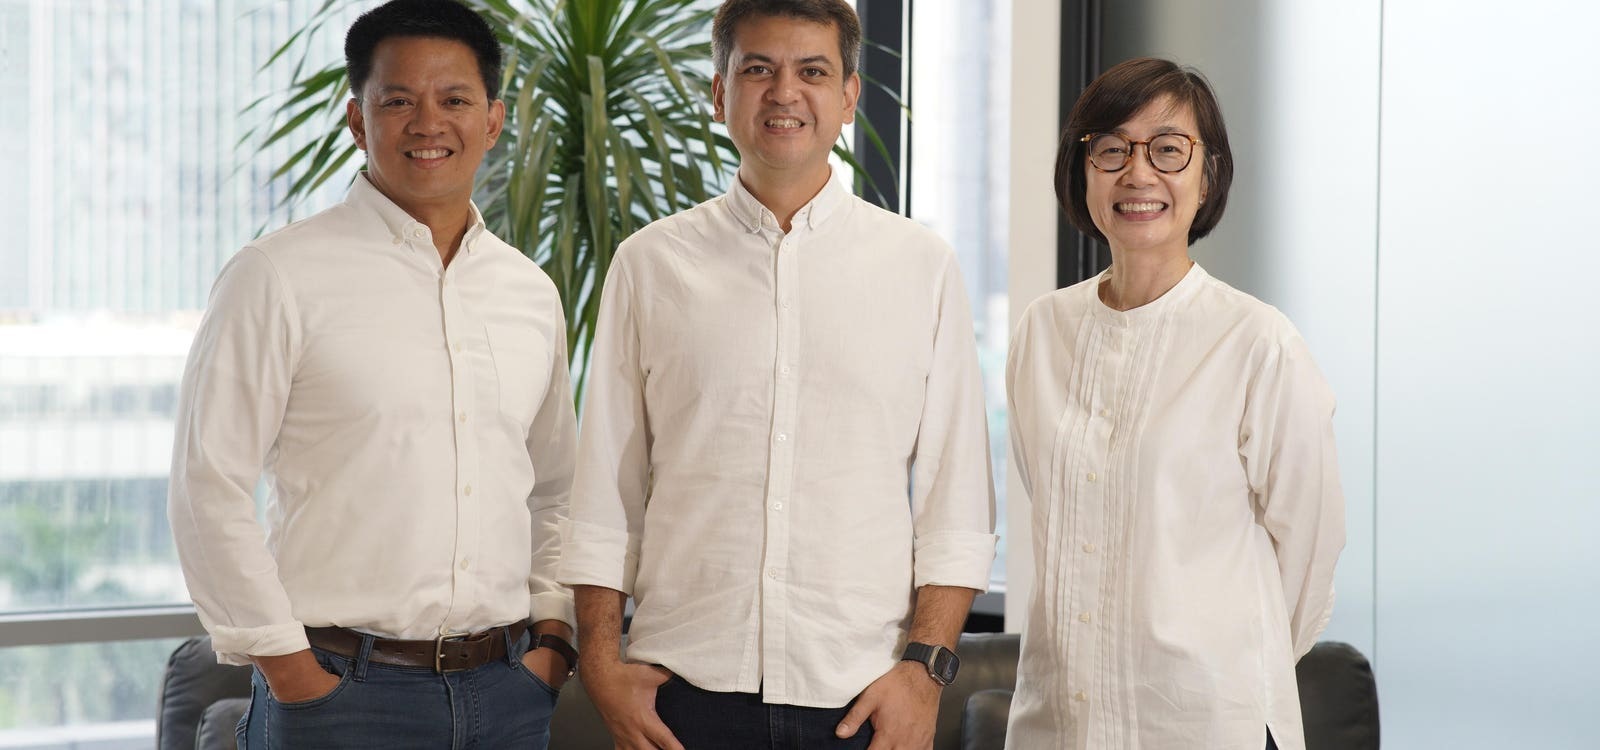
Campos linked the opportunity to changes accelerated by the pandemic: people becoming more comfortable shopping, working and managing daily tasks digitally. First-time founders were emerging to serve them. In his account, those entrepreneurs needed experience and emotional support as well as funding. Kaya’s local presence was part of the proposed answer.
Today, its team page lists Campos as founding managing general partner, Gokongwei-Cheng and Alimurung as general partners, and Robertz as founding director. Managing director Raya Buensuceso works alongside investment, people and finance staff. The structure suggests a firm that expects supporting companies to require work beyond selecting them.
Kaya serves two constituencies. Founders receive investment and support; the investors committing money to its funds seek financial returns. Its language about opportunity and inclusion sits within that commercial arrangement. Backing useful companies and earning venture returns are both part of the ambition. Neither follows automatically from the other.
Two funds, two different jobs
Zero to One targets pre-seed ventures, including teams that have yet to launch. One to Ten targets seed-to-Series A companies showing signs of product-market fit and a route toward profitability. The later-stage vehicle can also invest in promising companies emerging from the earlier one. Follow-on support is an option, not an entitlement.
Pre-seed
Test the idea.
Build the business.
Seed to Series A
Show the fit.
Finance the next stage.
The investment range announced in 2023 was $150,000 to $500,000 per company. That gives a sense of the scale Kaya was designed to handle, rather than a standing offer to every applicant. Its business is venture investment, with ownership and financing terms negotiated around individual companies. A founder should read the deal terms as closely as the check amount.
The fundraising history requires equally careful reading. The two funds reached $12 million in commitments in 2023, then $18 million in March 2024, before the $25 million final close in November 2025. Those are successive totals. They describe the same fundraising effort accumulating commitments over time.
Three closes, not three separate funds. Values in US dollars.
The final-close announcement named Pavilion Capital, Concentric Equity Partners, Gabriel and Geraldine Sunshine, AMTI and Filipino family offices and technology operators among the investors. It also set out an intention to back 10 to 20 additional startups over three years. In April 2026, Kaya’s leadership described approximately $30 million in firm-wide assets under management and more than 40 portfolio companies.
The distinction matters. Fund size measures capital committed to an investment strategy. It tells a reader something about Kaya’s capacity to write checks, but does not measure its revenue, valuation or realized investment performance.
The paperwork gets a venture round
Kaya’s recent writing points to a more specific diagnosis of the Philippine digital economy. In an April 2026 opinion article, Alimurung and Buensuceso argued that financial applications had advanced faster than the shared systems underneath them. Repeated identity checks, fragmented information and manual reconciliation remained costly. Their argument shifts attention toward the infrastructure that makes everyday transactions work.
Two investment notes published in June show how that thinking becomes a portfolio. Kita processes inconsistent financial records into information lenders can use. Its proposed inputs are recognizable: photographed payslips, bank statements, handwritten records and e-wallet screenshots. The product is available through an API for integration into lending software and a web portal for credit teams.
Kaya described a lesson from conversations with lenders: having data does not mean an institution can efficiently turn it into a lending decision. Documents and review procedures can still hold up the work. That is a specific reason to refine an investment thesis. The problem becomes clearer when the investor follows the task through the organization.
“There is no room for ego on our team.”
Kaya Founders’ public manifesto
Moneta addresses another part of this process, helping lenders analyze borrower records and prepare credit assessments. Kaya’s June 2026 investment note put pricing at approximately $2 to $15 per report and reported more than 34 paying customers in Indonesia. Those are the investor’s reported figures, but they provide a concrete view of the proposition: software sold against the cost and capacity of manual underwriting.
The appeal is straightforward. A lending institution has a task it must perform, a staff cost attached to it and a reason to process suitable applications faster. Software can be evaluated against that work. It still has to earn trust inside a consequential decision process. Speed is useful only when the output is reliable enough to act on.
A brand needs more than a checkout button
Credit infrastructure is one part of a broader portfolio. Kaya’s holdings include payment provider PayMongo, logistics platform Locad, e-commerce enabler Etaily and small-business software company Peddlr. These businesses address different portions of commercial life: accepting money, moving stock, selling across channels and keeping records. Their customers buy specific services rather than a general promise of digital transformation.
The firm has also invested in consumer ventures, agriculture and healthcare. Its approach allows it to move between sectors while looking for recognizable problems. A founder need not squeeze a business into one fashionable category to fit that mandate. The stronger question is what technology changes about the service, its cost or its reach.
Kaya’s 2024 investment themes offered a pointed observation about consumer brands. A website and social advertising had become insufficient foundations for distribution. Crowded channels and rising acquisition costs meant brands needed to think across marketplaces, live selling, customer relationships and relevant physical locations.
That is a useful lesson for readers building their own businesses. Distribution deserves attention while the product is being developed. If every sale depends on paying to reacquire the same customer, a polished storefront will not repair the economics. The task is to understand who returns, through which channel, and why.
Kaya retired a program, then joined forces
Kaya has changed its own operating arrangements too. In February 2024, it joined forces with Founders Launchpad and discontinued its Manila Venture Program as a separate accelerator. The program’s assets moved into the combined effort. The stated purpose was to consolidate resources and improve the support available to founders.
The move offered a practical division of labor: accelerator support, investment experience and operating guidance brought together in one program. It is a documented change of method, without requiring a dramatic story about a failed predecessor. For a small organization, choosing which activities to run with a partner can matter as much as choosing what to launch.
Kaya’s current programs page also presents a Future Founders Program for aspiring entrepreneurs and a Product Design Fellowship connecting emerging talent with portfolio-company work. This extends its reach to people who may have useful skills before they have an investable company. Its public manifesto emphasizes experimentation, candid feedback, integrity and different perspectives.
There is an institutional relationship as well. Kaya became an official co-investment partner of the National Development Company’s Startup Venture Fund, with a later memorandum of understanding announced alongside the 2025 close. The partnership aims to expand access to startup capital. It adds another potential route for supporting companies within the Philippine market.
A useful pitch starts with a specific headache
For a founder considering Kaya, the practical entry points are its website, public contact address and programs. Its stated geographic focus makes a credible connection to the Philippines or Southeast Asia relevant. Its stage focus favors businesses early enough for venture funding to influence how they develop.
There are alternatives, including Foxmont Capital Partners, regional investors, angels and accelerators. The useful comparison concerns stage, check size, market knowledge and the help a company actually needs. Kaya’s combination of operator experience, two investment vehicles and talent programs supplies specific things to compare.
The portable lesson is to describe the work before describing the market. Identify the customer, show the troublesome task, establish what it costs and explain how the proposed business improves it. Then show why that improvement can support a growing company. That test applies whether the product is a lending tool or a consumer service.
Some businesses will not suit this model. A profitable local operation with limited expansion needs may have little use for venture capital. Software that depends on inaccessible data or customers unwilling to change their processes may struggle despite a large theoretical market. Kaya’s newer bets make the question refreshingly concrete: can this business remove a costly obstacle often enough that customers keep paying?