Consider a handbag that changes owners twice. At first, it is an object of desire: a particular shape, a familiar clasp, the promise of becoming slightly more like the person you imagine yourself to be. Later, it becomes something practical. Eventually, someone brings it back to the company that made it. A craftsperson cleans it, repairs it, perhaps remakes it. The bag has acquired a history. The company has acquired another opportunity.
This is one way into Tapestry, the New York company behind Coach and Kate Spade. Its business involves leather and taste, certainly. It also involves a less photogenic question: how many different ways can a familiar brand become relevant again? After an expensive attempt to expand its portfolio collapsed, that question became harder to avoid.
- Coach and Kate Spade are the current portfolio.
- The Capri acquisition ended in November 2024.
- Coach grew in fiscal 2026; Kate Spade kept shrinking.
01The house that kept the shop names
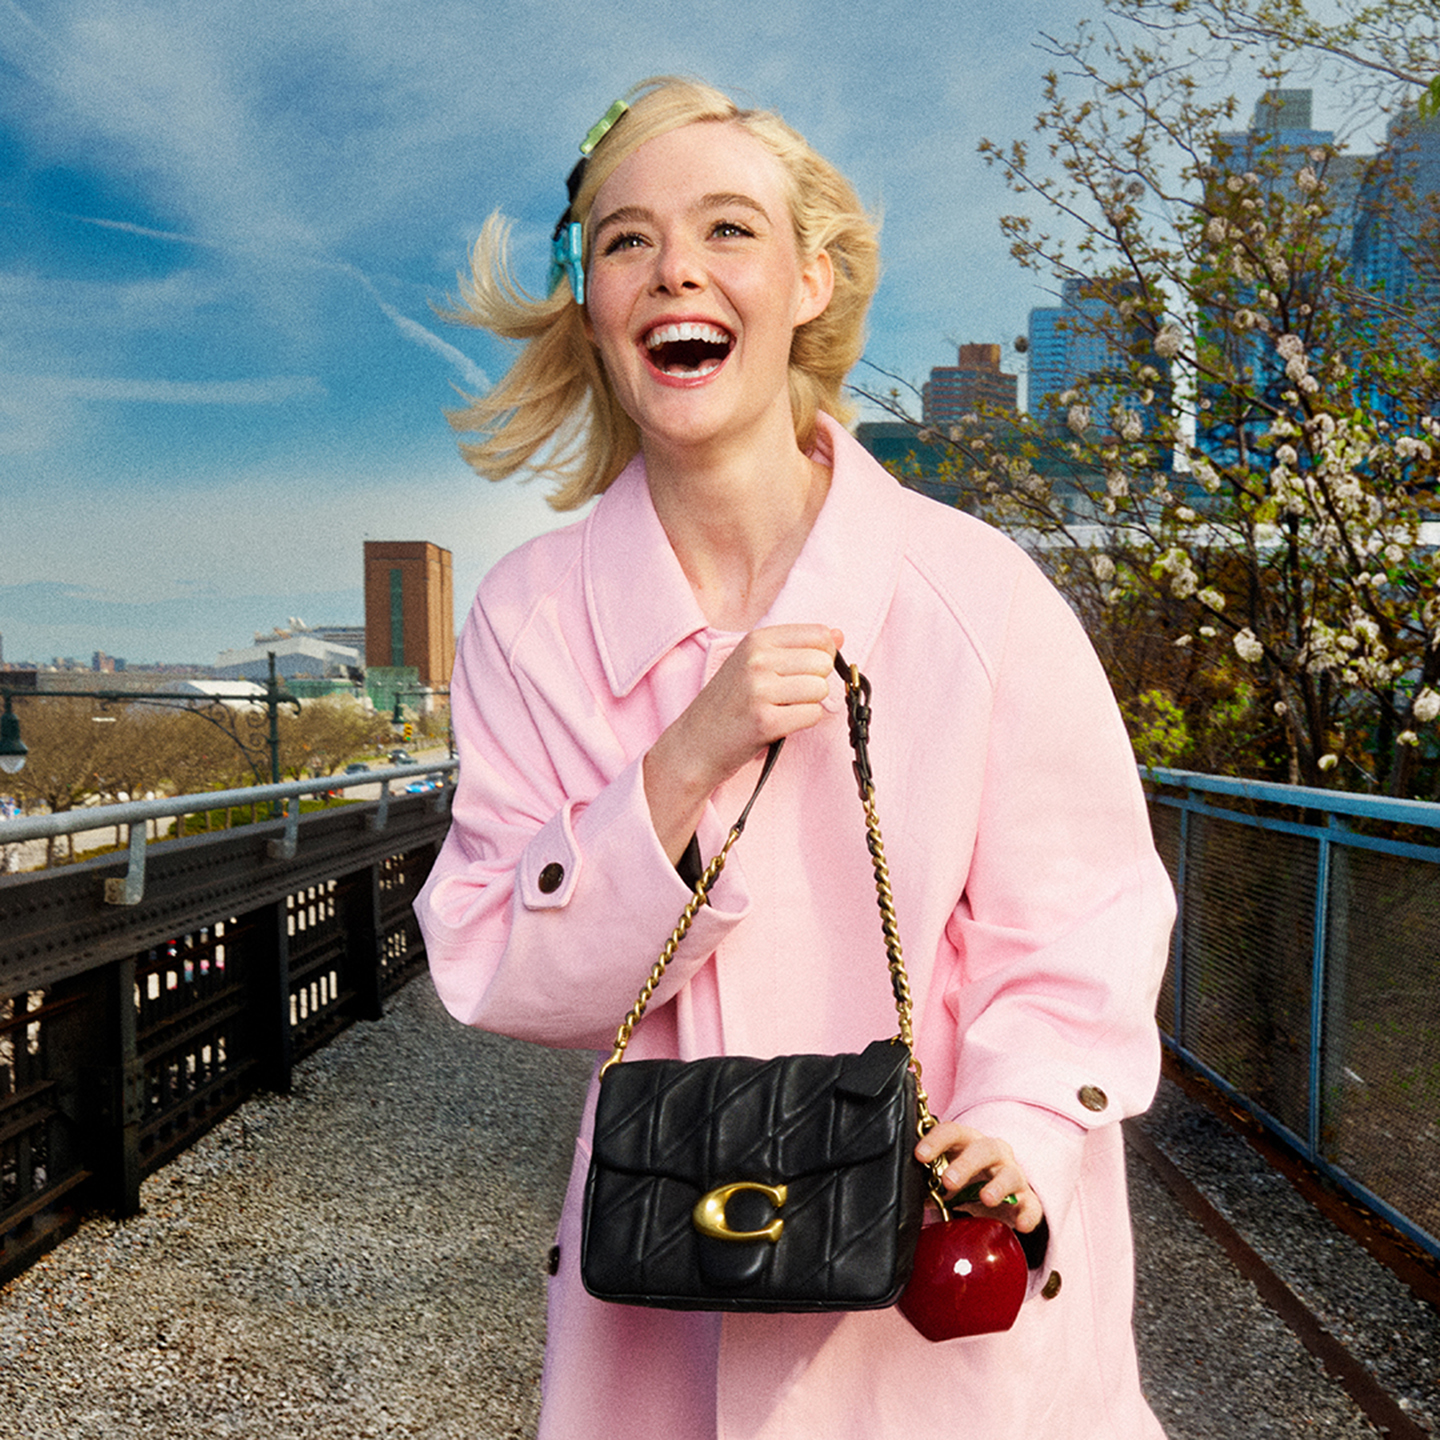
Tapestry sells handbags, wallets, accessories, shoes and other lifestyle products. Customers usually encounter it under a brand name, in a store or on a shopping site. Coach offers leather heritage and New York fashion; Kate Spade brings a colorful, playful identity. Both operate in the territory often called accessible luxury, where shoppers want a designer purchase they can justify without entering the highest luxury price tiers.
The corporate name arrived in 2017, after Coach bought Kate Spade for roughly $2.4 billion. Calling the parent Tapestry gave the expanding group an identity beyond its original brand. Coach itself dates to a six-artisan New York workshop in 1941. That distinction matters: the parent can change its strategy without asking customers to change the name on their bags.
The arrangement combines separate creative identities with shared capabilities. Each brand has its own design and merchandising team. The group supplies scale, operating expertise and customer analysis. Revenue comes through owned stores and e-commerce, wholesale customers and licensing. The expertise lies in coordinating design, sourcing, merchandising and distribution while preserving reasons to choose one label over another.
02The acquisition that met a wall
In August 2023, Tapestry announced an $8.5 billion agreement to acquire Capri Holdings, owner of Michael Kors, Versace and Jimmy Choo. The appeal was straightforward: more brands, more reach, a larger American fashion group. But the Federal Trade Commission challenged the transaction, arguing that combining close handbag competitors would harm competition. A federal court granted a preliminary injunction in October 2024.
The first decisive failure was the deal’s regulatory path. Tapestry and Capri terminated their agreement the following month, saying the legal process was unlikely to finish before the contractual deadline. Tapestry agreed to reimburse approximately $45 million of Capri’s expenses. It also said it would redeem $6.1 billion of acquisition-related notes at 101% of principal plus accrued interest. Those figures describe specific obligations, rather than a complete bill for the abandoned transaction.
“We have always had multiple paths to growth”Joanne Crevoiserat · November 2024
What changed was the available route. Tapestry said future acquisitions would wait until Coach remained strong and Kate Spade had returned to sustainable sales growth. Then, in August 2025, it completed the sale of Stuart Weitzman to Caleres. Its portfolio had narrowed to two brands. The work ahead would be more visible because there were fewer places to hide uneven performance.
03Two labels, two report cards
The contrast is striking. Coach’s fiscal 2026 sales rose 24% on a reported basis. Kate Spade’s fell 10%. Both belonged to the same parent, yet the outcomes diverged. Shared infrastructure clearly does not guarantee shared desirability. Each brand still has to persuade someone that this particular bag belongs in their life.
Tapestry’s September 2025 Amplify plan put consumers, product, experiences and people at the center of its growth agenda. Beneath those broad words were concrete choices: lead with handbags and leather goods, pursue selected footwear opportunities, and prioritize Greater China and Europe internationally. Kate Spade’s reset involved a more focused assortment and fewer promotions, according to the subsequent proxy statement.
That is a patient bargain. Reducing promotional activity can make the business healthier, but it does not automatically bring customers back. The result has to show up in products people want at prices they accept. Michael Kors, Longchamp, Tory Burch and many others compete for that decision. Shoppers can also postpone it. A handbag is rarely an emergency.
04The second life is part of the first sale
For customers, the useful possibilities extend beyond buying something new. Coach offers repairs and complimentary lifetime leather care. Its (Re)Loved program accepts eligible bags for credit and gives selected pieces another life through restoration or remaking. Eligibility matters; a damaged bag is not automatically a trade-in. Still, service makes the claim of longevity tangible.
Coachtopia, launched in 2023, approaches the same problem earlier. Its design brief considers reuse and remaking from the outset, with products using recycled, repurposed or renewable materials. These programs offer practical experiments in keeping materials useful. They also expose a demanding condition: circular systems need suitable products, skilled labor and customers willing to participate. A launch announcement alone cannot establish the environmental result.
05What another company can borrow
The transferable lesson is to keep the customer promise specific. Give creative teams room to express different identities, then make the supporting operations useful to both. Measure the brands separately. Offer care that matches the durability claim. Above all, distinguish acquiring another business from earning another purchase. Those activities require different evidence.
The approach becomes harder when product appeal fades, shoppers cut discretionary spending or higher costs outrun what customers will pay. Tapestry’s own contrasting brand results make the limitation plain. A smaller portfolio can sharpen attention. It still takes a product someone wants to carry out of the store.